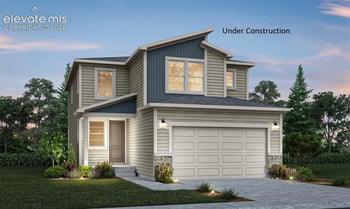
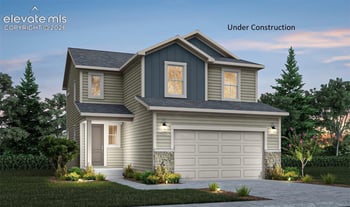
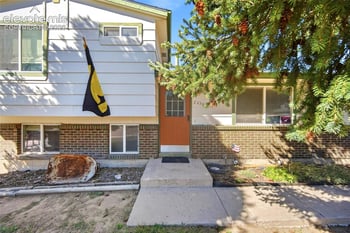
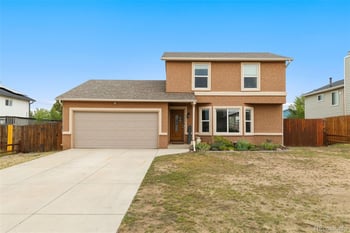
New - Just Now
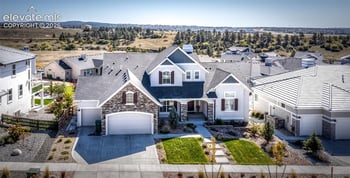
$1,375,000
Active
5
Beds
6
Baths
4503
Sqft
0.2309
Acres
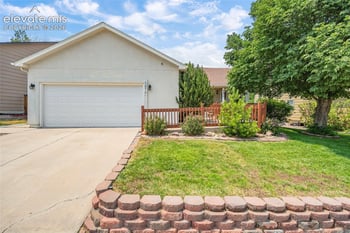
2363 Merlot Dr, Colorado Springs, CO 80921
MLS#: 2859425


Full-time Harrison School District 2 employees can qualify for CHFA Schools To Home, a Colorado down payment assistance program that pairs a 30-year fixed first mortgage with a deferred second mortgage worth up to 25% of that first mortgage amount. For eligible staff eyeing lower-priced homes in southeast Colorado Springs, that assistance can cover a meaningful share of the purchase price.
CHFA Schools To Home is a statewide Colorado program from the Colorado Housing and Finance Authority for eligible full-time public school employees. It pairs a 30-year fixed-rate first mortgage with an optional deferred second mortgage of up to 25% of the first mortgage amount, at zero percent interest with no monthly payment while it remains outstanding. The assistance can go toward down payment, closing costs, prepaid expenses, or principal reduction.
It is not free money. The second mortgage is a real loan with a real repayment obligation: you owe the original assistance back, plus a share of your home's appreciation, when a repayment event occurs. Weigh that trade-off against your own numbers before you commit.
Eligibility runs on employment classification, not job title. At least one borrower on the loan must be classified full time by an eligible Colorado preK-12 public school employer, including classroom staff, paraprofessionals, counselors and nurses, front-office and registrar staff, custodial and maintenance staff, nutrition services staff, bus drivers and mechanics, coaches, and administrative staff. Verify your employer through the Colorado Department of Education's SchoolView database, checking for "Public" in the School Type column for Harrison School District 2. Only one borrower needs to meet the employment requirement; a spouse or co-borrower can work in any field.
You do not have to be a first-time buyer, and you do not have to buy inside the Harrison D2 boundary. Eligibility comes from your employer, not your address, so a Harrison D2 employee can purchase anywhere in Colorado that meets the program's owner-occupancy and mortgage requirements.
The 25% figure applies to the first mortgage amount, not the purchase price. On a $350,000 home with a $280,000 first mortgage at 80% loan-to-value, the maximum second mortgage runs 25% of $280,000, or $70,000, covering the entire down payment with no mortgage insurance. A higher first-mortgage structure raises the available assistance, up to 97% LTV and 105% combined LTV, and requires mortgage insurance above 80% LTV. A CHFA participating lender can price both structures side by side before you decide.
The $1,000 figure people hear about is the minimum required borrower contribution, — gift funds are allowed — not the total assistance amount. Your actual cash needed at closing runs higher once closing costs, prepaids, and lender fees are added, so ask for a full cash-to-close estimate before writing an offer.
| At closing | Seven years later, sold for $450,000 | |
|---|---|---|
| Purchase price | $350,000 | — |
| First mortgage | $280,000 | — |
| Schools To Home assistance | $70,000 | Repaid at sale |
| Shared appreciation (illustrative 20%) | — | $20,000 owed on $100,000 gain |
| Total CHFA repayment | — | $90,000 |
This is an illustration only, not a projection of future values. Have a lender run the real numbers for your purchase price and timeline.
CHFA calculates a shared-appreciation percentage at closing, based on the assistance amount divided by the purchase price; in the example above, $70,000 of assistance on a $350,000 purchase sets a 20% shared-appreciation rate. When you sell, refinance, pay off the first mortgage, or stop using the home as your primary residence, that percentage applies to the difference between your sale price and your original purchase price. Negative appreciation counts as zero: you repay the original assistance, but never a share of a loss.
The income limit is $178,920 statewide, the same figure in every Colorado county regardless of household size, based on the qualifying income your lender uses for mortgage credit. The minimum mid credit score is 620, subject to the specific loan program's underwriting requirements.
Single-family homes, PUDs, condominiums, modular homes, and manufactured homes on a permanent foundation can all qualify, subject to Fannie Mae guidelines. A typical duplex does not qualify, since the program covers one-unit, owner-occupied properties. No Property Inspection Waiver is permitted; every purchase requires a full appraisal, which matters for offer strategy in a competitive southeast Colorado Springs market.
Schools To Home covers your down payment structure, but you still need a lender to originate and service the first mortgage. Mike Oswald at Rate (NMLS 261003, Equal Housing Lender) works with Colorado school-district buyers on CHFA financing, and you are free to use any lender who participates in the program. Start with the Kenna Real Estate Group's Kenna Credit Care mortgage readiness program if you want your credit and documentation squared away before you apply.
The Kenna Real Estate Group tracks active listings, price reductions, and pending sales through REcolorado for southeast Colorado Springs, so Harrison D2 employees can shop with current local data instead of a stale average. Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree. Ready to see what qualifies? Search every home for sale in Colorado.
Questions about any home in Colorado? Call or text 303-955-4220. A live person answers.
No. It's a deferred second mortgage with a shared-appreciation obligation, not a grant. You repay the assistance plus a share of your home's appreciation when a repayment event occurs.
Yes. The program covers any individual employed full time by an eligible public school employer, regardless of job title.
Up to 25% of your first mortgage amount, subject to CHFA guidelines, loan limits, and underwriting. On a $280,000 first mortgage, that's up to $70,000.
No. Eligibility comes from your employer, not your address. You can buy anywhere in Colorado that meets the program's owner-occupancy and mortgage requirements.
$178,920 statewide, the same figure in every Colorado county regardless of household size.
A minimum mid credit score of 620, subject to the specific loan program's underwriting requirements.
Not while the assistance is outstanding. Converting the property to a rental while assistance remains outstanding can trigger repayment.
Negative appreciation counts as zero. You still repay the original assistance amount, but never a share of a loss.