$1,325,000
Active
9
Beds
5
Baths
4376
Sqft
20.2
Acres
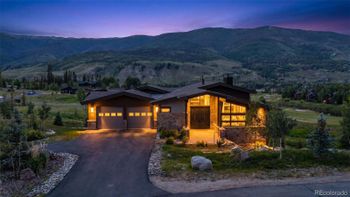
45 County Road 8751, Granby, CO 80446
MLS#: REC5167816
Kenna Real Estate Group · Cash buyers in Colorado
Delayed financing lets a cash buyer in Colorado take a mortgage within six months of closing and pull up to 80 percent of the price back out. You win the house with a cash offer and keep the cash liquid. Here are the rules, the numbers and the clock.
A live person answers. Not a robot, not a phone tree.
The refinance closes within 180 days of the day you bought with cash. Day 181 is a normal cash-out refinance with its own waiting rules.
Of the home's value on a primary residence, 75 percent on a second home or rental, and never more than the price you paid plus the refinance costs.
No mortgage, no seller financing, nothing recorded against the home. Money borrowed against other assets is allowed and gets paid off at the refinance.
Bank or brokerage statements, the purchase closing statement, and a clean title search.
About a quarter point above a purchase mortgage. That is the cost of having won the house.
Anyone sitting on sale proceeds or savings who wants the house now and the money back by spring.
Delayed financing is a Fannie Mae and Freddie Mac rule, so every conventional lender in Colorado offers it. Our lender partner starts the refinance file the week you go under contract, orders the appraisal the day after closing, and funds in 45 to 60 days.
Primary residence: you wire $700,000 at the purchase, and 60 days later $560,000 wires back, leaving $140,000 of equity in the house and a $560,000 mortgage. Second home or rental: $525,000 comes back. The loan amount cannot exceed what you paid plus the closing costs on the new loan, so a home that appraises above your price still returns the same dollars; the higher appraisal only makes the ratio test easier.
Read that chart honestly. Keeping the cash in the house earns nothing and costs you the interest the money would have made elsewhere; pulling it out costs the mortgage interest minus what the cash earns. At today's rates the mortgage costs about $9,800 a year more than leaving the money in on this home, and what you buy with that $9,800 is $560,000 liquid: the next purchase, the business, the market, or simply not being house-rich and cash-poor at 68. The full comparison, including the tax side, is on pay cash or finance in Colorado.
How the offer is written, down to the earnest money and the inspection window, is on making an offer on a Colorado home; the proof-of-funds and wire mechanics are on buying a home with cash in Colorado.
Buy the patio home with cash from the sale, then take 60 percent back out for income and travel. The homes are on Colorado ranch and patio homes and 55+ communities; the equity math on home equity.
Relocation cash wins the Colorado house in a week; the mortgage goes on after the move. Start on relocating to Colorado.
Cash at the sale, mortgage within six months, cash back for the next one. Rental property checklist.
The refinance qualifies on your savings divided over the loan term. Using retirement funds for a home.
Above $1 million the share of cash buyers doubles and the sellers expect it. These searches carry the live listings:
A cash-out refinance taken within six months of buying a home with cash. Fannie Mae and Freddie Mac both allow it, the new loan pays you back up to the price you paid plus the closing costs of the new loan, and the money arrives as a wire at the refinance closing. Compare it with a plain mortgage on pay cash or finance in Colorado.
Up to 80 percent of the home's value on a primary residence and 75 percent on a second home or a rental, and never more than what you paid plus the refinance closing costs. On a $700,000 primary residence that is $560,000 back. Run the payment on the mortgage calculator.
Yes. No mortgage, no seller carry, no loan secured by the home itself at the purchase. Money borrowed against something else, a brokerage line or a HELOC on your current home, is allowed and gets paid off from the refinance. The cash side of the purchase is on buying a home with cash in Colorado.
Where the purchase money came from, with bank or brokerage statements, the closing statement from the purchase showing no financing, and a title search showing no liens. Sale proceeds from your last home count; the equity math is on home equity.
Yes, by about a quarter point, because every lender prices delayed financing as a cash-out refinance. On $560,000 that is about $90 a month, the price of winning the house with cash. Rate timing is on refinancing a Colorado home.
The loan-to-value ratio uses the appraised value, so a $700,000 purchase that appraises at $750,000 passes the 80 percent test with room to spare, but the loan amount itself still caps at your price plus closing costs. Six months after the refinance, a normal cash-out refinance can use the full appraised value.
Because a cash offer wins. No financing contingency, no appraisal contingency, a 10-day close, and sellers take it over a financed offer at the same price. In a multiple-offer week that is the difference between the house and the next one. How the offer is written is on making an offer on a Colorado home.
Yes, at 75 percent of value. Investors use it to buy with cash at auction or from a seller who needs a fast close, then put the mortgage on within six months and move to the next one. The checklist is on the rental property checklist; the house-hacking version is on house hacking.
No. An asset-based (asset depletion) loan qualifies you on your savings instead of a paycheck: the lender divides your liquid assets over the loan term and treats the result as monthly income. It is the loan for a retiree or a business owner with a thin tax return, and it works at purchase, not only after. Our lender partner writes both; start on pre-approval with our lender partner.
You wait for the standard cash-out seasoning and refinance later on the appraised value, or open a home equity line on the new home. Neither is a disaster; both cost more time. The paths after six months are on refinancing and investing with a 401(k) or loan.
Text CASH and the price range to 303-955-4220. A live person answers, writes the cash offer the same day, and lines up the delayed-financing refinance before you close so the money comes back in 60 days.