New - 1 Day Ago
$619,900
Active
4
Beds
4
Baths
3242
Sqft
0.2184
Acres
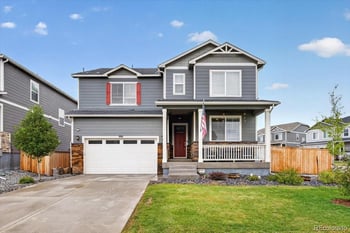
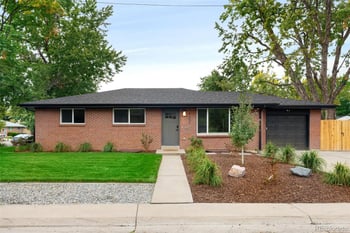
967 Spectrum Loop, Colorado Springs, CO 80921
MLS#: 2761458
Kenna Real Estate Group · Move-up buyers in Colorado
A bridge loan in Colorado turns the equity in your current home into the down payment on the next one, so you buy first, move once, and sell an empty, staged house. Here is what it costs, how much you can borrow, and the two paths that cost less.
A live person answers. Not a robot, not a phone tree.
A $650,000 home with $280,000 owed supports about $240,000.
Six months on $240,000: about $16,800. Paid off the day the old home closes.
One extension for a fee. The sale pays it off; nothing amortizes.
About 8.5 percent, no points, same job. Open it first; lenders decline a line on a listed home.
Zero interest, zero points. They cost you negotiating power or a tighter move.
The lender drops the old payment from your ratio once the contingencies clear.
Bridge loans in Colorado come from local banks, credit unions and portfolio lenders, not from the big national servicers, and every one of them wants the old home priced to sell inside the term. Our lender partner runs the bridge, the equity line and the new mortgage as one file so the three closings line up.
Every lender stops at 80 percent of the current home's value across all loans on it. Subtract what you owe and the rest is the down payment on the next home. The value is the number that matters, and it comes from the last 90 days of sales within a mile, not the county assessor and not a portal estimate; the Smart Pricing Report on home valuation pins it, and the equity math by itself is on home equity.
Approved in two weeks, funds at the new home's closing, interest-only until the sale. Fits a buyer who found the house this week and has not listed yet.
Opened 30 days before listing, drawn at the new closing, paid off at the old one. Fits anyone with 60 days of lead time.
The purchase closes only if your home sells. Works on homes that have sat 30 days or more; loses on fresh listings with competition.
Close the sale, rent your own home back for 30 to 60 days, buy with cash in hand. Fits a buyer who wants the strongest offer and tolerates a tighter move.
Close the bigger home on your schedule and move once. The 4-bedroom searches: Aurora, Colorado Springs, Arvada.
The home with the suite rarely waits for a sale contingency. Colorado next-gen homes and in-law suite homes.
Buy the one-level home first, move once, and let the big house show empty. Colorado ranch and patio homes and 55+ communities.
Two markets, one timeline. Relocating along the Front Range.
A short loan, six to twelve months, secured by the home you already own, that turns your equity into the down payment on the next home before the old one sells. It is interest-only, it costs 9 to 11 percent plus 1 to 3 points, and it is paid off from the sale. The equity side of the math is on home equity.
Up to 80 percent of your current home's value minus the mortgage on it. A $650,000 home with a $280,000 balance supports about $240,000. Your value is on home valuation; the Smart Pricing Report pins it to the dollar.
Yes, until the old home is under contract with the contingencies cleared; at that point the lender drops its payment from the ratio. That is why most Colorado move-up buyers list first, go under contract, then buy with a 45-day close. The full ratio run is on mortgage pre-approval.
Yes, by about $6,600 on a $240,000 gap over six months, and it has no points. The catch: open it before you list. Lenders decline a new equity line on a home that is listed for sale. The line pays off at your closing like any lien.
Yes, and on a home that has sat 30 days or more it works. On a fresh listing with other offers, a sale contingency loses to a clean offer at the same price. We write contingent offers with a kick-out clause and a 48-hour response so the seller keeps marketing; how it is structured is on making an offer on a Colorado home.
You sell first and rent your own home back from the buyer for 30 to 60 days while you close on the next one. Conventional lenders cap the buyer's rent-back at 60 days. It costs you rent at the buyer's mortgage payment and nothing in interest or points.
Sell when the move makes sense, because the home you are buying moves with the same market. A rate drop raises the price of the next home too. The city-by-city read on days on market and inventory is on why a Colorado house is not selling and selling a home in Colorado.
Today's value minus every loan on it. The value comes from the last 90 days of sales within a mile, not the tax notice and not a portal estimate. City pages: Parker, Castle Rock, Highlands Ranch, Littleton, Centennial, Aurora, Lakewood, Fort Collins, Colorado Springs.
Yes, and the timeline is the reason to: close the bigger home, move in on your own schedule, then list the old home empty and staged, which sells faster and for more. The bigger-home paths are on buying a bigger home in Colorado; the multigenerational homes on Colorado multigenerational homes.
You extend once, for a fee, or you cut the price. A home priced from the Smart Pricing Report sells inside the bridge term; a home priced from hope does not. If it still has not moved, a cash offer on it closes in 10 days: Denver cash home buyers.
Text EQUITY and your address to 303-955-4220. A live person answers, sends the Smart Pricing Report on your current home within one business day, and lines up the equity line or bridge with our lender partner so the offer on the next home is not contingent.