
The grid below lists every match live from the MLS, and the market stats under it show today's median price and price per square foot. Call or text 303-955-4220. A live person answers.

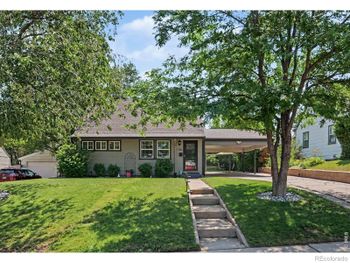


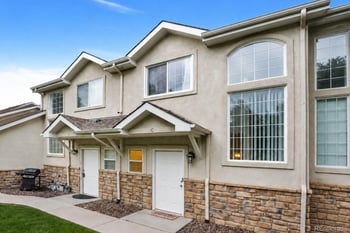


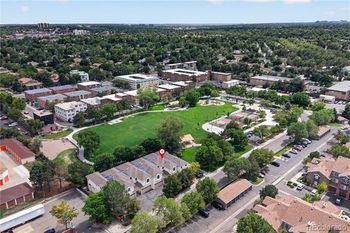


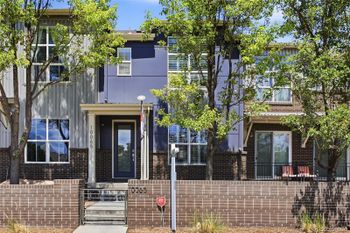



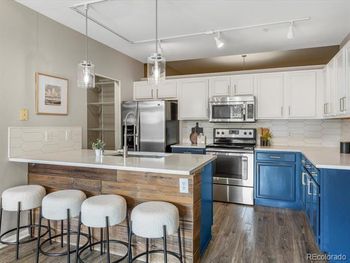

Denver FHA loan assumption homes for sale let buyers step into an existing mortgage, in many cases with lower interest rates and reduced upfront costs . These opportunities show up across the city, from Congress Park bungalows shaded by mature trees to newer homes in Green Valley Ranch . The trade-off is paperwork and approval steps, but the payoff is long-term affordability in one of Colorado’s most competitive housing markets. Scroll below to see the latest FHA assumable listings in Denver and decide if this path fits your next move.
For many buyers, an FHA loan assumption in Denver offers more than a home—it offers financial breathing room. By taking over a seller’s FHA mortgage, you can gain access to:
An FHA loan assumption means a buyer legally takes over the seller’s FHA-insured mortgage. Instead of applying for a brand-new loan, you step into the existing financing. To qualify, you’ll need:
Funds to cover any difference between the loan balance and the home’s purchase price—in many cases handled through a second loan or cash at closing.
Advantages include lower payments if the original rate is below current levels, while disadvantages can include stricter lender oversight and the need for additional cash if equity has grown.
Not every listing highlights assumable mortgages up front, so working with a knowledgeable Denver real estate agent is key. Agents can:
Final steps mirror a traditional closing. You’ll review loan documents, pay associated fees, and settle any equity difference owed to the seller. Expect costs to include:
Assumable FHA loans open doors for buyers navigating Denver’s competitive real estate market. With the potential for lower rates, smaller upfront costs, and access to established financing, they offer a smart alternative to starting from scratch. If you’re exploring FHA loan assumption homes for sale in Denver, connect with a trusted real estate agent or FHA-approved lender to see if this strategy fits your path to homeownership.
The grid at the top of this page is the live MLS list: it updates the moment a home lists or closes, and the market stats under it show today's median price. More: Financing a Colorado home.
The market stats under the grid show today's median list price and price per square foot, and they update with every new listing. More: Financing a Colorado home.
The price per square foot against the other listings on this page (the market stats under the grid show today's median), the days on market, the HOA or metro district if there is one, the sewer line and roof age on older homes, and whether the seller pays a closing-cost credit or a rate buydown. More: Financing a Colorado home.
It changes as homes list and sell. Switch the grid to map view to see where today's listings cluster, or open the ZIP code pages linked on this page for each ZIP's live count. More: Financing a Colorado home.
It depends on the price, your down payment and today's rate. Put the price of the home you like into the Colorado mortgage calculator at kennarealestate.com/colorado-mortgage-calculator for the full monthly cost. More: Financing a Colorado home.
Sizes vary from home to home. Use the grid filters for square footage and bedrooms; the market stats under the grid show today's price per square foot. More: Financing a Colorado home.
Not all FHA loans are assumable, but most originated after 1989 allow it with lender approval. Always confirm with the servicing lender before making an offer. More: Financing a Colorado home.
FHA loans are more flexible than conventional financing. In Denver, lenders in most cases look for mid-600 credit scores, but each case is reviewed individually. More: Financing a Colorado home.
Work with a Denver real estate agent familiar with assumable mortgages. Agents can screen MLS listings, confirm loan types with sellers, and connect you with FHA-approved lenders. More: Financing a Colorado home.
Closing costs in Denver FHA loan assumptions include origination fees, appraisal, inspection, title insurance, and county recording fees. These are in most cases lower than starting a new loan but vary by lender.
Yes. Programs like Denver’s Metro Down Payment Assistance Program or statewide CHFA assistance can be available in tandem with an FHA assumption, depending on lender participation. More: Financing a Colorado home.
Text DENVER and what you are looking for to 303-955-4220. A live person answers, sets up the saved search and sends the disclosures on any FHA loan assumption homes you want to see.