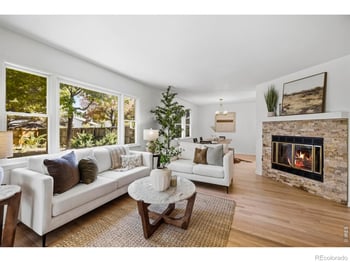
New - Just Now

$415,000
Active
2
Beds
2
Baths
2054
Sqft
0.11
Acres
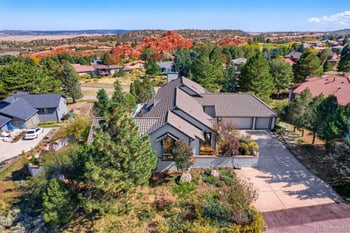
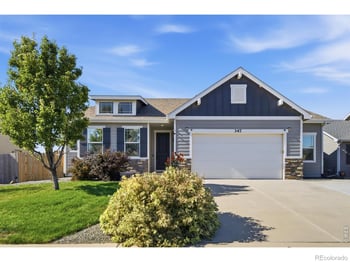
3607 Kirkwood Ln, Johnstown, CO 80534
MLS#: RECIR1070268
Kenna Real Estate Group · Colorado buyers
63% of Denver-area sales now include a seller concession. Here is what you can ask for, the loan limits, how a 2-1 buydown works, and the exact words to put in your offer.
A live person answers. Not a robot, not a phone tree.
Take the credit unless you will keep this exact loan, without refinancing, for well over a decade. On a $480,000 loan at 7 percent, a $10,000 seller credit used as a 2-1 buydown cuts the payment $616 a month in year one and $315 a month in year two, about $11,200 back in the first two years. The same $10,000 off the price saves $66 a month, $792 a year, and needs about 14 years to catch up to the buydown. Plan to refinance, sell or move inside that window, take the credit; plan to hold the loan longer, take the price, or ask for both. Sellers in Colorado are giving credits on 63 percent of sales, so the ask is normal, and homes past 30 days on market with a price cut are the ones that say yes.
Denver sales with a concession
63%
Average about $10,000 per sale.
2-1 buydown, year one
$616
On a $480,000 loan at a 7% note rate.
Same $10,000 as a price cut
$66
Over 30 years. The buydown wins on payment.
Best candidates
30+ days
Ask in the offer, then again after inspection.
| Loan | Down payment | Max seller contribution |
|---|---|---|
| Conventional | Under 10% | 3% of price |
| Conventional | 10% to 25% | 6% of price |
| Conventional | Over 25% | 9% of price |
| FHA | 3.5% and up | 6% of price |
| VA | 0% | Concessions (buydowns, prepaids, paying off buyer debts) up to 4% of the home’s reasonable value; ordinary closing costs the seller pays are counted separately and are not capped by the 4% |
| USDA | 0% | 6% of price |
The credit cannot exceed your actual closing costs, prepaids and buydown cost. On a $600,000 home with 5% down conventional, the cap is $18,000. Read what closing costs are in Colorado and FHA and VA buying.
The seller deposits the buydown cost with the lender at closing. In year one you pay as if your rate were 2 points lower. In year two, 1 point lower. In year three the full note rate applies. You qualify at the full rate, so the buydown is pure savings, and if rates fall you refinance and the unused deposit comes back to you as a principal reduction.
Use plain words the listing agent can read in five seconds: "Seller to credit Buyer $10,000 at closing toward Buyer's closing costs, prepaids and/or rate buydown." Keep the price at or near list if the home is fresh. Ask for a bigger credit instead of a lower price when the home has sat, because the seller's net is the same and your payment is better. After inspection, ask for a credit, not repairs: it closes faster and you pick the contractor.
Builders sit on a 15-year inventory peak and are paying $10,000 to $25,000 in closing costs and buying rates down on quick move-in homes, through their own lender in most cases. See which builders are offering what and new construction homes for sale.
Sometimes a slightly higher price, if the seller adds the credit to the price to protect their net. Check that the home still appraises at the higher number. A live person runs both versions of the deal with you in five minutes: 303-955-4220.
kennarealestate.com · free guide
What to ask for by loan type, the 2-1 buydown math on your price, the offer wording, and the inspection credit script
Ask for a credit, not a lower price. A 2-1 buydown on a $480,000 loan costs about $11,200 and saves $616 a month in year one and $315 in year two; the same money off the price saves about $70 a month for 30 years. Which one wins depends on how long you keep the loan, and the section below runs both. Sixty-three percent of Denver-area sales include a concession.
Prepared by
KENNA REAL ESTATE GROUP
Call or text 303-955-4220 · A live person answers.
Text the address to 303-955-4220. A live person tells you what to ask for and what the payment looks like with it.
Call or text 303-955-4220Get pre-approvedMoney the seller contributes at closing toward costs that are normally yours: closing costs, prepaid taxes and insurance, repairs, or a mortgage rate buydown. Right now about 63% of Denver-area sales include one, averaging about $10,000.
Conventional loans allow 3% of the price with under 10% down, 6% with 10% to 25% down. FHA allows 6%. VA caps concessions at 4% of the reasonable value and counts ordinary closing costs separately. The concession cannot exceed your actual costs.
The seller or builder pays a lump sum at closing so your rate is 2 points lower in year one and 1 point lower in year two, then returns to the note rate. On a $480,000 loan at 7% that is $616 a month saved in year one and $315 in year two.
For the monthly payment, yes. A $10,000 price cut lowers a 7% payment about $66 a month for 30 years. The same $10,000 as a 2-1 buydown saves $616 a month in year one and $315 in year two, and you can refinance if rates fall.
Yes, and builders are the most generous sellers in Colorado right now: closing cost credits of $10,000 to $25,000 and rate buydowns on quick move-in homes, tied to the builder's lender.
In the offer, and again after inspection. Homes past 30 days on market with a price cut are the best candidates. Ask for a credit instead of repairs; it closes faster.
No. Seller credits pay closing costs, prepaids and rate buydowns; lenders do not let them fund the down payment. Down-payment help comes from CHFA, metroDPA, a gift, or your own savings, and it stacks with a seller credit.
They are lost. If the credit is bigger than your closing costs, prepaids and buydown put together, the leftover goes back to the seller at closing. Size the ask to the Loan Estimate, or direct the extra into permanent points.
Yes. CHFA and metroDPA cover part of the down payment; the seller credit covers closing costs and the buydown. Together they can bring the buyer’s own cash on a $480,000 purchase under $10,000. Tell the lender both are in play before the offer is written.
Then the 2-1 buydown is two years of relief and the year-three payment is your payment for the life of the loan. If you plan to hold the loan for decades without refinancing, ask for permanent points or a price cut instead, and buy the home only if the year-three payment fits.
Today's Colorado mortgage rates
A seller credit buys down a rate, and the rate changes weekly: see today's Colorado mortgage rates before you write the offer.