New - 2 Days Ago

Looking for assumable mortgage homes in Colorado? The grid below lists every match live from the MLS, and the market stats under it show today's median price and price per square foot. The grid below lists every match live from the MLS, and the market stats under it show today's median price and price per square foot. Call or text 303-955-4220. A live person answers.
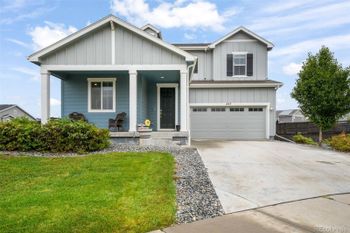
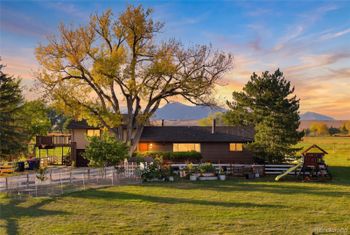

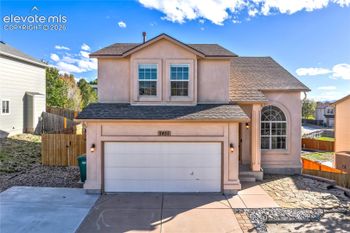

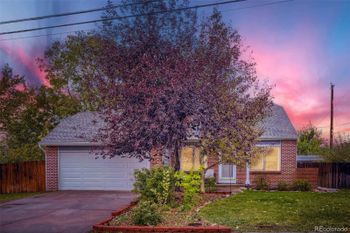






Every listing on this page says the seller's loan can be assumed. On an FHA or VA loan from 2020 to 2022 that means a rate in the 2s or 3s instead of today's rate. The catch: you pay the seller's equity in cash or with a second loan, you qualify with the servicer, and the servicer takes 45 to 120 days. VA loans can be assumed by non-veterans, but the seller's entitlement stays tied up unless the buyer is also VA-eligible.
Of the 418 Colorado listings whose remarks say the loan can be assumed, 156 name a VA loan and 64 an FHA loan; the rest do not say which. The assumable rate is the whole reason to look: on the median $519K assumable listing with 20 percent down, a 3 percent assumed loan costs $1,750 a month in principal and interest against $2,762 at 7 percent, $1,012 a month less for the life of the loan.
The buyer does not need to be a veteran, but the seller's VA entitlement stays tied to the loan unless a veteran buyer substitutes theirs. VA charges a 0.5 percent funding fee on assumption. Colorado VA assumable homes for sale.
FHA loans written after 1989 assume with a full qualification by the servicer; investors are out on most. The FHA mortgage insurance stays with the loan. Colorado FHA assumable homes for sale and Denver FHA loan assumption homes.
You take over the balance; the difference between the price and that balance is paid in cash or with a second mortgage. On a home bought in 2021 with a 3 percent loan the gap is most of the appreciation since.
Assumptions close on the servicer's timeline, not the contract's. Write the contract with that in mind and keep a conventional pre-approval as the backup. The Colorado assumable mortgage guide walks the steps.
| City | Assumable listings | VA eligible homes for sale |
|---|---|---|
| Colorado Springs | 100 | Colorado Springs VA eligible homes for sale |
| Denver | 37 | Denver VA eligible homes for sale |
| Aurora | 33 | Aurora VA eligible homes for sale |
| Peyton | 19 | Peyton VA eligible homes for sale |
| Commerce City | 17 | Commerce City VA eligible homes for sale |
| Littleton | 16 | Littleton VA eligible homes for sale |
| Castle Rock | 14 | Castle Rock VA eligible homes for sale |
| Parker | 13 | Parker VA eligible homes for sale |
| Thornton | 12 | Thornton VA eligible homes for sale |
| Fountain | 11 | Fountain VA eligible homes for sale |
| Brighton | 8 | Brighton VA eligible homes for sale |
| Johnstown | 8 | Johnstown VA eligible homes for sale |
| Monument | 8 | Monument VA eligible homes for sale |
| Arvada | 7 | Arvada VA eligible homes for sale |
| Pueblo | 6 | Pueblo VA eligible homes for sale |
The grid at the top of this page is the live MLS list: it updates the moment a home lists or closes, and the market stats under it show today's median price. More: Financing a Colorado home.
The market stats under the grid show today's median list price and price per square foot, and they update with every new listing. More: Financing a Colorado home.
It depends on the price, your down payment and today's rate. Put the price of the home you like into the Colorado mortgage calculator at kennarealestate.com/colorado-mortgage-calculator for the full monthly cost. More: Financing a Colorado home.
Some do. Each listing card shows the HOA fee, and the grid filters can narrow the list to homes with no HOA. More: Financing a Colorado home.
It changes as homes list and sell. Switch the grid to map view to see where today's listings cluster, or open the ZIP code pages linked on this page for each ZIP's live count. More: Financing a Colorado home.
Yes. Colorado down-payment assistance works at a 620 credit score, FHA takes 3.5 percent down, VA zero where the buyer qualifies, and a seller credit covers closing costs. On the median $518K assumable mortgage homes that is $18,130 down at 3.5 percent. More: Financing a Colorado home.
Yes, if the servicer approves you. A non-veteran buyer can assume a VA loan, but the seller's VA entitlement stays with the loan until it is paid off, which many sellers refuse. More: Financing a Colorado home.
You need the equity gap. If the home is $500,000 and the loan balance is $380,000, you need $120,000 in cash or a second loan. More: Can I afford a home now?.
Text COLORADO and what you are looking for to 303-955-4220. A live person answers, sets up the saved search and sends the disclosures on any assumable mortgage homes you want to see.