New - 3 Hours Ago

Kenna Real Estate Group · Colorado buyers
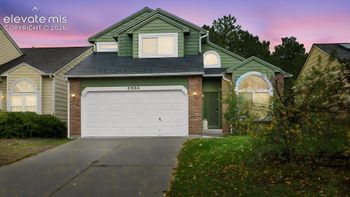
Take one real $600,000 home in Parker and see the full monthly payment at 5.5%, 6%, 6.5%, 7% and 7.5%. Then see the four ways buyers are cutting that payment right now.
A live person answers. Not a robot, not a phone tree.
At 7%, a $600,000 Colorado home with 20% down costs about $3,800 a month all in (PITI: principal, interest, taxes and insurance). With 3.5% down on an FHA loan the same home is about $4,725 a month, because the loan is bigger and mortgage insurance is added. Half a point on the rate moves that payment about $155 a month. The bigger levers are the down payment, the seller, the builder and the loan type, and all four are in play in this market. Below is a real home, priced line by line, so you can see it.
PITI means principal, interest, property taxes and homeowners insurance. Taxes and insurance differ by parcel and carrier, so your number moves by a few dollars to a couple hundred a month from the example; the lender's Loan Estimate is the exact figure. To get the rate itself down, read seller concessions and 2-1 buydowns and builder rate buydowns, or get the buyer concession playbook.
The example home
$600,000
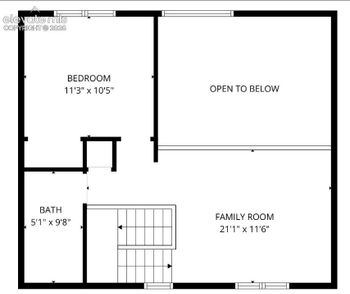
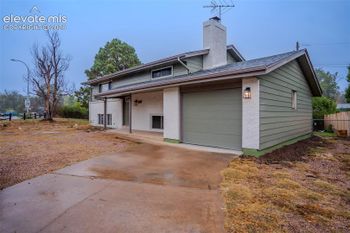
4 bed, 4 bath, 1,982 sq ft, no HOA, 70 days on the market. See the listing.
Payment at 7%
$3,801
$3,193 principal and interest + $261 taxes + $347 insurance.
Per half point
$155
That is the whole difference between 6.5% and 7% on this home.
What sellers give
63%
include a seller concession, averaging about $10,000. That buys the rate down.
The table is principal and interest on a 30-year fixed loan. Taxes and insurance are added below it. Look across a row: the jump from 5.5% to 7.5% is real, but each half point is smaller than most buyers think.
| Rate | 5.5% | 6.0% | 6.5% | 7.0% | 7.5% |
|---|---|---|---|---|---|
| 20% down ($480,000 loan) | $2,725 | $2,878 | $3,034 | $3,193 | $3,356 |
| 5% down ($570,000 loan) | $3,236 | $3,417 | $3,603 | $3,792 | $3,986 |
| 3.5% down FHA ($579,000 loan) | $3,287 | $3,471 | $3,660 | $3,852 | $4,048 |
| Line | 20% down | 5% down | 3.5% FHA |
|---|---|---|---|
| Principal and interest | $3,193 | $3,792 | $3,852 |
| Property tax ($3,130 a year on this home) | $261 | $261 | $261 |
| Homeowners insurance (Colorado average $4,164 a year) | $347 | $347 | $347 |
| Mortgage insurance | $0 | about $238 | about $265 |
| HOA | $0 | $0 | $0 |
| Total per month | $3,801 | $4,638 | $4,725 |
Run your own numbers on the Kenna mortgage calculator, or call 303-955-4220 and a live person runs them with you in five minutes.
About $135,000 to $150,000 a year with 20% down, and about $165,000 with 5% down. Lenders cap total debt at roughly 43% to 45% of gross income. A $3,800 payment plus a $500 car payment and $200 in other minimums is $4,500 of debt, which needs about $10,500 a month, or $126,000 a year, before student loans. Every $100 a month of other debt costs you about $17,000 of house.
63% of Denver-area sales this year include a seller concession, averaging about $10,000. Used as a 2-1 buydown, that money cuts your rate 2 points in year one and 1 point in year two. On the 20% down example that is a payment near $2,590 in year one instead of $3,190. Read how to ask for a concession or buydown.
Builders sit on a 15-year inventory peak and are paying closing costs and buying down rates on quick move-in homes. The builder rate sits well below the market rate on most quick move-in homes. See which builders are offering incentives and new construction homes for sale.
CHFA offers up to $25,000 in down payment help, and buyers in Adams, Arapahoe, Denver, Douglas and Jefferson counties can stack another $15,000 through NeighborhoodLIFT. Income limits apply, and a home buyer class is required. Start with the first-time buyer guide and FHA and VA buying.
FHA and VA loans written in 2020 and 2021 carry rates in the 2s and 3s, and they transfer to the next buyer. You cover the seller's equity in cash or with a second loan. Search assumable mortgage homes for sale in Colorado and read how an assumption works.
Waiting costs more than most buyers expect. When rates fall, buyers who stepped back step in again, and the concessions, price cuts and builder incentives that exist today shrink. Right now 57% of Denver listings carry a price cut and homes sit 53 days. That is leverage you have today. You can refinance a rate. You cannot refinance a purchase price.
Renting costs less per month than buying in every large metro this year, Denver included. Buying wins when you stay five years or more, because the payment on a fixed loan does not rise and rents do. If your horizon is under three years, rent and keep saving. If it is five years or more, the numbers on this page are the ones that matter.
kennarealestate.com · free guide
Price any home the way we price the Parker example: rate, down payment, taxes, insurance, HOA, metro district, mortgage insurance and the income you need
At 7 percent, a $600,000 Colorado home with 20 percent down costs about $3,800 a month all in. Half a point moves it $155. The bigger levers are the down payment, the seller, the builder and the loan type.
Prepared by
KENNA REAL ESTATE GROUP
Call or text 303-955-4220 · A live person answers.
The payment is half the picture; the cash to close is the other half. Closing costs for Colorado buyers lays out every line, who pays it, and how a seller credit cuts it.
Looking for the cheapest homes? Every Colorado home under $400,000, ranked by city with the HOA and the programs that cut your cash to about $1,000: affordable homes for sale in Colorado.
Text the address to 303-955-4220. A live person sends back the full monthly number, with taxes, insurance and any HOA or metro district, the same day.
Call or text 303-955-4220Get pre-approvedAbout $3,193 a month for principal and interest with 20% down, and about $3,801 with taxes and insurance on the Parker example home. With 5% down it is about $4,638 including mortgage insurance.
About $155 a month on a $480,000 loan. Going from 7% to 6.5% saves $159; going from 7.5% to 7% saves $163.
About $135,000 to $150,000 a year with 20% down and no other debt, and about $165,000 with 5% down. Car payments and student loans raise that quickly: every $100 a month of other debt removes about $17,000 of buying power.
Yes. A seller credit can fund a 2-1 buydown or permanent points. 63% of Denver-area sales this year include a seller concession averaging about $10,000.
Rates can be refinanced later; the purchase price cannot. Today 57% of Denver listings have cut their price and sellers are paying concessions. When rates fall, that leverage shrinks.
An assumable FHA or VA loan from 2020 or 2021, a builder buydown on a new home, or CHFA down payment assistance stacked with a seller concession. Each one is explained above with a link.
Half a point on your rate is $135 a month
On a $400,000 loan, the monthly payment is $2,648 at 6.95% and $2,783 at 7.45%. That is $135 a month for half a point of rate, or $34 for every $100,000 you borrow.
Today's Colorado mortgage rates
Your payment moves with the rate, so check this week's 30-year and 15-year numbers on current Colorado mortgage rates before you price a home.