New - Just Now

Looking for rent-to-own homes in Colorado, Colorado? 21,270 homes at $24K to $600K are the Colorado listings a lease-purchase or a $1,000-cash-to-close loan reaches this week, median $385K. ZIP 80908 has the most of them (28); the steps and the buy-now alternative follow the homes. Call or text 303-955-4220. A live person answers.


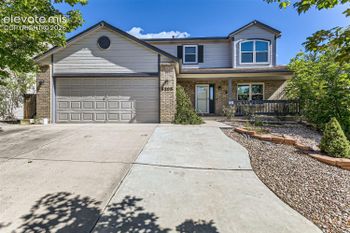


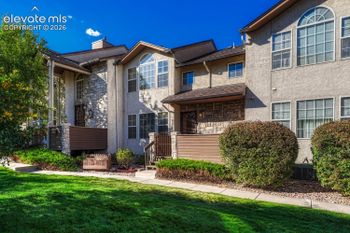


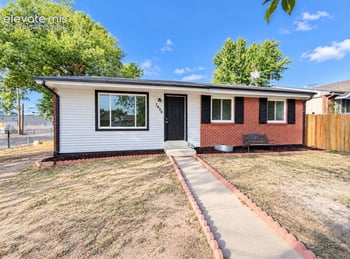
Rent-to-own in Colorado is real, and it is smaller than the search results suggest: the national programs have pulled back, so the homes that work are private lease-options with individual sellers, the sellers of homes that have sat, and the builders and lenders who make buying now possible for the same buyer. This page holds all of it: the live listings, the requirements, the costs, the contract rules, the city pages, and the buy-now alternative most rent-to-own shoppers qualify for.
The deal
1 to 3 years
Option fee of 1 to 5 percent up front, part of the rent credited to the purchase.
What sellers want
580 to 620
No eviction or bankruptcy in the last two years. Below 580, a 12-month repair plan first.
The alternative
3.5% down
Many rent-to-own shoppers can buy today. A live person runs both numbers.
The rule
Attorney + recorded
Colorado has no rent-to-own statute; the contract is the protection.
Most people searching for rent-to-own in Colorado can buy a home now. A 620 credit score qualifies for Colorado down-payment assistance, and a participating lender can run a program that brings the buyer’s cash to close to about $1,000: the down payment comes from the assistance, the closing costs come from the seller credit, and you keep the money a rent-to-own seller would have taken as an option fee. There is a second saving nobody mentions: the first mortgage payment is not due until the first of the month after the month you close, so a buyer who closes early in the month skips close to two months of rent on the way in.
Almost everyone searching rent to own in Colorado is a renter who wants to own and believes one thing is in the way: the down payment, the credit score, the debt, the new job or a past foreclosure. Each one has a fix that costs less than a lease-option. The three charts use a $450,000 home, the Front Range median for a 3-bedroom house, and a 30-year FHA loan.
Read the $1,000 cash-to-close path, then the objections below. Call or text 303-955-4220. A live person answers.
That is the number one reason renters search for rent-to-own, and it is the easiest one to solve. CHFA pays up to 3 percent of the loan as a grant that is never repaid, or up to 4 percent as a 0 percent second mortgage, and we ask the seller to pay your closing costs. Your own money: about $1,000 plus an earnest deposit you get back at closing. The program rules are on CHFA down payment assistance in Colorado, the worked example is on $1,000 cash to close, and every other path is on ways to buy.
FHA closes at 580 with 3.5 percent down and at 500 with 10 percent down. Between 580 and 620 you buy with FHA now and skip the assistance; under 580 you spend 60 days on credit care (paying cards under 30 percent of their limits and disputing errors moves most scores 20 to 40 points) and then apply. The loan rules are on FHA and VA home buying.
FHA approves debt-to-income ratios up to 50 percent with a 620 score and reserves, and it counts an income-based student loan payment as it is paid, with 0.5 percent of the balance used only when the payment is $0. Run the real ratio on mortgage pre-approval before you decide a lease-option is the only way.
A new salaried job in the same field closes with an offer letter and one pay stub. Self-employed buyers bring two years of tax returns, or one year with a two-year history in the same line of work. A lender who works with self-employed buyers can read the file in a day; start on mortgage pre-approval.
Waiting periods, not life sentences: FHA three years after a foreclosure or short sale, two years after a Chapter 7, one year of on-time Chapter 13 payments. The homes and the timeline are on after a foreclosure; a lease-option bridges the gap when the date is inside two years. After a divorce, the one-income path is on buying a house after divorce in Colorado.
Then rent-to-own fits: a two-year lease-option on a home you want, with the option to walk away, costs the option fee and nothing else. Buying and selling inside two years costs about 8 percent of the price in commissions and closing costs. The city lists are on Denver rent-to-own homes, Colorado Springs rent-to-own, Aurora rent-to-own homes and Greeley rent-to-own homes.
That is the ad for a scam, not a home. A real Colorado lease-option is drafted by a lawyer, recorded against the title, and signed with a seller who owns the home free of default. The warning signs are listed under red flags below, and the honest version of the deal is on Denver rent-to-own homes.
A lease-option does lock the price, and sellers price that lock above today's market. The cheaper lock is an assumable loan: take over a seller's 3 percent FHA or VA mortgage and own the home now. Listings are on assumable mortgage homes, VA assumable homes and FHA assumable homes.
| Line | Typical in Colorado | Refundable? | Credited to the price? |
|---|---|---|---|
| Option fee | 1% to 5% of the agreed price | No | Yes, at closing |
| Rent premium | $150 to $500 a month above market rent | No | Yes, as the rent credit |
| Rent credit | 10% to 30% of each payment | No | Yes, if you buy |
| Security deposit | One month | Yes, under Colorado landlord-tenant law | No |
| Maintenance | Routine repairs on you; major systems on the owner | n/a | No |
| Purchase price | Fixed the day you sign | n/a | n/a |
| Rent-to-own | Buy now with FHA + down-payment help | Keep renting | |
|---|---|---|---|
| Cash up front | 1% to 5% option fee | 3.5% down, part of it from CHFA or metroDPA | Deposit |
| Credit needed | 580 to 620 | 580 for FHA | Varies |
| Price locked? | Yes | Yes, you own it | No |
| Equity while you wait | Only the credits | All of it | None |
| Risk | Losing the fee if you cannot close | Normal ownership risk | Rent increases |
| Best for | Mortgage 12 to 24 months away | Score 580+, reserves in hand | Moving in under two years |
Compare the year-one payment with a seller credit toward the rate: seller concessions for buyers and can I afford a home now. First-time buyers: the Colorado first-time buyer guide and what closing costs are in Colorado. Buyers with a home to sell: who is buying at 7 percent.
Every city page below carries the live rent-to-own and lease-option listings, the requirements, the costs, and the questions buyers ask there.
Usually, yes. A 620 score and two years of steady income qualify for Colorado down-payment programs, and a participating lender’s $1,000 cash-to-close program pairs the assistance with a seller credit so the buyer’s own cash is about ,000. You own the home from day one instead of paying an option fee for the right to buy it later, and you skip close to two months of rent before the first mortgage payment.
You lease the home for one to three years under a written option to buy it at a price set today. You pay an option fee of 1 to 5 percent of the price up front, a monthly rent that is a little above market, and part of that rent is credited toward the purchase. At the end of the term you buy with a normal mortgage, using the credits and the option fee as part of the down payment, or you walk away and forfeit them.
The listings on this page are the Colorado homes whose sellers accept a lease-option, lease-purchase or seller-financing structure, pulled live from the MLS. Most rent-to-own deals in Colorado are private agreements with an individual seller, not a program, so the inventory changes weekly. Call or text 303-955-4220 and a live person checks the current list, including the homes not marked that way in the MLS.
Yes, that is what the structure is for. Most sellers want a score of 580 to 620, income of about three times the monthly rent, and no eviction or bankruptcy in the last two years. Below 580 the plan is a 12-month lease with a credit-repair schedule, then the option. An FHA loan needs 580 with 3.5 percent down, so many buyers who think they need rent-to-own can buy now.
No legitimate one. A seller who skips the credit check is either pricing the risk into a high option fee and rent, or running a scam. Expect a soft pull at the application and a full pull when you exercise the option and apply for the mortgage.
The option fee, 1 to 5 percent of the agreed price: $5,000 to $25,000 on a $500,000 home. It is non-refundable if you do not buy, and it is credited to the price if you do. Compare that with 3.5 percent down on an FHA purchase, which buys the home outright today.
A lease-option gives you the right, not the obligation, to buy; you can walk away and lose the fee and credits. A lease-purchase obligates you to buy at the end of the term, and the seller can sue for the difference if you cannot close. Sign a lease-option unless a Colorado real estate attorney has read the lease-purchase and told you why it is sound for you.
Yes. Colorado has no single rent-to-own statute; the deal runs under landlord-tenant law and real estate contract law, and the Colorado Real Estate Commission requires the purchase-option contract to be drafted by a licensed attorney rather than a broker. Colorado does not require the option to be recorded, so ask for a recorded memorandum of option to protect your position if the seller sells or refinances.
Whatever the contract says. Most Colorado lease-options put routine maintenance on the tenant-buyer and keep taxes, insurance and major systems with the owner until closing. Get a home inspection before you sign, the same as a purchase, and write the roof, furnace and sewer line into the agreement.
Not if the option is written correctly: the price is fixed the day you sign, and the option binds the seller for the term. Recording a memorandum of option puts the world on notice. An unrecorded option and a seller with a mortgage in default is how buyers lose their option fee.
No. The national lease-with-right-to-purchase programs stopped taking new applications, and the last one sold in 2025. Every rent-to-own deal in Colorado today is a private agreement with an individual seller, which is why the listings on this page come straight from the MLS and why the $1,000 cash-to-close path beats most of them.
With a lease-option you move out and forfeit the option fee and rent credits. With a lease-purchase you are in breach. That is why the plan starts with a lender: a pre-approval path with a date, so the option term matches the time it takes to fix the credit or save the difference.
Run both numbers. Colorado buyers with a 580 to 620 score and three months of reserves can buy today with FHA and a down-payment program such as CHFA or metroDPA, and a seller credit toward the rate. Rent-to-own only wins when the mortgage is 12 to 24 months away and the home is worth locking in at today's price.
Yes, as long as the HOA allows leasing and the owner holds clear title. Condos also need the building to be FHA-eligible if you plan to buy with FHA at the end; check the approval list before you pay an option fee.
Two months of pay stubs or a year of bank statements if self-employed, two years of W-2s or tax returns, a photo ID, the last two months of bank statements for the option fee, and your rental history. A seller who asks for a fee before showing you the home or the contract is a red flag.
Call or text 303-955-4220. A live person sends both within one business day: the sellers who will write a lease-option, and what you qualify for today.
Call or text 303-955-4220All Colorado rent-to-own homesLooking for the cheapest homes? Every Colorado home under $400,000, ranked by city with the HOA and the programs that cut your cash to about $1,000: affordable homes for sale in Colorado.