New - 1 Day Ago
Rent to own homes in Commerce City are private lease-option deals with individual sellers; we found no Commerce City rent-to-own program. On October 25, 2026, 1 of the 330 Commerce City homes for sale mentioned rent to own, a lease option or seller financing in the MLS remarks, and the grid below shows Commerce City homes for sale now. metroDPA, Colorado Roots and CHAC all list Commerce City.
Get rent-to-own and low-down-payment homes in Commerce City sent to you. Call or text 303-955-4220. A live person answers.
Send me the Commerce City listWhat it’s like to live in Commerce City: our Commerce City area guide.



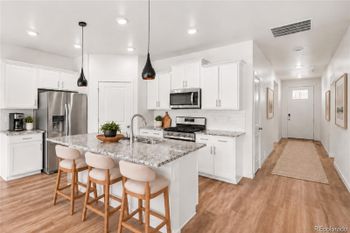
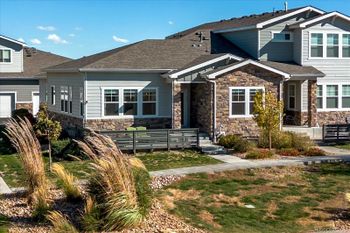
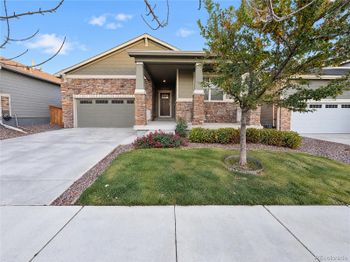


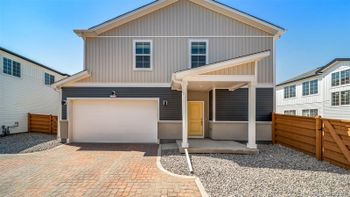

77.2% of Commerce City homes are owner-occupied, and the Census median value is $499,700. A Commerce City lease to own deal makes sense only when a mortgage is 12 to 24 months away. The Kenna Group at Keller Williams DTC asks every caller one thing first: what has you looking at rent-to-own instead of buying?
620+
You may not need rent-to-own. metroDPA, Colorado Roots, CHAC and CHFA. Next step: a pre-approval call with a lender of your choice.
580 to 619
Buy with your own down payment. 580 is the FHA minimum with 3.5% down, about $17,500 on a $500,000 Commerce City home. Most down payment assistance programs we work with start at a 620 credit score, so this path uses your own savings.
Under 580
Work on credit first. A lender call will not help yet. Pull your free reports at annualcreditreport.com and ask us about the Kenna Credit Care program; we call back when the score is ready.
| Rent to own (lease option) | Buy now with down payment assistance | |
|---|---|---|
| Cash up front | Option fee, often 1% to 5% ($5,000 to $25,000), lost if you do not buy | metroDPA covers 3% or 4% of the loan; Colorado Roots up to 10%; CHFA asks for at least $1,000 |
| Credit | Set by each seller; you still need a mortgage when the lease ends | 620 for most assistance; 580 with your own 3.5% FHA down payment |
| Who owns the home | The seller, until you close | You, at closing |
| Equity while you wait | Only the rent credits the contract allows | All of it, from day one |
| Which homes | Only homes whose sellers agree to a lease option | Any Commerce City home for sale: the whole grid above |
The $500,000 example matches the Census median Commerce City value ($499,700); today’s average list price is $553,000. The 2026 Adams County FHA and conforming limit is $862,500.
Renting versus owning in Commerce City: Census 2020-2024 figures show a median rent of $1,880 and a median owner cost with a mortgage of $2,553, a $673 gap.
Checking the seller: Commerce City is in Adams County: the Adams County property search and Adams recorded documents. Confirm who owns the home and whether a loan or lien is recorded before you pay any option fee.
330
Commerce City homes for sale, active or coming soon, October 25, 2026
62
of them listed at $400,000 or less
1
mention rent to own, a lease option or seller financing in the MLS remarks
62 of the 330 Commerce City listings are at $400,000 or less. Starter search: affordable homes for sale in Commerce City.
We found none. Commerce City buyers use metroDPA, Colorado Roots, CHAC and CHFA; rent-to-own there is a private lease option.
On October 25, 2026, 1 of the 330 Commerce City homes for sale mentioned rent to own, a lease option or seller financing in the MLS remarks.
Use the city’s interactive metro district map by address, then read the district’s mill levy before you sign a lease option.
metroDPA (3% or 4% of the loan), Colorado Roots (up to 10%, first-time or first-generation buyers), CHAC (6% up to $12,000) and CHFA.
At 1% to 5% of a $500,000 price, $5,000 to $25,000, lost if you do not buy.
Next steps: Commerce City homes for sale · CHFA down payment assistance · the $1,000 cash-to-close path · mortgage pre-approval · first-time buyer guide · Denver rent to own homes · Brighton rent to own homes · Thornton rent to own homes · all Colorado rent to own homes · our Commerce City area guide.
Call or text 303-955-4220. A live person answers.
Browse Available Homes
Search "rent to own homes Commerce City" and most of what comes back is a list-building site that wants a fee. The real Commerce City inventory is the grid above: homes whose sellers will write a lease-option, plus the ones we ask on your behalf once they have sat past 45 days. The grid below lists every match live from the MLS, and the market stats under it show today's median price and price per square foot. Below: the requirements, the costs, the Colorado contract rules, the red flags, the other Front Range cities, and the buy-now path.
The deal
1 to 3 years
Option fee of 1 to 5 percent up front, part of the rent credited to the purchase.
What sellers want
580 to 620
No eviction or bankruptcy in the last two years. Below 580, a 12-month repair plan first.
The alternative
3.5% down
Many rent-to-own shoppers can buy today. A live person runs both numbers.
The rule
Attorney + recorded
Colorado has no rent-to-own statute; the contract is the protection.
Most people searching for rent-to-own in Commerce City can buy a home now. A 620 credit score qualifies for Colorado down-payment assistance, and a participating lender can run a program that brings the buyer’s cash to close to about $1,000: the down payment comes from the assistance, the closing costs come from the seller credit, and you keep the money a rent-to-own seller would have taken as an option fee. There is a second saving nobody mentions: the first mortgage payment is not due until the first of the month after the month you close, so a buyer who closes early in the month skips close to two months of rent on the way in.
Rent to own in Commerce City is what renters search when a lender said no, or when they think one will. The grid below lists every match live from the MLS, and the market stats under it show today's median price and price per square foot. Below, each reason a renter believes they cannot buy here, priced against the lease-option it is supposed to replace.
Every Commerce City home for sale: Commerce City homes for sale. Call or text 303-955-4220. A live person answers.
Down payment is the wall for most Commerce City renters, and it is the one with a door: a CHFA grant of $14,475 on the median Commerce City home that is never repaid, or a $19,300 second mortgage at 0 percent, plus seller-paid closing costs. You bring about $1,000. CHFA down payment assistance in Colorado and $1,000 cash to close walk it through.
A 620 is the CHFA floor, 580 is the FHA floor, and a Commerce City buyer at 590 closes with FHA this month. Under 580 the plan is 60 days on credit care, then the loan. The homes that pass the FHA appraisal: Commerce City homes that pass FHA.
The ratio that matters is every monthly payment, house included, against gross income: FHA allows 50 percent, CHFA 50 to 55. A $75,000 Commerce City buyer with $700 of other payments has $2,425 for the house. Yours is on mortgage pre-approval.
Lenders care about the line of work, not the start date: a new salaried job in your field closes with the offer letter and a pay stub. Two years of returns for the self-employed. Mortgage pre-approval in Commerce City takes a day.
The clock runs from the date on the record: three years after a foreclosure or short sale, two after a Chapter 7, one year of on-time Chapter 13 payments. A Commerce City lease-option covers the gap when it is short. Details on after a foreclosure.
A two-year lease-option is built for a maybe: you live in the Commerce City home, decide by the end of the term, and lose only the option fee if you walk. The nearby cities to compare: Thornton, Denver, Aurora, Westminster.
Nobody with a real Commerce City house to sell skips the credit check. The real deal has a lawyer-drafted option, a recorded memorandum, and a seller current on the loan; the red flags section below lists the rest.
The price lock in a lease-option costs you the premium the seller builds into it. The lock that pays is an assumable loan written at 3 percent: assumable mortgage homes in Colorado.
| Line | Typical in Commerce City | Refundable? | Credited to the price? |
|---|---|---|---|
| Option fee | 1% to 5% of the agreed price | No | Yes, at closing |
| Rent premium | $150 to $500 a month above market rent | No | Yes, as the rent credit |
| Rent credit | 10% to 30% of each payment | No | Yes, if you buy |
| Security deposit | One month | Yes, under Colorado landlord-tenant law | No |
| Maintenance | Routine repairs on you; major systems on the owner | n/a | No |
| Purchase price | Fixed the day you sign | n/a | n/a |
| Rent-to-own | Buy now with FHA + down-payment help | Keep renting | |
|---|---|---|---|
| Cash up front | 1% to 5% option fee | 3.5% down, part of it from CHFA or metroDPA | Deposit |
| Credit needed | 580 to 620 | 580 for FHA | Varies |
| Price locked? | Yes | Yes, you own it | No |
| Equity while you wait | Only the credits | All of it | None |
| Risk | Losing the fee if you cannot close | Normal ownership risk | Rent increases |
| Best for | Mortgage 12 to 24 months away | Score 580+, reserves in hand | Moving in under two years |
Compare the year-one payment with a seller credit toward the rate: seller concessions for buyers and can I afford a home now. First-time buyers: the Colorado first-time buyer guide and what closing costs are in Colorado. Buyers with a home to sell: who is buying at 7 percent.
Every city page below carries the live rent-to-own and lease-option listings, the requirements, the costs, and the questions buyers ask there.
Usually, yes. A 620 score and two years of steady income qualify for Colorado down-payment programs, and a participating lender’s $1,000 cash-to-close program pairs the assistance with a seller credit so the buyer’s own cash is about $1,000. You own the home from day one instead of paying an option fee for the right to buy it later, and you skip close to two months of rent before the first mortgage payment.
Yes, that is what the structure is for. Most sellers want a score of 580 to 620, income of about three times the monthly rent, and no eviction or bankruptcy in the last two years. Below 580 the plan is a 12-month lease with a credit-repair schedule, then the option. An FHA loan needs 580 with 3.5 percent down, so many buyers who think they need rent-to-own can buy now.
No legitimate one. A seller who skips the credit check is either pricing the risk into a high option fee and rent, or running a scam. Expect a soft pull at the application and a full pull when you exercise the option and apply for the mortgage.
The option fee, 1 to 5 percent of the agreed price: $5,000 to $25,000 on a $500,000 home. It is non-refundable if you do not buy, and it is credited to the price if you do. Compare that with 3.5 percent down on an FHA purchase, which buys the home outright today.
A lease-option gives you the right, not the obligation, to buy; you can walk away and lose the fee and credits. A lease-purchase obligates you to buy at the end of the term, and the seller can sue for the difference if you cannot close. Sign a lease-option unless a Colorado real estate attorney has read the lease-purchase and told you why it is sound for you.
Yes. Colorado has no single rent-to-own statute; the deal runs under landlord-tenant law and real estate contract law, and the Colorado Real Estate Commission requires the purchase-option contract to be drafted by a licensed attorney rather than a broker. Colorado does not require the option to be recorded, so ask for a recorded memorandum of option to protect your position if the seller sells or refinances.
Whatever the contract says. Most Colorado lease-options put routine maintenance on the tenant-buyer and keep taxes, insurance and major systems with the owner until closing. Get a home inspection before you sign, the same as a purchase, and write the roof, furnace and sewer line into the agreement.
With a lease-option you move out and forfeit the option fee and rent credits. With a lease-purchase you are in breach. That is why the plan starts with a lender: a pre-approval path with a date, so the option term matches the time it takes to fix the credit or save the difference.
Run both numbers. Colorado buyers with a 580 to 620 score and three months of reserves can buy today with FHA and a down-payment program such as CHFA or metroDPA, and a seller credit toward the rate. Rent-to-own only wins when the mortgage is 12 to 24 months away and the home is worth locking in at today's price.
Yes, as long as the HOA allows leasing and the owner holds clear title. Condos also need the building to be FHA-eligible if you plan to buy with FHA at the end; check the approval list before you pay an option fee.
Call or text 303-955-4220. A live person sends both within one business day: the sellers who will write a lease-option, and what you qualify for today.
Call or text 303-955-4220All Colorado rent-to-own homesThe cheapest Commerce City homes, on a map: every home under $400,000, and every one under $300,000, with the HOA on every tile and the programs that bring your cash to about $1,000: affordable homes for sale in Commerce City. Statewide: affordable homes in Colorado.
Disclaimer: The Kenna Group at Keller Williams DTC are real estate agents, not lenders, mortgage brokers or credit counselors. Credit scores, loan and assistance rules on this page are general information as of October 25, 2026, and programs change; a licensed lender of your choice confirms what you qualify for, and a HUD-approved housing counselor can help with credit and budgeting. Nothing here is legal advice: have a Colorado real estate attorney review any lease-option or lease-purchase contract before you sign.