New - 3 Hours Ago
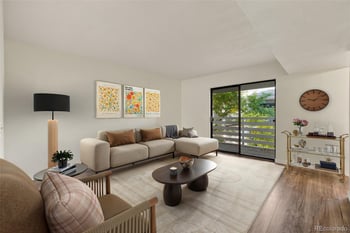
$219,900
Active
2
Beds
1
Baths
891
Sqft
--
Acres
7665 E Eastman Ave #301D, Denver, CO 80231
MLS#: REC7240107
Looking for rent-to-own homes in Denver, Colorado? 2,792 homes at $30K to $650K are the Denver listings a lease-purchase or a $1,000-cash-to-close loan reaches this week, median $399K. How rent-to-own works in Denver, the option fee, and the $1,000 cash-to-close alternative are below the homes. Call or text 303-955-4220. A live person answers.
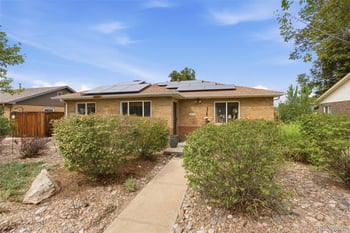
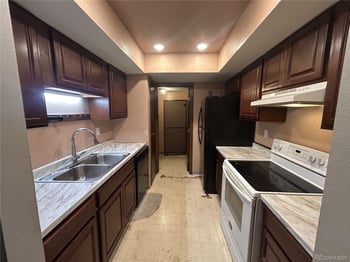
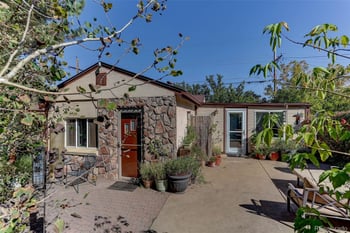
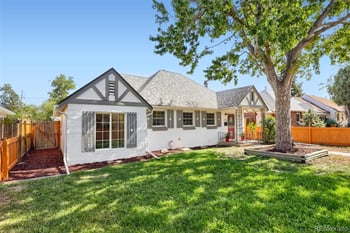
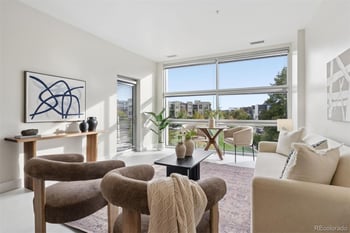
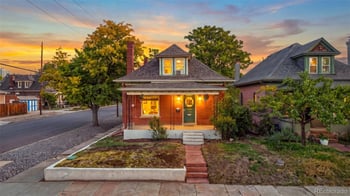
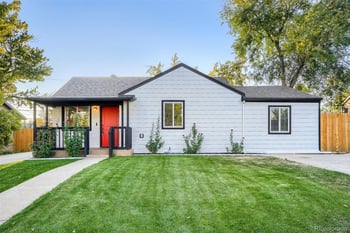
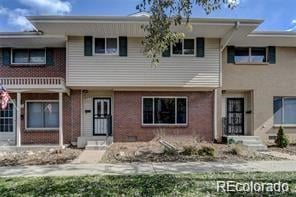
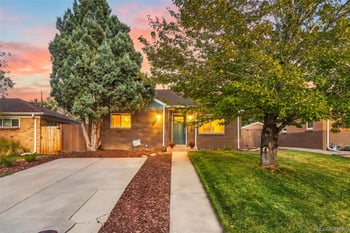

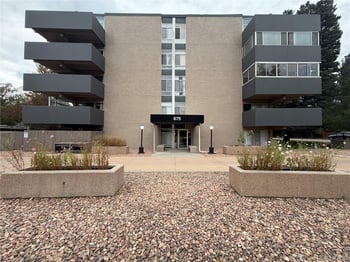

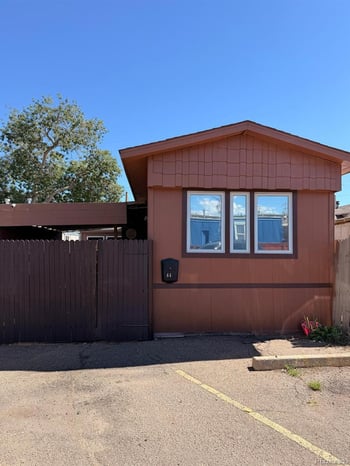
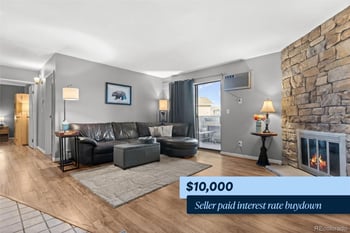
Denver rent-to-own homes let buyers move into the neighborhood they want now while building equity toward future ownership. Choices span historic bungalows near City Park, modern townhomes in Central Park, and condos along light-rail lines in southeast Denver. Many buyers value the flexibility Scroll below to view the latest rent-to-own listings in Denver and take your next step toward ownership on your terms.
The process of Rent to Own, which is now also known as Lease Purchase, has benefitted from a huge surge in popularity over the past few years, with more home buyers wanting to rent to own. Many people looking to buy a Denver area home but worried about rising costs compared with rental prices are seeing this as a viable way forward when needing to find somewhere new to live around Denver.
Kenna Real Estate believes that Rent to Own in Denver is a great move to make. Opting to use Kenna Real Estate in Denver, Colorado, is the perfect choice if you want to make the transition to becoming a Denver homeowner as straightforward as possible.
The amounts of money needed for these services are not small and are in many cases the costs that put many people off buying for the first time.
Often, people will then decide to simply stay in their rental properties, especially if they know they will want to move on within five years or so.
These aren’t the only costs that stop people from buying a new home in the Denver area. There are also outlays, such as general upkeep, maintenance, and repairs, that all fall to the person who owns the house rather than the landlord.
Property insurance also costs money and is something that needs to be carefully considered, too. Anyone who owns a home is automatically responsible for this. Persons who rent leave these issues to their landlord, too, as they’re in most cases covered by the monthly rental fees.
Rent to Own in Denver - Could it Work For You?
Rent to own in Denver is a scheme that can really reap the rewards for you if you’re currently renting a Denver area home and want to take the initial steps to Denver homeownership.
Rent to own works in the following way. People who want to buy their own Denver area home can potentially select the house they want and, after a few simple credit and background checks, move into it. They sign a lease that covers them for a period of time up to three years. During this time, they rent and can save money to buy the home outright.
Every state in America has different laws and regulations on how this will work, and no two rent-to-own contracts will be the same. Check out the rules for where you live.
The person partaking of rent to own will simply rent the property they potentially want to own for a set period of time. Usually, this amounts to between one and three years. Once this set time has elapsed, they have the option to buy the home from the seller as anyone else purchasing a home for the first time would.
As always, there are terms and conditions that must be examined carefully, but this sets out the procedure in simple terms.
Rent to own in Denver process and application
If you decide you want to opt for rent to own in Denver or the Denver Metro area, then you’ll first need to fill in a pre-qualification application form. This initial check makes sure that the person or persons applying are suitable to do so.
Anyone who is aged eighteen or older will also have to fill in the same form and have the same background checks.
Rent-to-own is just a type of financing; please contact us for information on Down payment assistance programs also available with the same criteria as rent-to-own/lease purchase.
If you're moving to Texas, check out Rental Cash Back.
Click here for some rent-to-own tips
View All Homes For Sale in Denver, CO >>>
Ready to find your dream home in Denver?
Let us help you. Call or Text Kenna Real Estate at 303-955-4220 to get personalized assistance from our expert real estate agents.
Kenna Real Estate Group at Keller Williams DTC · Call or text 303-955-4220. A live person answers, 7 days a week.
Browse Available Homes
Denver does not have a rent-to-own program; it has sellers. The homes that get written as lease-options in Denver are the finished ones that did not sell in the first month, priced at today’s number with a fee that buys you one to three years to close. This week 13 Denver homes carry a rent-to-own, lease-option or seller-financing note in the MLS, from $140K to $3.1M; the rest of the list is built by asking. Below: the requirements, the costs, the Colorado contract rules, the red flags, the other Front Range cities, and the buy-now path.
The deal
1 to 3 years
Option fee of 1 to 5 percent up front, part of the rent credited to the purchase.
What sellers want
580 to 620
No eviction or bankruptcy in the last two years. Below 580, a 12-month repair plan first.
The alternative
3.5% down
Many rent-to-own shoppers can buy today. A live person runs both numbers.
The rule
Attorney + recorded
Colorado has no rent-to-own statute; the contract is the protection.
Most people searching for rent-to-own in Denver can buy a home now. A 620 credit score qualifies for Colorado down-payment assistance, and our lender partner runs a program that brings the buyer’s cash to close to about $1,000: the down payment comes from the assistance, the closing costs come from the seller credit, and you keep the money a rent-to-own seller would have taken as an option fee. There is a second saving nobody mentions: the first mortgage payment is not due until the first of the month after the month you close, so a buyer who closes early in the month skips close to two months of rent on the way in.
Nearly everyone typing rent to own Denver into a phone is a renter who wants to own and believes one thing blocks it: the down payment, the score, the debt, a new job or an old foreclosure. Denver has 4,989 homes for sale this week and 1,797 of them are under $475,000; each of those blocks has a fix that costs less than a lease-option. The charts use the median Denver home at $500,000 and a 30-year FHA loan.
Under $475,000 right now: Denver homes $100K to $400K. Call or text 303-955-4220. A live person answers.
In Denver the down payment on the median home is $17,500 with FHA, and CHFA covers it: a 3 percent grant ($14,475) that is never repaid, or a 4 percent second mortgage at 0 percent. The seller pays closing costs through the offer. You bring about $1,000. Rules on CHFA down payment assistance, the example on $1,000 cash to close.
580 is the FHA floor with 3.5 percent down, so a 590 buys a Denver home today without any assistance. Under 580, paying every card under 30 percent of its limit and disputing errors moves most scores 20 to 40 points in 60 days: credit care. The homes that pass FHA: Denver homes that pass FHA.
Debt ratios kill fewer Denver files than renters expect: FHA allows 50 percent of income to all payments, CHFA 50 to 55. Student loans on income-based plans count at the plan payment. The exact ratio for your income is on mortgage pre-approval.
New job, same line of work: an offer letter and a pay stub are enough. Self-employed less than two years is the one that waits. Start on mortgage pre-approval.
Waiting periods, not bans: three years after a foreclosure, two after a Chapter 7, one year into a Chapter 13. If the date is inside two years, a lease-option on a Denver home gets you in now; the rest is on after a foreclosure.
Rent-to-own fits exactly this: a Denver home you want, two years to decide, and only the option fee on the line. Compare the neighbors first: Aurora, Lakewood, Thornton, Westminster.
No credit check and a few hundred dollars down is how Denver renters lose option fees. A legitimate lease-option is written by a lawyer, recorded, and sits on a home with no default. Red flags are below.
Sellers price a two-year lock above the market. Taking over a seller's 3 percent mortgage locks a lower payment and puts you on title now: Denver assumable mortgage homes, VA assumable homes.
| Line | Typical in Denver | Refundable? | Credited to the price? |
|---|---|---|---|
| Option fee | 1% to 5% of the agreed price | No | Yes, at closing |
| Rent premium | $150 to $500 a month above market rent | No | Yes, as the rent credit |
| Rent credit | 10% to 30% of each payment | No | Yes, if you buy |
| Security deposit | One month | Yes, under Colorado landlord-tenant law | No |
| Maintenance | Routine repairs on you; major systems on the owner | n/a | No |
| Purchase price | Fixed the day you sign | n/a | n/a |
| Rent-to-own | Buy now with FHA + down-payment help | Keep renting | |
|---|---|---|---|
| Cash up front | 1% to 5% option fee | 3.5% down, part of it from CHFA or metroDPA | Deposit |
| Credit needed | 580 to 620 | 580 for FHA | Varies |
| Price locked? | Yes | Yes, you own it | No |
| Equity while you wait | Only the credits | All of it | None |
| Risk | Losing the fee if you cannot close | Normal ownership risk | Rent increases |
| Best for | Mortgage 12 to 24 months away | Score 580+, reserves in hand | Moving in under two years |
Compare the year-one payment with a seller credit toward the rate: seller concessions for buyers and can I afford a home now. First-time buyers: the Colorado first-time buyer guide and what closing costs are in Colorado. Buyers with a home to sell: who is buying at 7 percent.
Every city page below carries the live rent-to-own and lease-option listings, the requirements, the costs, and the questions buyers ask there.
Usually, yes. A 620 score and two years of steady income qualify for Colorado down-payment programs, and our lender partner’s ,000 cash-to-close program pairs the assistance with a seller credit so the buyer’s own cash is about ,000. You own the home from day one instead of paying an option fee for the right to buy it later, and you skip close to two months of rent before the first mortgage payment.
You lease the home for one to three years under a written option to buy it at a price set today. You pay an option fee of 1 to 5 percent of the price up front, a monthly rent that is a little above market, and part of that rent is credited toward the purchase. At the end of the term you buy with a normal mortgage, using the credits and the option fee as part of the down payment, or you walk away and forfeit them.
The listings on this page are the Denver homes whose sellers accept a lease-option, lease-purchase or seller-financing structure, pulled live from the MLS. Most rent-to-own deals in Colorado are private agreements with an individual seller, not a program, so the inventory changes weekly. Call or text 303-955-4220 and a live person checks the current list, including the homes not marked that way in the MLS.
The option fee, 1 to 5 percent of the agreed price: $5,000 to $25,000 on a $500,000 home. It is non-refundable if you do not buy, and it is credited to the price if you do. Compare that with 3.5 percent down on an FHA purchase, which buys the home outright today.
A lease-option gives you the right, not the obligation, to buy; you can walk away and lose the fee and credits. A lease-purchase obligates you to buy at the end of the term, and the seller can sue for the difference if you cannot close. Sign a lease-option unless a Colorado real estate attorney has read the lease-purchase and told you why it is sound for you.
Yes. Colorado has no single rent-to-own statute; the deal runs under landlord-tenant law and real estate contract law, and the Colorado Real Estate Commission requires the purchase-option contract to be drafted by a licensed attorney rather than a broker. Colorado does not require the option to be recorded, so ask for a recorded memorandum of option to protect your position if the seller sells or refinances.
Whatever the contract says. Most Colorado lease-options put routine maintenance on the tenant-buyer and keep taxes, insurance and major systems with the owner until closing. Get a home inspection before you sign, the same as a purchase, and write the roof, furnace and sewer line into the agreement.
Not if the option is written correctly: the price is fixed the day you sign, and the option binds the seller for the term. Recording a memorandum of option puts the world on notice. An unrecorded option and a seller with a mortgage in default is how buyers lose their option fee.
Yes, as long as the HOA allows leasing and the owner holds clear title. Condos also need the building to be FHA-eligible if you plan to buy with FHA at the end; check the approval list before you pay an option fee.
Two months of pay stubs or a year of bank statements if self-employed, two years of W-2s or tax returns, a photo ID, the last two months of bank statements for the option fee, and your rental history. A seller who asks for a fee before showing you the home or the contract is a red flag.
Call or text 303-955-4220. A live person sends both within one business day: the sellers who will write a lease-option, and what you qualify for today.
Call or text 303-955-4220All Colorado rent-to-own homesThe cheapest Denver homes, on a map: 1,348 homes under $400,000 and 849 under $300,000 this week, with the HOA on every tile and the programs that bring your cash to about $1,000: affordable homes for sale in Denver. Statewide: affordable homes in Colorado.