New - 3 Days Ago
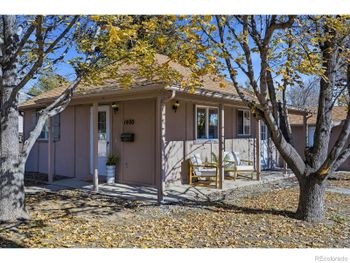
The grid below lists every match live from the MLS, and the market stats under it show today's median price and price per square foot. Rent to own homes in Louisville are private lease-option deals with individual sellers; the City of Louisville has no rent-to-own program; its affordable housing comes from an inclusionary rule on new homes. Boulder County’s down payment program covers Louisville buyers who qualify.
Get rent-to-own and low-down-payment homes in Louisville sent to you. Call or text 303-955-4220. A live person answers.
Send me the Louisville listWhat it’s like to live in Louisville: our Louisville area guide.





Louisville’s Census median value is $883,900, so a Louisville lease to own option fee of 1% to 5% runs about $8,850 to $44,250. The Kenna Group at Keller Williams DTC asks every caller one thing first: what has you looking at rent-to-own instead of buying?
620+
You may not need rent-to-own. Boulder County’s program (under 80% of area median income) and CHFA. Next step: a pre-approval call with a lender of your choice.
580 to 619
Buy with your own down payment. 580 is the FHA minimum with 3.5% down, but the 2026 FHA limit in Boulder County is $879,750, about the Census median Louisville value, so FHA fits only part of the grid; most down payment assistance programs we work with start at a 620 credit score.
Under 580
Work on credit first. A lender call will not help yet. Pull your free reports at annualcreditreport.com and ask us about the Kenna Credit Care program; we call back when the score is ready.
| Rent to own (lease option) | Buy now with down payment assistance | |
|---|---|---|
| Cash up front | Option fee, often 1% to 5% ($8,850 to $44,250), lost if you do not buy | Boulder County’s program lends up to $40,000 with $2,000 or 1% of your own money; CHFA asks for at least $1,000 |
| Credit | Set by each seller; you still need a mortgage when the lease ends | 620 for most assistance; 580 with your own 3.5% FHA down payment |
| Who owns the home | The seller, until you close | You, at closing |
| Equity while you wait | Only the rent credits the contract allows | All of it, from day one |
| Which homes | Only homes whose sellers agree to a lease option | Any Louisville home for sale: the whole grid above |
The $885,000 example is near the Census median Louisville value ($883,900); today’s average list price is $1,007,000. The 2026 Boulder County FHA and conforming limit is $879,750.
Renting versus owning in Louisville: Census 2020-2024 figures show a median rent of $2,166 and a median owner cost with a mortgage of $2,948, a $782 gap.
Checking the seller: Louisville is in Boulder County; use the Boulder County property search and recorded documents. Confirm who owns the home and whether a loan or lien is recorded before you pay any option fee.
66
Louisville homes for sale, active or coming soon, October 25, 2026
9
of them listed at $400,000 or less
0
mention rent to own, a lease option or seller financing in the MLS remarks
Only 9 of the 66 Louisville listings are at $400,000 or less. See all Louisville homes for sale.
No. Louisville’s affordable homes come from its 12% inclusionary rule, and a homeownership program is only proposed. Rent-to-own in Louisville is a private lease option.
On October 25, 2026, none of the 66 Louisville homes for sale mentioned rent to own, a lease option or seller financing in the MLS remarks.
Yes, if they qualify: it covers Boulder County outside the City of Boulder, for incomes under 80% of area median, up to $40,000, and you must be approved before going under contract.
Louisville is not on metroDPA’s city list, so plan on Boulder County’s program or CHFA.
At 1% to 5% of an $885,000 price, about $8,850 to $44,250, lost if you do not buy.
Next steps: Louisville homes for sale · CHFA down payment assistance · the $1,000 cash-to-close path · mortgage pre-approval · first-time buyer guide · Denver rent to own homes · Boulder rent to own homes · Superior rent to own homes · all Colorado rent to own homes · our Louisville area guide.
Call or text 303-955-4220. A live person answers.
Browse Available Homes
Louisville does not have a rent-to-own program; it has sellers. The homes that get written as lease-options in Louisville are the finished ones that did not sell in the first month, priced at today’s number with a fee that buys you one to three years to close. No Louisville listing carries a rent-to-own or lease-option note in the MLS this week, which is normal; the deals are made on the sitting homes, not tagged in advance. Below: the requirements, the costs, the Colorado contract rules, the red flags, the other Front Range cities, and the buy-now path.
The deal
1 to 3 years
Option fee of 1 to 5 percent up front, part of the rent credited to the purchase.
What sellers want
580 to 620
No eviction or bankruptcy in the last two years. Below 580, a 12-month repair plan first.
The alternative
3.5% down
Many rent-to-own shoppers can buy today. A live person runs both numbers.
The rule
Attorney + recorded
Colorado has no rent-to-own statute; the contract is the protection.
Most people searching for rent-to-own in Louisville can buy a home now. A 620 credit score qualifies for Colorado down-payment assistance, and a participating lender can run a program that brings the buyer’s cash to close to about $1,000: the down payment comes from the assistance, the closing costs come from the seller credit, and you keep the money a rent-to-own seller would have taken as an option fee. There is a second saving nobody mentions: the first mortgage payment is not due until the first of the month after the month you close, so a buyer who closes early in the month skips close to two months of rent on the way in.
A rent-to-own search in Louisville is a buyer with a reason: not enough saved, a score under 620, student loans, a job that started last month, a short sale in the past. With 14 of Louisville's 96 listings under $475,000, every one of those reasons has a cheaper answer than a lease-option. The numbers below run on the median Louisville home, $825,000, with a 30-year FHA loan.
Every Louisville home for sale: Louisville homes for sale. Call or text 303-955-4220. A live person answers.
In Louisville the down payment on the median home is $28,875 with FHA, and CHFA covers it: a 3 percent grant ($23,884) that is never repaid, or a 4 percent second mortgage at 0 percent. The seller pays closing costs through the offer. You bring about $1,000. Rules on CHFA down payment assistance, the example on $1,000 cash to close.
580 is the FHA floor with 3.5 percent down, so a 590 buys a Louisville home today without any assistance. Under 580, paying every card under 30 percent of its limit and disputing errors moves most scores 20 to 40 points in 60 days: credit care. The homes: all Louisville homes for sale.
Debt ratios kill fewer Louisville files than renters expect: FHA allows 50 percent of income to all payments, CHFA 50 to 55. Student loans on income-based plans count at the plan payment. The exact ratio for your income is on mortgage pre-approval.
New job, same line of work: an offer letter and a pay stub are enough. Self-employed less than two years is the one that waits. Start on mortgage pre-approval.
Waiting periods, not bans: three years after a foreclosure, two after a Chapter 7, one year into a Chapter 13. If the date is inside two years, a lease-option on a Louisville home gets you in now; the rest is on after a foreclosure.
Rent-to-own fits exactly this: a Louisville home you want, two years to decide, and only the option fee on the line. Compare the neighbors first: Lafayette, Superior, Broomfield, Erie.
No credit check and a few hundred dollars down is how Louisville renters lose option fees. A legitimate lease-option is written by a lawyer, recorded, and sits on a home with no default. Red flags are below.
Sellers price a two-year lock above the market. Taking over a seller's 3 percent mortgage locks a lower payment and puts you on title now: FHA assumable homes, VA assumable homes.
| Line | Typical in Louisville | Refundable? | Credited to the price? |
|---|---|---|---|
| Option fee | 1% to 5% of the agreed price | No | Yes, at closing |
| Rent premium | $150 to $500 a month above market rent | No | Yes, as the rent credit |
| Rent credit | 10% to 30% of each payment | No | Yes, if you buy |
| Security deposit | One month | Yes, under Colorado landlord-tenant law | No |
| Maintenance | Routine repairs on you; major systems on the owner | n/a | No |
| Purchase price | Fixed the day you sign | n/a | n/a |
| Rent-to-own | Buy now with FHA + down-payment help | Keep renting | |
|---|---|---|---|
| Cash up front | 1% to 5% option fee | 3.5% down, part of it from CHFA or metroDPA | Deposit |
| Credit needed | 580 to 620 | 580 for FHA | Varies |
| Price locked? | Yes | Yes, you own it | No |
| Equity while you wait | Only the credits | All of it | None |
| Risk | Losing the fee if you cannot close | Normal ownership risk | Rent increases |
| Best for | Mortgage 12 to 24 months away | Score 580+, reserves in hand | Moving in under two years |
Compare the year-one payment with a seller credit toward the rate: seller concessions for buyers and can I afford a home now. First-time buyers: the Colorado first-time buyer guide and what closing costs are in Colorado. Buyers with a home to sell: who is buying at 7 percent.
Every city page below carries the live rent-to-own and lease-option listings, the requirements, the costs, and the questions buyers ask there.
Usually, yes. A 620 score and two years of steady income qualify for Colorado down-payment programs, and a participating lender’s $1,000 cash-to-close program pairs the assistance with a seller credit so the buyer’s own cash is about $1,000. You own the home from day one instead of paying an option fee for the right to buy it later, and you skip close to two months of rent before the first mortgage payment.
You lease the home for one to three years under a written option to buy it at a price set today. You pay an option fee of 1 to 5 percent of the price up front, a monthly rent that is a little above market, and part of that rent is credited toward the purchase. At the end of the term you buy with a normal mortgage, using the credits and the option fee as part of the down payment, or you walk away and forfeit them.
Yes, that is what the structure is for. Most sellers want a score of 580 to 620, income of about three times the monthly rent, and no eviction or bankruptcy in the last two years. Below 580 the plan is a 12-month lease with a credit-repair schedule, then the option. An FHA loan needs 580 with 3.5 percent down, so many buyers who think they need rent-to-own can buy now.
No legitimate one. A seller who skips the credit check is either pricing the risk into a high option fee and rent, or running a scam. Expect a soft pull at the application and a full pull when you exercise the option and apply for the mortgage.
A lease-option gives you the right, not the obligation, to buy; you can walk away and lose the fee and credits. A lease-purchase obligates you to buy at the end of the term, and the seller can sue for the difference if you cannot close. Sign a lease-option unless a Colorado real estate attorney has read the lease-purchase and told you why it is sound for you.
Yes. Colorado has no single rent-to-own statute; the deal runs under landlord-tenant law and real estate contract law, and the Colorado Real Estate Commission requires the purchase-option contract to be drafted by a licensed attorney rather than a broker. Colorado does not require the option to be recorded, so ask for a recorded memorandum of option to protect your position if the seller sells or refinances.
Whatever the contract says. Most Colorado lease-options put routine maintenance on the tenant-buyer and keep taxes, insurance and major systems with the owner until closing. Get a home inspection before you sign, the same as a purchase, and write the roof, furnace and sewer line into the agreement.
Not if the option is written correctly: the price is fixed the day you sign, and the option binds the seller for the term. Recording a memorandum of option puts the world on notice. An unrecorded option and a seller with a mortgage in default is how buyers lose their option fee.
With a lease-option you move out and forfeit the option fee and rent credits. With a lease-purchase you are in breach. That is why the plan starts with a lender: a pre-approval path with a date, so the option term matches the time it takes to fix the credit or save the difference.
Two months of pay stubs or a year of bank statements if self-employed, two years of W-2s or tax returns, a photo ID, the last two months of bank statements for the option fee, and your rental history. A seller who asks for a fee before showing you the home or the contract is a red flag.
Call or text 303-955-4220. A live person sends both within one business day: the sellers who will write a lease-option, and what you qualify for today.
Call or text 303-955-4220All Colorado rent-to-own homesDisclaimer: The Kenna Group at Keller Williams DTC are real estate agents, not lenders, mortgage brokers or credit counselors. Credit scores, loan and assistance rules on this page are general information as of October 25, 2026, and programs change; a licensed lender of your choice confirms what you qualify for, and a HUD-approved housing counselor can help with credit and budgeting. Nothing here is legal advice: have a Colorado real estate attorney review any lease-option or lease-purchase contract before you sign.