New - 6 Hours Ago

$515,000
Coming Soon
4
Beds
3
Baths
2188
Sqft
0.13
Acres
4444 Decatur Ave, Castle Rock, CO 80104
MLS#: 6223885
Rent to own a home in Castle Rock? 233 Castle Rock homes under $650K fit a lease-purchase right now (median $550K), and most of the people searching rent-to-own in Castle Rock qualify to buy one outright with a 620 score. How rent-to-own works in Castle Rock, the option fee, and the $1,000 cash-to-close alternative are below the homes. Call or text 303-955-4220. A live person answers.


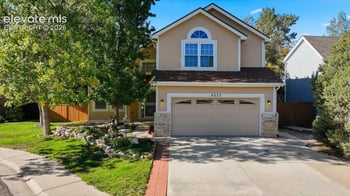


Rent-to-own homes in Castle Rock bridge the gap between renting and owning, offering flexible timelines and room to grow into long-term ownership. These properties fit buyers who want stability without rushing a full purchase, combining convenience with the chance to build equity while living in the home. Scroll below to see the latest Castle Rock rent-to-own listings and find a fit that matches your goals.
The process of Rent to Own, which is now also known as Lease Purchase, has benefitted from a huge surge in popularity over the past few years, with more home buyers wanting to rent to own. Many people looking to buy a Castle Rock area home but worried about rising costs compared with rental prices are seeing this as a viable way forward when needing to find somewhere new to live around the Castle Rock area.
Kenna Real Estate Group believes that Rent to Own in Castle Rock is a great move to make. Opting to use Kenna Real Estate Group in Castle Rock, Colorado, is the perfect choice if you want to make the transition to becoming a Castle Rock homeowner as straightforward as possible.
The amounts of money needed for these services are not small and are in many cases the costs that put many people off buying for the first time.
Often, people will then decide to simply stay in their rental properties, especially if they know they will want to move on within five years or so.
These aren’t the only costs that stop people from buying a new home in the Castle Rock area. There are also outlays, such as general upkeep, maintenance, and repairs, that all fall to the person who owns the house rather than the landlord.
Property insurance also costs money and is something that needs to be carefully considered, too. Anyone who owns a home is automatically responsible for this. Persons who rent leave these issues to their landlord, too, as they’re in most cases covered by the monthly rental fees.
Rent to Own in Castle Rock - Could it Work For You?
Rent to own in Castle Rock is a scheme that can really reap the rewards for you if you’re currently renting a Castle Rock home and want to take the initial steps to Castle Rock homeownership.
Rent to own works in the following way. People who want to buy their own Castle Rock home can potentially select the house they want and, after a few simple credit and background checks, move into it. They sign a lease that covers them for a period of time up to three years. During this time, they rent and can save money to buy the home outright.
Every state in America has different laws and regulations on how this will work, and no two rent-to-own contracts will be the same. Check out the rules for where you live.
The person partaking of rent to own will simply rent the property they potentially want to own for a set period of time. Usually, this amounts to between one and three years. Once this set time has elapsed, they have the option to buy the home from the seller as anyone else purchasing a home for the first time would.
As always, there are terms and conditions that must be examined carefully, but this sets out the procedure in simple terms.
Rent to own in Castle Rock process and application
If you decide you want to opt for rent to own in the Castle Rock area, then you’ll first need to fill out a pre-qualification application form. This initial check makes sure that the person or persons applying are suitable to do so.
Anyone who is aged eighteen or older will also have to fill out the same form and have the same background checks.
Rent-to-own is just a type of financing; please contact us for information on Down payment assistance programs also available with the same criteria as rent-to-own/lease purchase.
If you're moving to Texas, check out Rental Cash Back.
Click here for some rent-to-own tips
View All Homes For Sale in Castle Rock, CO >>>
Ready to find your dream home in Castle Rock?
Let us help you. Call or Text Kenna Real Estate Group at 303-955-4220 to get personalized assistance from our expert real estate agents.
Kenna Real Estate Group at Keller Williams DTC · Call or text 303-955-4220. A live person answers, 7 days a week.
Browse Available Homes
Castle Rock does not have a rent-to-own program; it has sellers. The homes that get written as lease-options in Castle Rock are the finished ones that did not sell in the first month, priced at today’s number with a fee that buys you one to three years to close. The Castle Rock listings carrying a lease-option or seller-financing note this week are land and commercial, not houses, so the residential deals are made by asking the sellers of homes past 45 days. Below: the requirements, the costs, the Colorado contract rules, the red flags, the other Front Range cities, and the buy-now path.
The deal
1 to 3 years
Option fee of 1 to 5 percent up front, part of the rent credited to the purchase.
What sellers want
580 to 620
No eviction or bankruptcy in the last two years. Below 580, a 12-month repair plan first.
The alternative
3.5% down
Many rent-to-own shoppers can buy today. A live person runs both numbers.
The rule
Attorney + recorded
Colorado has no rent-to-own statute; the contract is the protection.
Most people searching for rent-to-own in Castle Rock can buy a home now. A 620 credit score qualifies for Colorado down-payment assistance, and a participating lender can run a program that brings the buyer’s cash to close to about $1,000: the down payment comes from the assistance, the closing costs come from the seller credit, and you keep the money a rent-to-own seller would have taken as an option fee. There is a second saving nobody mentions: the first mortgage payment is not due until the first of the month after the month you close, so a buyer who closes early in the month skips close to two months of rent on the way in.
Rent to own in Castle Rock is what renters search when a lender said no, or when they think one will. Castle Rock lists 722 homes this week, 0 under $475,000, and the median sits at $725,000. Below, each reason a renter believes they cannot buy here, priced against the lease-option it is supposed to replace.
Every Castle Rock home for sale: Castle Rock homes for sale. Call or text 303-955-4220. A live person answers.
Down payment is the wall for most Castle Rock renters, and it is the one with a door: a CHFA grant of $20,989 on the median Castle Rock home that is never repaid, or a $27,985 second mortgage at 0 percent, plus seller-paid closing costs. You bring about $1,000. CHFA down payment assistance in Colorado and $1,000 cash to close walk it through.
A 620 is the CHFA floor, 580 is the FHA floor, and a Castle Rock buyer at 590 closes with FHA this month. Under 580 the plan is 60 days on credit care, then the loan. The homes that pass the FHA appraisal: Castle Rock homes that pass FHA.
The ratio that matters is every monthly payment, house included, against gross income: FHA allows 50 percent, CHFA 50 to 55. A $75,000 Castle Rock buyer with $700 of other payments has $2,425 for the house. Yours is on mortgage pre-approval.
Lenders care about the line of work, not the start date: a new salaried job in your field closes with the offer letter and a pay stub. Two years of returns for the self-employed. Mortgage pre-approval in Castle Rock takes a day.
The clock runs from the date on the record: three years after a foreclosure or short sale, two after a Chapter 7, one year of on-time Chapter 13 payments. A Castle Rock lease-option covers the gap when it is short. Details on after a foreclosure.
A two-year lease-option is built for a maybe: you live in the Castle Rock home, decide by the end of the term, and lose only the option fee if you walk. The nearby cities to compare: Franktown, Castle Pines, Sedalia, Larkspur.
Nobody with a real Castle Rock house to sell skips the credit check. The real deal has a lawyer-drafted option, a recorded memorandum, and a seller current on the loan; the red flags section below lists the rest.
The price lock in a lease-option costs you the premium the seller builds into it. The lock that pays is an assumable loan written at 3 percent: assumable mortgage homes in Colorado.
| Line | Typical in Castle Rock | Refundable? | Credited to the price? |
|---|---|---|---|
| Option fee | 1% to 5% of the agreed price | No | Yes, at closing |
| Rent premium | $150 to $500 a month above market rent | No | Yes, as the rent credit |
| Rent credit | 10% to 30% of each payment | No | Yes, if you buy |
| Security deposit | One month | Yes, under Colorado landlord-tenant law | No |
| Maintenance | Routine repairs on you; major systems on the owner | n/a | No |
| Purchase price | Fixed the day you sign | n/a | n/a |
| Rent-to-own | Buy now with FHA + down-payment help | Keep renting | |
|---|---|---|---|
| Cash up front | 1% to 5% option fee | 3.5% down, part of it from CHFA or metroDPA | Deposit |
| Credit needed | 580 to 620 | 580 for FHA | Varies |
| Price locked? | Yes | Yes, you own it | No |
| Equity while you wait | Only the credits | All of it | None |
| Risk | Losing the fee if you cannot close | Normal ownership risk | Rent increases |
| Best for | Mortgage 12 to 24 months away | Score 580+, reserves in hand | Moving in under two years |
Compare the year-one payment with a seller credit toward the rate: seller concessions for buyers and can I afford a home now. First-time buyers: the Colorado first-time buyer guide and what closing costs are in Colorado. Buyers with a home to sell: who is buying at 7 percent.
Every city page below carries the live rent-to-own and lease-option listings, the requirements, the costs, and the questions buyers ask there.
Usually, yes. A 620 score and two years of steady income qualify for Colorado down-payment programs, and a participating lender’s $1,000 cash-to-close program pairs the assistance with a seller credit so the buyer’s own cash is about ,000. You own the home from day one instead of paying an option fee for the right to buy it later, and you skip close to two months of rent before the first mortgage payment.
You lease the home for one to three years under a written option to buy it at a price set today. You pay an option fee of 1 to 5 percent of the price up front, a monthly rent that is a little above market, and part of that rent is credited toward the purchase. At the end of the term you buy with a normal mortgage, using the credits and the option fee as part of the down payment, or you walk away and forfeit them.
Yes, that is what the structure is for. Most sellers want a score of 580 to 620, income of about three times the monthly rent, and no eviction or bankruptcy in the last two years. Below 580 the plan is a 12-month lease with a credit-repair schedule, then the option. An FHA loan needs 580 with 3.5 percent down, so many buyers who think they need rent-to-own can buy now.
No legitimate one. A seller who skips the credit check is either pricing the risk into a high option fee and rent, or running a scam. Expect a soft pull at the application and a full pull when you exercise the option and apply for the mortgage.
The option fee, 1 to 5 percent of the agreed price: $5,000 to $25,000 on a $500,000 home. It is non-refundable if you do not buy, and it is credited to the price if you do. Compare that with 3.5 percent down on an FHA purchase, which buys the home outright today.
A lease-option gives you the right, not the obligation, to buy; you can walk away and lose the fee and credits. A lease-purchase obligates you to buy at the end of the term, and the seller can sue for the difference if you cannot close. Sign a lease-option unless a Colorado real estate attorney has read the lease-purchase and told you why it is sound for you.
With a lease-option you move out and forfeit the option fee and rent credits. With a lease-purchase you are in breach. That is why the plan starts with a lender: a pre-approval path with a date, so the option term matches the time it takes to fix the credit or save the difference.
Run both numbers. Colorado buyers with a 580 to 620 score and three months of reserves can buy today with FHA and a down-payment program such as CHFA or metroDPA, and a seller credit toward the rate. Rent-to-own only wins when the mortgage is 12 to 24 months away and the home is worth locking in at today's price.
Yes, as long as the HOA allows leasing and the owner holds clear title. Condos also need the building to be FHA-eligible if you plan to buy with FHA at the end; check the approval list before you pay an option fee.
Two months of pay stubs or a year of bank statements if self-employed, two years of W-2s or tax returns, a photo ID, the last two months of bank statements for the option fee, and your rental history. A seller who asks for a fee before showing you the home or the contract is a red flag.
Call or text 303-955-4220. A live person sends both within one business day: the sellers who will write a lease-option, and what you qualify for today.
Call or text 303-955-4220All Colorado rent-to-own homesThe cheapest Castle Rock homes, on a map: 37 homes under $400,000 and 11 under $300,000 this week, with the HOA on every tile and the programs that bring your cash to about $1,000: affordable homes for sale in Castle Rock. Statewide: affordable homes in Colorado.