New - Just Now
Kenna Real Estate Group · A fresh start in Colorado
Buying a house after divorce in Colorado comes down to three things: when the decree is final, whether support counts as income yet, and getting your name off the old mortgage. Here is how each one works, what one income buys, and the assistance that replaces the second paycheck.
A live person answers. Not a robot, not a phone tree.
A home bought during the marriage is marital property in Colorado. The decree or a signed agreement with a court order puts the next home in your name alone.
Alimony and child support count once they have been paid six months and the decree shows them continuing three years.
Refinance, assumption, or 12 months of your former spouse paying it from their own account under the decree.
3 percent grant or 4 percent second mortgage at a 620 score; your own money is about $1,000.
Three exits, priced below. The Smart Pricing Report sets the number the agreement uses.
From final decree to keys, when the paperwork is lined up before the decree lands.
Every lender in Colorado reads the decree before it reads your pay stubs: who keeps the house, who pays the mortgage, what support is owed and for how long. The decree written with the mortgage in mind is the one that lets you buy in 90 days; the one written without it costs a year. The housing side of the agreement, clause by clause, is on real estate and divorce in Colorado, and the live workshops are on Colorado divorce workshops.
The lender adds the support to the salary once it qualifies, caps total debt at half of that, subtracts your other payments, and the rest is the house payment with taxes, insurance and mortgage insurance inside it. On these numbers that is about a $350,000 FHA loan at 7 percent. CHFA assistance replaces the down payment the second income used to supply; the program is on CHFA down payment assistance in Colorado and the full worked example on $1,000 cash to close. Your own ratio runs on mortgage pre-approval.
$600,000 sale, 8 percent in commissions, closing costs and repairs, $300,000 loan paid off, $252,000 split two ways. Each side has a down payment and a clean credit file. The agents who handle this sale weekly are on the Denver divorce realtors page and the other city pages.
The spouse who stays takes a new $426,000 loan: the old balance plus the other spouse's $126,000 share. It works only when that spouse qualifies alone and the payment fits. Timing on refinancing a Colorado home.
No cash to either side today, both names stay on the loan, and the spouse who left cannot buy until it sells. The exit with the highest cost in time.
The number every exit depends on is the home's value, and the number the court accepts is a report built from the last 90 days of sales within a mile, not a portal estimate. That is the Smart Pricing Report on home valuation; the equity math is on home equity.
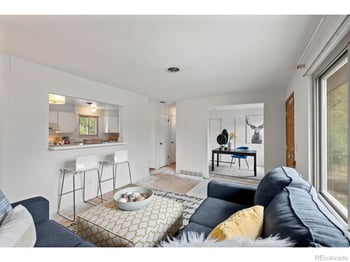
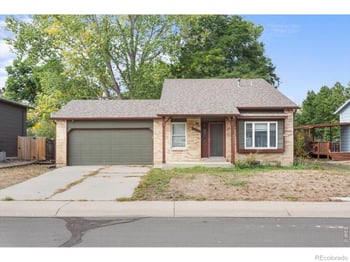
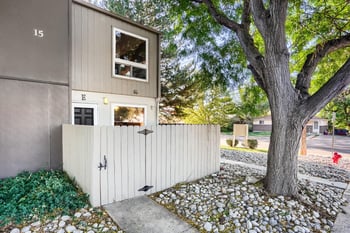
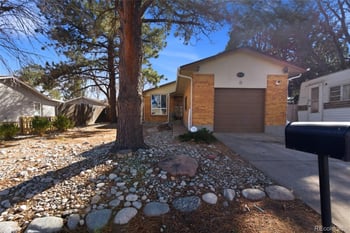
Each county page lists the agents who handle the marital-home sale and the next purchase, the local court's timeline, and the homes that fit one income there: Denver County, Arapahoe County, Jefferson County, Adams County, Douglas County, Boulder County, Broomfield County, El Paso County, Larimer County, Elbert County. Homes that fit one income with assistance: Denver homes that pass FHA, Aurora, Thornton, Westminster, Greeley, Colorado Springs under $400,000.
Colorado treats anything bought during the marriage as marital property until the decree, so a home bought before the decree is on the table for division. Buy after the decree, or with a signed separation agreement and a court order that assigns the new home to you alone. The lender wants the same paper. The housing side of the decree is on real estate and divorce in Colorado.
Yes, when it has been paid for six months and the decree shows it continuing for three more years. The lender wants the decree and six months of deposits. Support that has not started yet does not count, so the timing of the decree sets the timing of the purchase. The ratio run is on mortgage pre-approval.
Yes, until your name comes off through a refinance or an assumption, or the decree assigns the payment to your former spouse and the lender sees 12 months of that spouse paying it from their own account. A quitclaim deed moves the title, not the loan. Refinance timing is on refinancing a Colorado home; taking over an FHA or VA loan is on assumable mortgage homes.
The same way as anyone at that income, with assistance doing the work the second income used to. CHFA pays up to 3 percent of the loan as a grant or 4 percent as a 0 percent second mortgage at a 620 score, and the seller pays closing costs through the offer; your own money is about $1,000. The program is on CHFA down payment assistance in Colorado; the worked example on $1,000 cash to close.
Colorado divides marital property fairly, not automatically in half, and the court looks at who can carry the house. In practice there are three exits: sell and split the equity, one spouse buys the other out by refinancing, or a deferred sale where one spouse stays for a set time and the home sells later. The chart above prices all three on a $600,000 home. Pricing the home for any of them starts on home valuation.
Keep it only if you qualify to refinance the full balance plus the buyout on your income alone and the payment fits under 45 percent of that income. The equity in a house pays no bills; the $126,000 from a sale is a down payment on a home you can carry. The numbers are on home equity; the city agents who handle the sale are on Denver divorce realtors, Aurora, Colorado Springs, Littleton, Greeley and Fort Collins.
FHA closes at 580 with 3.5 percent down and CHFA at 620. Close the joint cards, pull your own report, dispute what is not yours, and pay revolving balances under 30 percent of their limits; most scores move 20 to 40 points in 60 days. The plan is on credit care.
The day the decree is final and your name is off the old loan. With support income already flowing for six months and a pre-approval in hand, buyers close 90 to 120 days after the decree. The timeline is in the chart above; the step list is on the Colorado divorce workshops.
No. A lease-option on a $450,000 home takes a $13,500 option fee and a rent premium and leaves you with no title; assistance puts you on title now for about $1,000. The comparison with charts is on rent-to-own in Colorado.
The Colorado Divorce Decisions workshops and the guide on divorce and the house, for women walk the decree, the mortgage and the buyout step by step; the county pages list the agents who do this every week: Denver County, Arapahoe County, Jefferson County, Douglas County, El Paso County, Larimer County.
Text DIVORCE and the address to 303-955-4220. A live person answers, sends the Smart Pricing Report on the marital home within one business day, and runs the one-income pre-approval with our lender partner so you know what the next home looks like before you sign the agreement.
Call or text 303-955-4220 Real estate and divorce in Colorado