Do not sign anything about the house yet
Not a quitclaim deed, not a listing agreement, not a refinance. Get the value in writing and talk to an attorney first.
Divorce real estate · Colorado
The questions women ask us most, answered straight: what to do now, whether you can keep the house when he earned more, how to qualify on your own, and how to downsize without losing ground. Everything here applies to any spouse.
A live person answers. Not a robot, not a phone tree. Everything you tell us stays private.
Not a quitclaim deed, not a listing agreement, not a refinance. Get the value in writing and talk to an attorney first.
Colorado divides marital property fairly, and a homemaker's contribution counts under C.R.S. 14-10-113.
Maintenance and child support count as income for a mortgage once they have a history. We work with lenders who do this every week.
Patio homes, condos, townhomes and 55+ communities cost less to carry. We help you find one after the sale, privately.
Start here
Three things this week. One: find out what the house is worth and what is owed on it, in writing. Two: open a bank account and a credit card in your own name if you do not have them. Three: talk to a family law attorney, even for one hour, before you agree to anything about the house. Then call us. We will tell you what the house would net, what it would take to keep it, and what a smaller place would cost, with no pressure and nothing shared with your spouse.
Maybe, and the answer is math, not fairness. To keep the house you need to get his name off the loan, which means refinancing in your own name, or a settlement that lets you stay on the existing loan for a set time.
Divorce Decisions covers this in more depth: Keeping the house, Mortgage qualification after divorce and Equity and spousal buyouts.
See Living on one income after divorce, Maintenance in Colorado and Retirement and pensions in divorce on Divorce Decisions.
Six moves that protect your share of the house and set up the next one.
What the house is worth, what is owed, what it costs to run. In writing.
A checking account and a credit card in your name only.
Temporary orders, maintenance, who pays the mortgage.
Find out what you can qualify for alone, before anyone decides who keeps the house.
Put the decision and the dates in the separation agreement.
Pre-approved, proceeds as the down payment, a home you can carry.
Tap a home type to see what is for sale across the Front Range, or pick a city.
Read Downsizing after divorce, House to condo after divorce, Rent or buy after divorce and Buying after divorce.
Divorces after 50 are the fastest-growing kind, and the house is usually paid down and full of thirty years of things. The equity is large, the income is fixed, and the next home should be one level, low maintenance and close to people you love. We sell the big house, help sort what stays and what goes, and find the right-sized place, in that order.
See Gray divorce in Colorado and Sorting a house full of memories, plus our own gray divorce guide and patio homes for solo buyers at 60.
Intelligence reports provided by  ™
Free for every seller
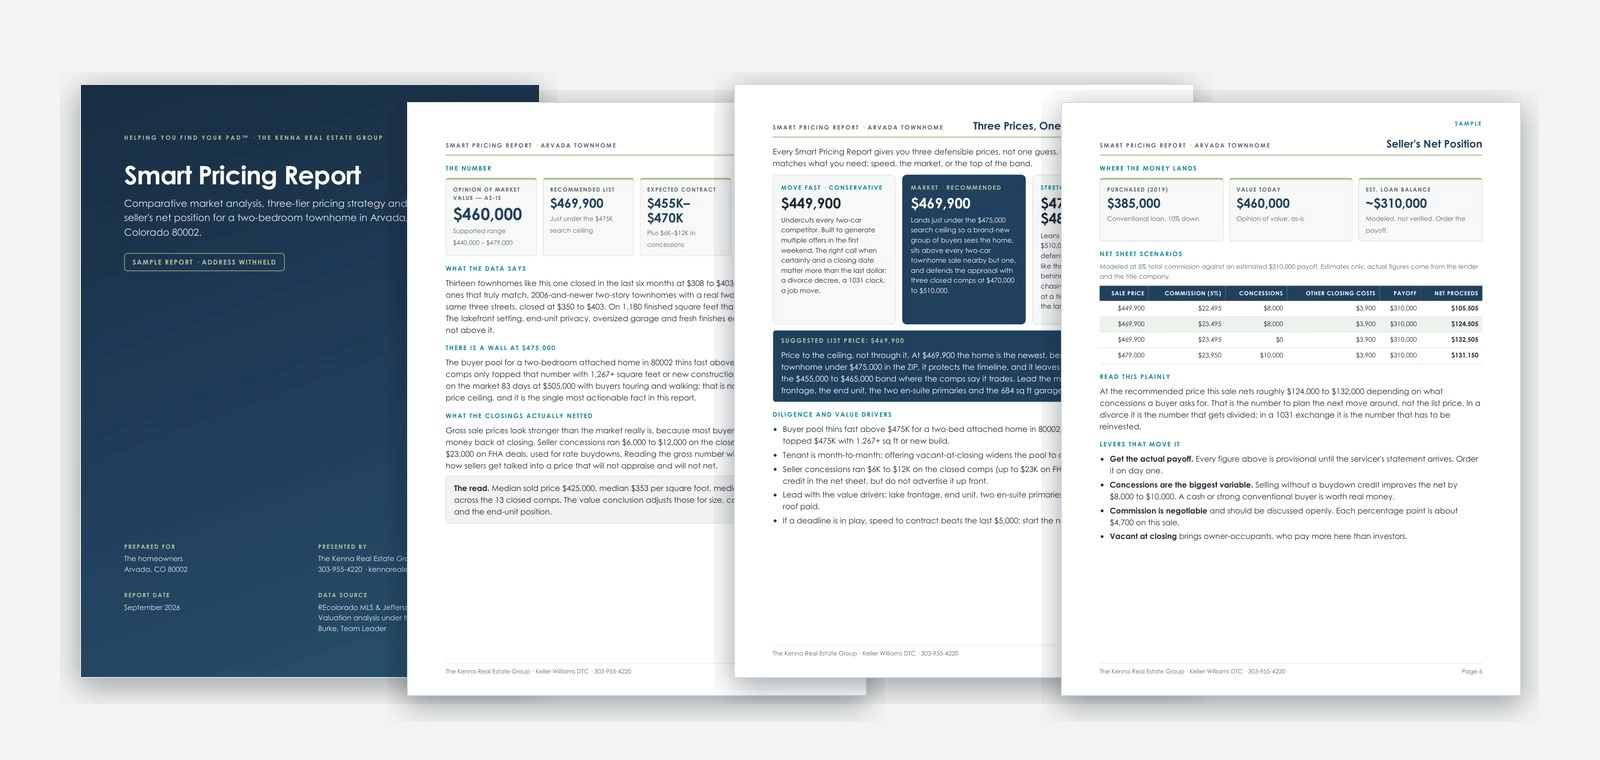
One number both spouses can trust, delivered to both of you at the same time. The Smart Pricing Report™ is Kenna Real Estate Group's proprietary pricing analysis for Colorado homes: three defensible prices, the comps with concessions netted out, your net sheet and a written strategy. Not a generic CMA. Free.
Call or text 303-955-4220A live person answers. Not a robot, not a phone tree. We start on your report the same day.
Undercuts every competitor. Built for multiple offers in the first weekend when the closing date matters most.
Just under the search ceiling, above the field, defended by three closed comps. The price that sells and appraises.
Leans on the top two sales. Only if the interior shows like them. The risk is chasing the market down.
Three prices above are from a real September 2026 Arvada townhome report, address withheld. Every report is a broker's opinion of value, not an appraisal.
Not if you are on the deed. Both owners must sign. If only his name is on the deed but the home was bought during the marriage, it is still marital property and the court can stop a sale. Tell your attorney immediately if you think a sale is being arranged.
Not on his own. Only a court order, usually a temporary order or a protection order, decides who stays. Leaving voluntarily does not give up your ownership, but talk to your attorney before you move.
Whatever the temporary orders or your written agreement say. Until then, the loan is still in both names and a missed payment hurts both credit scores. Get it in writing early.
Not automatically. The judge can weigh whether the parent with the children should stay for a time, but you still have to be able to pay for it. Many settlements give the parent with the kids the home until a set date, then sell.
Possibly. Lenders can count maintenance and child support as income once payments are documented, and some programs accept a shorter work history if you are returning to your field. A pre-approval conversation costs nothing and tells you where you stand.
Ask for a written market analysis with the comparable sales, not an online estimate. If your attorney wants it, a licensed appraisal adds a number the court will accept. We provide the analysis free, to both spouses if you both want it.
Be careful. A house costs money every month and its equity is only real when it sells; a retirement account grows. Have a CPA or a certified divorce financial analyst run both scenarios before you choose.
No. Some settlements delay the sale until the end of the year, a job change, or a child's milestone, with a firm list date. Make sure the agreement says who pays what until then.
No. The listing never mentions it, showings are scheduled around you, and both spouses get the same information at the same time.
The filing fee is $260 and the response fee is $146. Attorney fees vary widely; mediation is far cheaper than a trial. Divorce Decisions has a full breakdown of what a Colorado divorce costs.
You come first. Colorado courts issue protection orders, and the court will not send an abuse case to mediation if you object. If you need to leave, leave. The house can be handled afterward through your attorney and a neutral agent, without you ever being in the same room.
Yes. A consultation with us is private. We do not contact the other spouse unless and until both of you hire us to sell the home.





Every city has its own page with the local court, neighborhoods and homes for sale: Real estate and divorce in Colorado lists them all. Popular pages: Denver, Aurora, Lakewood, Littleton, Highlands Ranch, Centennial, Parker, Castle Rock, Arvada, Westminster, Thornton, Broomfield, Boulder, Fort Collins, Greeley, Colorado Springs.
Women-specific resources on Divorce Decisions: Women and divorce in Colorado, Just served divorce papers, Colorado divorce checklist, Running a home alone after divorce.
From our blog: How divorce affects qualifying for a mortgage, Keeping your home during divorce, Selling a house during a divorce, Home appraisal in divorce. All: divorce articles.
Free, private, no pressure
A free, private conversation. Nothing is shared with your spouse.
The Kenna Real Estate Group is a team of REALTORS® and licensed real estate professionals, not attorneys, CPAs or financial advisors. Nothing on this page is legal, tax or financial advice, and nothing here creates an attorney-client relationship. Colorado divorce law changes and every case is different. Before you sign a listing agreement, a deed, a refinance or a settlement, talk to a Colorado family law attorney, and to a CPA about taxes. We will gladly work alongside them. The Smart Pricing Report™ is a broker's opinion of value, not an appraisal. Equal Housing Opportunity.
Fill out the form and we will send your Smart Pricing Report™ (three prices, the comps and a written strategy) plus the 20-page Colorado divorce home guide. Nothing is shared with your spouse unless you ask us to send it to both of you. You can also download the guide right now on Divorce Decisions.