$245,400
Active
2
Beds
2
Baths
1184
Sqft
0.01
Acres
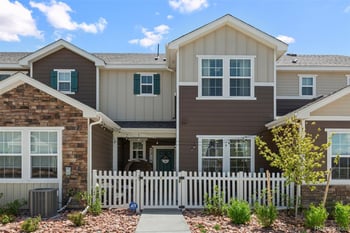
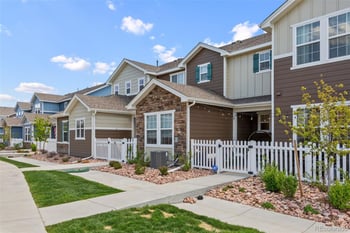
4019 Charleston Dr, Colorado Springs, CO 80916
MLS#: REC4938857
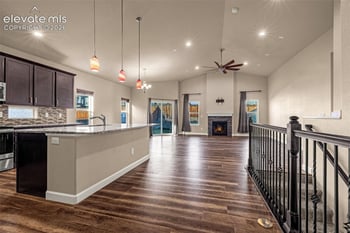
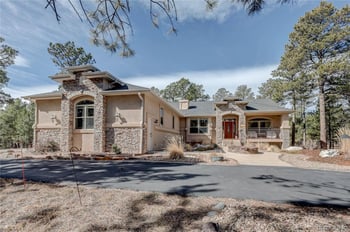
Every listing on this page says the seller's loan can be assumed. On an FHA or VA loan from 2020 to 2022 that means a rate in the 2s or 3s instead of today's rate. The catch: you pay the seller's equity in cash or with a second loan, you qualify with the servicer, and the servicer takes 45 to 120 days. VA loans can be assumed by non-veterans, but the seller's entitlement stays tied up unless the buyer is also VA-eligible.
Yes, if the servicer approves you. A non-veteran buyer can assume a VA loan, but the seller's VA entitlement stays with the loan until it is paid off, which many sellers refuse.
Plan on 45 to 120 days from application to closing. Servicers are slow and the seller has to stay patient.
You need the equity gap. If the home is $500,000 and the loan balance is $380,000, you need $120,000 in cash or a second loan.
Call or text 303-955-4220. A live person answers. Read the Colorado assumable mortgage guide, compare FHA and VA buying, or see what sellers are giving buyers right now.