New - 1 Day Ago


$479,900
Active
4
Beds
4
Baths
2325
Sqft
0.18
Acres
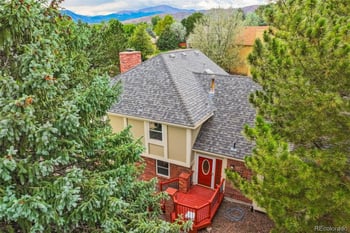
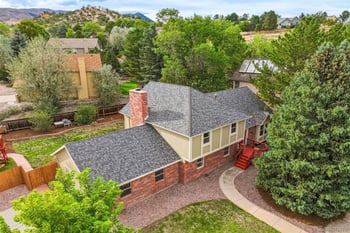
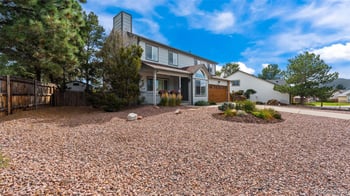
8045 Sangor Dr, Colorado Springs, CO 80920
MLS#: REC6426274


CHFA Schools To Home is a Colorado homebuying program built for full-time public school employees. If you work full time for Academy School District 20 — or an eligible D20-area charter school, institute charter school, BOCES, or innovation zone — you may qualify for a 30-year fixed conventional mortgage paired with a deferred second mortgage worth up to 25% of your first mortgage amount.
That assistance can go toward your down payment, closing costs, prepaids, or principal reduction, with no monthly payment and no interest while the second mortgage remains outstanding.
Many qualified Academy D20 employees can receive up to 25% down payment assistance while purchasing with as little as $1,000 cash to close, subject to CHFA guidelines, transaction costs, and lender approval.
Here's what doesn't change no matter where in Colorado you buy:
The assistance is not a grant. When you sell, refinance, pay off your first mortgage, or stop using the property as your primary residence, you'll repay the assistance along with a share of the home's appreciation according to CHFA guidelines.
Program terms reflect CHFA's published Schools To Home guidelines. Always verify current eligibility and loan terms with a participating CHFA lender before making an offer.
Colorado created the Schools To Home program to help full-time public school employees overcome one of the biggest barriers to homeownership: saving enough for a down payment. The program came out of bipartisan legislation passed during the 2025 Colorado legislative session and is administered by the Colorado Housing and Finance Authority (CHFA), funded through the Public School Permanent Fund.
Academy District 20 covers a fast-growing stretch of northern Colorado Springs, from Briargate down through the Air Force Academy area and out toward Monument. Home prices here have climbed as new subdivisions continue to develop along the I-25 corridor.
For a first-year D20 paraprofessional, bus driver, longtime custodian, teacher, or other full-time employee, saving a traditional down payment can take years. Schools To Home exists to help close that gap.
No. Schools To Home is not a grant and it is not loan forgiveness. It is a real second mortgage with a real repayment obligation. What it does is let many Academy D20 employees buy years sooner by dramatically reducing the cash needed upfront. Whether that trade-off makes sense depends on your situation, your plans, and how long you expect to stay in the home.
CHFA's eligibility rules are intentionally broad. If you're classified as a full-time employee by an eligible Colorado public school employer, your job title generally doesn't matter.
Whether you teach in the classroom, drive a bus, prepare school meals, maintain facilities, support students, or work in administration, Schools To Home is based on your employment status — not simply your job title.
Potentially eligible positions can include:
How to verify your employer: CHFA verifies eligible employers through the Colorado Department of Education SchoolView database. Your employer must be listed as a Public school. Private schools, religious schools, and independent schools are not eligible.
Yes. Your employer must classify you as a full-time employee. Part-time employees, substitute teachers, and seasonal staff generally do not qualify on their own.
That's fine. Only one borrower on the mortgage needs to be the eligible school employee. Your spouse or co-borrower can work in any other field — including active-duty military, which is common for households near the Air Force Academy — while the household still qualifies under Schools To Home.
The assistance is up to 25% of your first mortgage amount, not the home's purchase price. Those are different numbers, and the difference matters.
There are also two loan limits that work together: a maximum 97% loan-to-value (LTV) on the first mortgage and a maximum 105% combined loan-to-value (CLTV) after adding the Schools To Home assistance.
| Purchase price | $525,000 |
| First mortgage (80% LTV) | $420,000 |
| Schools To Home assistance | $105,000 |
| Cash needed for down payment | $0 |
| PMI | None |
| Purchase price | $525,000 |
| First mortgage (84% LTV) | $441,000 |
| Schools To Home assistance | $110,250 |
| Combined financing | $551,250 |
| PMI | Required |
For many qualified buyers, the program can reduce the cash needed to close to around $1,000, depending on seller concessions, prepaid expenses, loan structure, transaction costs, and lender approval. The exact structure depends on automated underwriting, your credit profile, and your lender's recommendations.
Yes. The maximum first mortgage is the lower of $832,750 or the applicable Fannie Mae conforming loan limit plus financed mortgage insurance — well above what most Academy D20 households need to borrow.
No. If your income qualifies and your loan amount fits CHFA guidelines, you can buy anywhere in Colorado — letting D20 staff consider Briargate, the Air Force Academy area, Monument-adjacent neighborhoods, or other communities rather than being limited to the least expensive pockets of the district.
The statewide qualifying income limit is $178,920. The same limit applies in El Paso County as everywhere else in Colorado, and it does not vary by household size.

Our lender partner, Mike Oswald, can compare financing structures and show exactly how much assistance may be available based on your price range. No obligation — just real numbers.
Schools To Home uses a shared appreciation model instead of charging interest on the second mortgage. When the loan becomes due, you repay the original assistance amount plus a percentage of the home's appreciation.
CHFA divides your original assistance amount by your original purchase price. That percentage is fixed at closing and does not change. On a $525,000 purchase with $105,000 of assistance, that's a 20% shared-appreciation rate.
Appreciation is your sale price minus your original purchase price. On a $525,000 purchase sold for $685,000, appreciation is $160,000. At a 20% shared-appreciation rate, the illustrative shared-appreciation repayment would be 20% × $160,000 = $32,000, in addition to repaying the original assistance.
If your home's value stays flat or declines, you still repay the original assistance amount, but negative appreciation counts as zero. You never owe a share of a loss.
The second mortgage becomes due if you sell your home, refinance, pay off the first mortgage, or the property stops being your primary residence. Converting the home into a rental while the loan is outstanding triggers repayment.
Yes — but refinancing counts as a repayment event. You'll need enough equity to cover the original assistance and applicable shared appreciation, so evaluate any refinance carefully with your lender first.
Let's say you're a full-time Academy D20 employee buying a home near Briargate for $525,000, using Structure A.
| Illustrative structure | |
|---|---|
| Purchase price | $525,000 |
| First mortgage | $420,000 |
| Schools To Home assistance | $105,000 |
| Minimum borrower contribution | $1,000 |
| Shared-appreciation percentage | 20% |
For illustration only, if the home appreciated from $525,000 to $685,000:
| Appreciation | $160,000 |
| Shared appreciation owed at 20% | $32,000 |
| Original assistance repaid | $105,000 |
| Illustrative total repaid to CHFA | $137,000 |
Although you repay part of the appreciation, you've also benefited from years of homeownership, principal paydown, and market appreciation that may not have been possible had you waited to save a traditional down payment.
The honest comparison: The real question isn't whether shared appreciation costs money — it does. It's whether waiting several more years to save a large down payment would leave you in a stronger position than buying sooner. For some D20 employees, this program means building equity years earlier. For others who've already saved a substantial down payment, a conventional loan may cost less overall. Compare both scenarios before you decide.
Schools To Home can be an excellent fit for many Academy D20 employees, but it isn't right for everyone.
Everything below reflects the published CHFA Schools To Home program guidelines.
The program allows several eligible owner-occupied property types, subject to CHFA and Fannie Mae requirements:
Academy D20's housing stock leans heavily toward newer single-family construction and townhomes, especially in Briargate and newer subdivisions pushing north toward Monument, with a mix of older ranch-style homes closer to the Air Force Academy's original growth corridor.
Academy District 20 stretches across a wide swath of northern Colorado Springs, so "buying close to work" can look very different depending on which school you're assigned to.
The district's commercial and residential core, with newer single-family homes, townhomes, shopping, and quick access to I-25. Prices run toward the higher end of the district, but inventory and amenities are strong.
Browse homes in Briargate.A broad mix of established neighborhoods and newer infill closer to the district's southern boundary, generally more attainable than Briargate proper while staying inside D20 boundaries.
Browse homes in Colorado Springs.Unincorporated El Paso County neighborhoods pushing toward Monument offer larger lots and newer construction. They can appeal to buyers wanting more space and a quieter feel while remaining within a reasonable commute to D20 schools.
Browse homes in El Paso County.Neighborhoods near the Academy see steady turnover tied to military relocation cycles, and many D20 households include an active-duty or veteran co-borrower. VA financing may be worth comparing against Schools To Home for military-affiliated buyers.
Browse homes near the Air Force Academy.Rather than relying on citywide averages, compare current local market data and active listings that match your budget, commute, and the specific D20 attendance area you're targeting.
Buying in D20's footprint involves a different diligence list than buying in Denver or the mountain corridor. Here's what we encourage every buyer to evaluate carefully.
Colorado Springs experiences significant hail activity. Ask what's been claimed and what's been replaced on the roof, and expect your insurer to want documentation or photos before binding a policy.
Much of D20's inventory is newer, fast-built subdivision construction. A newer home still benefits from an independent inspection. Municipal inspection is a minimum standard, not a substitute for an independent inspection.
Many newer developments north of Colorado Springs carry metro district assessments in addition to standard property taxes. Understand the full monthly payment rather than looking only at the mortgage.
Because Schools To Home requires a full appraisal and does not permit a PIW, build your offer timeline and terms around that reality rather than assuming an appraisal waiver will be available.
No. It is a deferred second mortgage with shared appreciation.
No. There are no monthly payments and no interest accrues while the second mortgage remains outstanding.
Up to 25% of your first mortgage amount, subject to CHFA guidelines.
50% for a mid FICO of 620–659, or 55% for a mid FICO of 660 or above. Automated underwriting can be more restrictive, so treat 55% as a ceiling, not a target.
No. Cosigners and non-occupying co-borrowers are not permitted, and a non-borrowing spouse cannot take title.
Yes, if it is on a permanent foundation and meets applicable Fannie Mae guidelines and DU approval.
Yes. Every borrower must complete a CHFA-approved Homebuyer Education course, plus CHFA's "Understanding Your Financial Commitment" course and quiz.
Yes. The $1,000 minimum borrower contribution may be gifted, subject to applicable requirements.
The lower of $832,750 or the applicable Fannie Mae conforming loan limit plus financed mortgage insurance.
No. Previous homeowners may also qualify.
The statewide qualifying income limit is $178,920, the same in El Paso County as anywhere else in Colorado.
No. Schools To Home has no separate purchase price limit.
A minimum middle score of 620, or higher if required by the loan type.
Yes. The program covers eligible full-time employees of qualifying public school employers, regardless of job title.
Eligible D20-authorized charter schools and institute charter schools are included, along with qualifying district schools, BOCES, and innovation zones.
No. Only one borrower must be the eligible school employee, including households where the co-borrower is active-duty military.
Potentially, provided all applicable occupancy, mortgage, title, and program requirements are satisfied.
Yes, eligible condos, townhomes/PUDs, and homes with qualifying ADUs can potentially qualify subject to applicable requirements.
Not while the assistance remains outstanding. Converting the home to a rental can trigger repayment.
Refinancing can trigger repayment of both the assistance and applicable shared appreciation.
Negative appreciation is treated as zero appreciation. You repay the original assistance but not a share of a loss.
No. Subordinate financing is not permitted.
No. Interest-rate buydowns are not allowed under Schools To Home.
Call the Kenna Real Estate Group at 303-955-4220. Our lender partner is Mike Oswald, New American Funding, NMLS #261003.
One conversation can tell you whether you qualify, how much assistance may be available, and whether Schools To Home or another financing option is the better fit. No cost, no obligation — just honest guidance based on your goals.
Every eligible Colorado public school district gets its own Schools To Home breakdown. Explore the statewide hub and district-specific guides below.
If you work for another Colorado public school district, use the hub above to find your district-specific guide.
Program details summarized from the Colorado Housing and Finance Authority (CHFA) Schools To Home program and are subject to change. This article is provided for general informational purposes only and is not a commitment to lend, an offer of credit, or a guarantee of eligibility, loan terms, assistance amounts, or approval. Eligibility, income limits, loan limits, credit requirements, homebuyer education requirements, loan structure, and shared appreciation terms are determined by CHFA and a participating CHFA lender. Verify eligible employers using the Colorado Department of Education SchoolView database. The Kenna Real Estate Group is a real estate brokerage and does not originate loans. Not affiliated with, sponsored by, or endorsed by Academy School District 20. Each office is independently owned and operated. Equal Housing Opportunity.