New - Just Now
$449,990
Active
3
Beds
3
Baths
1840
Sqft
0.0966
Acres
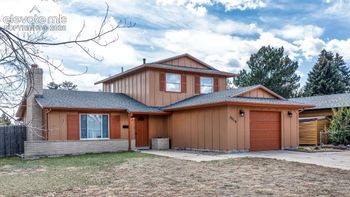
8514 Blue Feather Loop, Colorado Springs, CO 80908
MLS#: 3121439


Full-time employees of a Colorado Charter School Institute school can qualify for CHFA Schools To Home, a statewide down payment assistance program worth up to 25% of a first mortgage, whether that CSI school sits in Denver, Aurora, Colorado Springs, Fort Collins, or a smaller Colorado community.
CSI is a statewide charter public school authorizer, not a single district tied to one city. Its portfolio spans schools across Colorado, from Aurora, Denver, and Westminster to Colorado Springs, Fort Collins, Grand Junction, Durango, Steamboat Springs, Salida, and Fruita. Because CSI isn't geographically bound the way a district like Denver Public Schools or Jeffco is, its employees are a genuinely statewide Schools To Home audience.
CHFA Schools To Home is a Colorado Housing and Finance Authority program for eligible full-time public school employees. It pairs a 30-year fixed-rate first mortgage with an optional deferred second mortgage worth up to 25% of the first mortgage, at zero percent interest with no monthly payment while it remains outstanding.
The assistance can cover down payment, closing costs, prepaid expenses, or principal reduction. It is not a grant: the assistance is repaid, along with a share of your home's appreciation, when a repayment event occurs.
Important:
Schools To Home assistance is a deferred second mortgage, not free money. The repayment terms and shared-appreciation component should be reviewed carefully with your participating lender before you purchase.
CHFA's eligible-employer definition specifically names institute charter schools alongside district schools and BOCES, and CSI schools fall under that definition.
At least one borrower on the loan must be classified full time by an eligible CSI school; job title doesn't decide eligibility, employment classification does.
This can cover roles such as:
| Classroom staff | Paraprofessionals | Counselors and nurses |
| Office staff | Custodial and maintenance staff | Nutrition services staff |
| Bus drivers | Coaches | Administrative staff |
Verify your specific school through the Colorado Department of Education's SchoolView database, checking for "Public" under School Type.
Only one borrower needs to meet the requirement; a spouse or co-borrower can work in any field, and you do not have to be a first-time buyer.

No cost. No commitment. Just an honest answer about whether Schools to Home — or something better — fits your situation.
Eligibility comes from your employer, not a district boundary, which matters more for CSI employees than for any other Schools To Home group.
A CSI employee teaching in Grand Junction, working in a Denver charter school, or on staff at a CSI school in Colorado Springs qualifies under the same statewide rules, and can purchase in any Colorado community that meets the program's owner-occupancy and mortgage requirements.
Unlike a traditional school district employee whose program audience may be concentrated around one district boundary, CSI employees can use the program while shopping across Colorado, subject to the program's mortgage and owner-occupancy requirements.
The 25% figure applies to the first mortgage amount, not the purchase price.
| Purchase price | $400,000 |
| First mortgage | $320,000 |
| Maximum 25% second mortgage | $80,000 |
On a $400,000 home with a $320,000 first mortgage at 80% loan-to-value, the maximum second mortgage runs 25% of $320,000, or $80,000, which can cover the full down payment with no mortgage insurance.
A higher first-mortgage structure can raise the assistance amount, up to 97% LTV and 105% combined LTV, and requires mortgage insurance above 80% LTV. Ask a CHFA participating lender to price both structures for your specific city and price point.
The $1,000 figure people hear about is the minimum required borrower contribution — gift funds are allowed — not the total assistance amount.
Add closing costs, prepaids, and lender fees to get a full cash-to-close number before writing an offer.
| At Closing | Six Years Later |
|---|---|
| Purchase price: $400,000 | Sold for: $500,000 |
| First mortgage: $320,000 | Home gain: $100,000 |
| Schools To Home assistance: $80,000 | Shared appreciation, illustrative 20%: $20,000 |
| Second mortgage is repaid at sale | Total CHFA repayment: $100,000 |
This is an illustration only, not a projection of future home values in any particular Colorado market. Have a lender run the actual numbers for your city and purchase price.
| Statewide income limit | $178,920 |
| Minimum mid credit score | 620 |
| Income calculation | Qualifying income used by your lender for mortgage credit |
The income limit is $178,920 statewide, the same figure in every Colorado county regardless of household size, based on the qualifying income your lender uses for mortgage credit. The minimum mid credit score is 620, subject to the specific loan program's underwriting requirements.
Single-family homes, PUDs, condominiums, modular homes, and manufactured homes on a permanent foundation can all qualify, subject to Fannie Mae guidelines.
A typical duplex does not qualify, since the program covers one-unit, owner-occupied properties.
No Property Inspection Waiver is permitted; every purchase requires a full appraisal, which affects offer strategy in a competitive market such as Denver or Fort Collins.
A short hold may not build enough equity to make the shared-appreciation structure attractive.
Compare a conventional loan without shared appreciation before deciding.
The program requires the home to serve as your primary residence.
The shared-appreciation structure can include value created during your ownership.
Zero down does not create a cash cushion for a roof, furnace, foundation, or other unexpected repairs.
Schools To Home covers your down payment structure, but you still need a lender to originate the first mortgage.
Mike Oswald at Rate (NMLS 261003, Equal Housing Lender) works with Colorado school-district and charter-school buyers on CHFA financing statewide, and you are free to use any lender who participates in the program.
The Kenna Real Estate Group's Kenna Credit Care mortgage readiness program can get your credit and documentation ready before you apply.
Before making an offer, ask your lender to compare the Schools To Home structure with the conventional alternatives available for your credit profile, income, purchase price, and expected time in the home.
Work for a Colorado Charter School Institute school? We can help you understand the eligibility and homebuying numbers before you make an offer.
The Kenna Real Estate Group works with CSI employees buying in every corner of Colorado and tracks active listings and pending sales through REcolorado so you can shop with current local data wherever your CSI school is located.
Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree.
CSI is a statewide charter public school authorizer whose portfolio includes charter schools across Colorado.
Full-time employees of eligible CSI schools can qualify, subject to the program's employment and mortgage requirements. Verify your specific school through CDE SchoolView.
Yes. CSI employees can purchase in any Colorado community that meets the program's owner-occupancy and mortgage requirements.
The deferred second mortgage can be worth up to 25% of the first mortgage amount, subject to program and underwriting requirements.
No. It is a deferred second mortgage that is repaid when a repayment event occurs, along with the applicable shared-appreciation amount.
No. Eligibility is based on qualifying full-time employment with an eligible public school employer, not simply on having a teaching job title.
The article's current statewide income limit is $178,920.
The minimum mid credit score stated in this guide is 620, subject to the specific loan program's underwriting requirements.
Have questions about your school, eligibility, financing, or buying anywhere in Colorado? Send us your questions.
|
First Name
|
Last Name
|
|
Email
|
|
|
Phone (optional)
|
|
|
Message
Enter your questions/comments here |
|
Consent: I agree to be contacted by The Kenna Real Estate Group via call, email, and text for real estate services. To opt out, you can reply 'stop' at any time or reply 'help' for assistance. You can also click the unsubscribe link in the emails. Message and data rates may apply. Message frequency may vary. For more information, please review our Privacy Policy.
Explore the district and statewide guides below to see how CHFA Schools To Home applies across Colorado.
| Colorado Schools To Home Hub
Every district and statewide guide in one place. |
Denver Public Schools | Douglas County |
| Aurora | Adams 12 | St. Vrain |
| Poudre | Boulder Valley | District 49 |
| Academy 20 | 27J | Greeley-Evans |
| Colorado Springs D11 | CSI Charter Schools To Home
This guide — statewide CSI eligibility and DPA. |
Thompson |
| Pueblo | Littleton | Harrison D2 |
| Widefield | Weld RE-4 | Fountain-Fort Carson |
| Westminster | BOCES & Small Districts
A broader guide for employees outside the major district pages. |
Jeffco |
| ← Return to the Colorado Schools To Home Hub | ||
Information in this guide is provided for educational purposes and is based on the program details referenced in the article. Program guidelines, underwriting requirements, income limits, loan limits, and eligible-property rules can change. Confirm current requirements with a CHFA participating lender before relying on the information for a purchase decision.
Questions about any home in Colorado? Call or text 303-955-4220. A live person answers.
A statewide charter public school authorizer overseeing charter schools across Colorado, from Denver and Aurora to Grand Junction and Steamboat Springs, rather than one city-bound district.
Yes, if the specific school is an eligible institute charter school and the employee is classified full time. A CHFA participating lender verifies the employer and status.
Yes. Eligibility comes from your employer, not a district boundary, so you can purchase in any Colorado community that meets the program's owner-occupancy and mortgage requirements.
Up to 25% of your first mortgage amount, subject to CHFA guidelines and underwriting. On a $320,000 first mortgage, that's up to $80,000.
No. It's a deferred second mortgage with a shared-appreciation obligation, repaid at sale, refinance, or when the home stops being your primary residence.
No. Eligibility is based on full-time employment with an eligible public-school employer, not job title.
$178,920 statewide, the same figure in every Colorado county regardless of household size.
A minimum mid credit score of 620, subject to the specific loan program's underwriting requirements.