New - 1 Hour Ago
$299,900
Active
4
Beds
2
Baths
1586
Sqft
0.1607
Acres
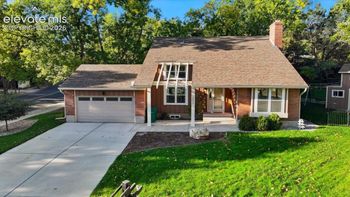
1287 Cree Dr, Colorado Springs, CO 80915
MLS#: 6901904


Full-time District 49 employees can buy a home in Falcon, Peyton, or eastern Colorado Springs with close to nothing down using CHFA Schools To Home — a 30-year fixed first mortgage paired with a deferred second mortgage worth up to 25% of that first mortgage, with no monthly payment on the second.
Schools To Home was created by 2025 Colorado legislation and is funded through the Public School Permanent Fund, administered by the Colorado Housing and Finance Authority (CHFA). District 49 — also known as Falcon School District 49 — serves a large and growing stretch of El Paso County. For a paraprofessional, bus driver, custodian, or first-year teacher, saving a traditional down payment while renting in a fast-growing market can take years. Schools To Home is built to close that gap.
Eligible employers include District 49 district-run campuses, D49-authorized charter and institute charter programs, eligible BOCES serving El Paso County public schools, and innovation zone campuses. CHFA verifies each employer through the Colorado Department of Education's SchoolView database, and the employer has to carry a public designation there. Private and religious-school employees are not eligible.
Job title does not matter. Full-time status with an eligible D49 employer is what CHFA checks.
District 49's service area sits close to Peterson Space Force Base and Schriever Space Force Base, and within commuting distance of Fort Carson, which creates real overlap between the D49 employee population and military households. Only one borrower on the loan has to be the eligible full-time D49 employee — the other can hold VA loan eligibility from active duty or veteran status. Combining a VA-eligible first mortgage with the CHFA second mortgage is possible in some cases, but the specifics need confirming directly with a participating lender, since not every lender structures that pairing the same way. A household expecting a PCS move within a few years should weigh that timing carefully: a short ownership period does not leave enough time to build equity before the CHFA obligation comes due.
The assistance amount is up to 25% of the first mortgage, not the purchase price. Two loan limits shape the structure: a maximum 97% loan-to-value on the first mortgage, and a maximum 105% combined loan-to-value once the second mortgage is layered in.
| Structure | Purchase price | First mortgage | Assistance | PMI |
|---|---|---|---|---|
| Structure A | $475,000 | $380,000 (80% LTV) | $95,000 | None |
| Structure B | $475,000 | $399,000 (84% LTV) | $99,750 | Required |
A CHFA-participating lender should price both structures side by side. The PMI premium against the extra assistance runs differently depending on credit score and how long the buyer plans to stay in the home.
No. It is a second mortgage with a real repayment obligation, not a grant. What it changes is timing: it turns years of saving into a purchase this year, at a cost calculated up front and compared against the alternative.
$178,920, statewide, regardless of county or household size. The income counted is the qualifying income the lender uses to credit-approve the loan, not a separate household calculation.
No separate Schools To Home purchase-price limit applies. There is still a maximum first-mortgage amount — the lesser of $832,750 or the applicable Fannie Mae conforming limit plus financed mortgage insurance — but that is a loan-amount ceiling, not a cap on the home's price. A qualifying D49 employee can compare new-construction Falcon against established eastern Colorado Springs neighborhoods rather than assuming one option is out of reach.
The first mortgage is capped at the lesser of $832,750 or the applicable Fannie Mae conforming limit plus financed mortgage insurance. In El Paso County, that ceiling sits well above what most D49 households will be borrowing.
CHFA divides the assistance amount by the original purchase price to lock in a fixed shared appreciation percentage at closing. Appreciation itself is measured as sale price minus original purchase price — not down payment, not renovation spend, not agent commission.
Worked example: a full-time District 49 employee buys a home in Falcon for $475,000 using Structure A: $380,000 first mortgage, $95,000 in assistance, a locked 20% shared appreciation rate, and a minimum $1,000 contribution at closing. Seven years later, at roughly 3.8% annual appreciation — a reasonable Front Range assumption — the home sells for $605,000. Appreciation is $130,000; the shared appreciation payment is 20% of that, or $26,000; the total owed to CHFA is $121,000 ($95,000 assistance plus $26,000 appreciation share), against a remaining first-mortgage balance near $330,000.
Negative appreciation is treated as zero. The buyer still owes the assistance back in full, but never owes a share of a decline.
Four triggers: selling, refinancing the first mortgage, paying it off, or the home no longer being the owner's primary residence. Move out and rent the house, and the whole balance accelerates — this program is not built for a rental portfolio, and it is not designed for a household planning to convert the home into a rental during a future PCS.
Yes, but a refinance triggers repayment of both the assistance and the shared appreciation amount. Have a lender model the future CHFA payoff against the refinance before committing to a rate lock.
That is not disqualifying. Only one borrower on the loan has to be the eligible school employee. A spouse or partner in any other field — including active-duty military, common in the Fort Carson and Space Force base area — can still be a co-borrower, which lets many households qualify on combined income.
A typical duplex does not qualify — the program is structured around one-unit, owner-occupied properties. The home must be owner-occupied as a primary residence, and a full appraisal is required.
Browse current inventory at Explore Colorado Springs and Explore Monument, or search every county at once at homes for sale in Colorado.
Falcon's newer master-planned communities frequently sit inside metro districts that finance roads, parks, and infrastructure, which can push property taxes above what an older Colorado Springs neighborhood carries; many of those subdivisions also carry HOA dues, so price the full monthly payment rather than just principal and interest. Some Peyton-area properties rely on well and septic systems instead of municipal utilities, so have those inspected separately and budget for maintenance and eventual replacement. Because Schools To Home requires a full appraisal with no waiver option, build the offer timeline around that reality in a competitive Falcon or eastern Colorado Springs market.
Financing questions on Schools To Home, and on El Paso County mortgages of any kind, are a good fit for Mike Oswald at Rate (NMLS 261003, Equal Housing Lender). You are free to use any lender. Start at the Colorado home financing guide or check readiness first at Kenna Credit Care mortgage readiness. Ask for the printable Schools To Home closing-cost checklist in the form below and we email it the same day.
The Kenna Real Estate Group works with District 49 staff on Schools To Home purchases across Falcon, Peyton, and eastern Colorado Springs — comparing loan structures, weighing VA financing for military-connected households, and timing offers around the required appraisal. Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree. Or start now and search every home for sale in Colorado.
Questions about any home in Colorado? Call or text 303-955-4220. A live person answers.
Up to 25% of the first mortgage amount. On a $475,000 Falcon home, that runs $95,000 to $99,750 depending on the loan structure, not 25% of the purchase price.
No. Schools To Home does not require first-time buyer status. Any full-time employee of an eligible District 49 public school employer can apply.
No. It is a deferred second mortgage that comes due when the home sells, the first mortgage is refinanced or paid off, or the home stops being the owner's primary residence, along with a locked share of the home's appreciation.
$178,920 statewide, the same number used in every Colorado county regardless of household size.
Yes. Only one borrower has to be the District 49 employee. A spouse working at Fort Carson, Peterson Space Force Base, or Schriever Space Force Base, or serving on active duty, adds income to the file as a co-borrower.
No. The constraint is on the loan amount, capped at the lesser of $832,750 or the applicable Fannie Mae conforming limit plus financed mortgage insurance, not on the price of the house.
That converts the home away from a primary residence, which triggers immediate repayment of the assistance and the shared appreciation amount.
A minimum middle credit score of 620, with maximum debt-to-income of 50% at 620-659 and 55% at 660 and above.