New - 4 Days Ago


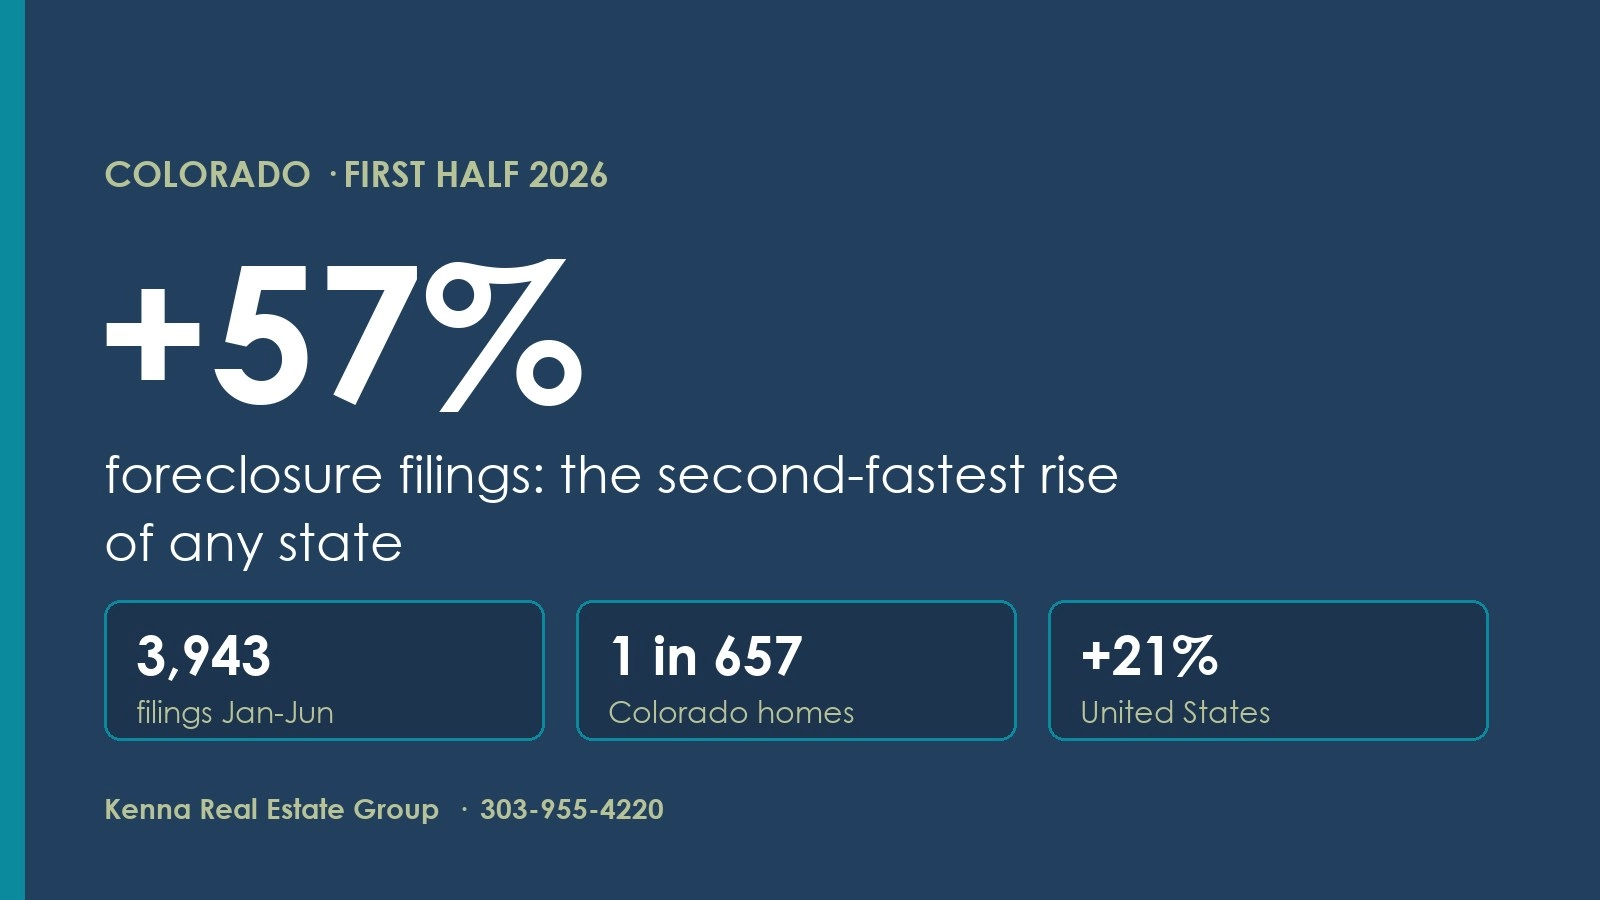
Are foreclosures rising in Colorado? Yes: Colorado foreclosure filings rose 57% in the first half of 2026, the second-fastest increase of any state. ATTOM counted 3,943 Colorado filings from January through June, one for every 657 homes. This week a bank took back an apartment building in Aurora at a foreclosure auction, and four apartment complexes in Greeley face an $18 million foreclosure. If you want to buy a foreclosure in Colorado, a bank-owned home or a HUD home, here is how it works and what to watch for.
Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree.
3,943 Colorado foreclosure filings January to June 2026 | +57% Change from a year earlier Second-fastest rise of any state |
1 in 657 Colorado homes with a filing National rate: 1 in 625 | +21% U.S. filings, first half 227,548 filings nationwide |
Change in foreclosure filings, first half of 2026 vs 2025 (states with 500+ filings)
A filing counts every step: the default notice, the auction notice and the bank taking the home back. More filings today means more bank-owned homes on the market over the next 6 to 12 months, because the Colorado process runs through the county public trustee and the sale date lands months after the first notice.
| Type | Who sells it | How you buy | The catch |
|---|---|---|---|
| Bank-owned (REO) | The lender, after the auction | Through the MLS with a buyer agent, like any listing | Sold as-is; the bank adds its own addendum and answers slowly |
| HUD home | HUD, after an FHA loan foreclosure | Online bid through a HUD-registered agent | Owner-occupants bid first; sold as-is |
| Short sale | The owner, with the lender approving | Through the MLS; the lender signs off on the price | Approval takes 30 to 120 days |
| Public trustee auction | The county public trustee | Certified funds at the auction | No inspection, no access inside, cash only |
What to watch out for
Call your lender before the first notice is recorded. A loan modification, a forbearance plan or a short sale in Colorado stops a foreclosure when you act early. If you have equity, selling before the auction keeps it in your pocket: start with a home value report or an instant offer to compare.
More reading: Colorado housing inventory is piling up, rent or buy in Colorado at 7% rates, this week's Colorado mortgage rates and can I afford a home now?




Yes. Colorado had 3,943 foreclosure filings in the first half of 2026, up 57% from a year earlier, the second-fastest increase of any state with at least 500 filings.
Most buyers buy a bank-owned (REO) home through the MLS with a buyer agent: pre-approval or proof of funds, an offer on the state contract plus the bank addendum, a full inspection, and a loan that fits the condition.
They are priced to sell, but as-is. Compare the price with the last 90 days of sales nearby, then subtract the repairs the inspection finds. That number is the real discount.
Yes, when the home meets FHA condition rules. Missing appliances, peeling paint or hazards like loose railings fail the appraisal, and a renovation loan or a conventional loan covers rougher homes.
In a foreclosure the lender already owns the home and sells it. In a short sale the owner still owns it and sells for less than the loan, with the lender approving the price.
Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree.
Brian Lee Burke, the hardest working man in real estate
Kenna Real Estate Group at Keller Williams DTC. Helping You With Your Pad™ since 2002.