New - 11 Hours Ago
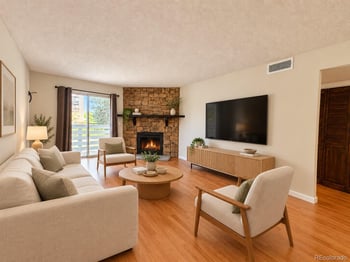
$160,000
Active
1
Beds
1
Baths
701
Sqft
--
Acres
8555 Fairmount Dr #C104, Denver, CO 80247
MLS#: REC4913201


A loan origination fee pays the lender for processing, underwriting and funding your mortgage, and on a Colorado loan it runs 0.5% to 1% of the loan amount as a rule — $2,500 to $5,000 on a $500,000 loan. It is one line on a page full of closing costs, and it is one of the few lines you can actually shop and negotiate before you lock a rate.
It is a charge from the lender for the work of taking your application, verifying your documents, underwriting the file, and preparing the loan for closing. It is separate from third-party costs like the appraisal, title insurance, and recording fees, which pay other companies, not the lender.
Most Front Range lenders charge somewhere between 0.5% and 1% of the loan amount, though some quote a flat dollar fee instead of a percentage. On a $450,000 loan, that is roughly $2,250 to $4,500. Some lenders build a portion of this cost into the interest rate instead of charging it directly — which is exactly why comparing the rate alone never tells the full story.
An origination fee pays for processing the loan; a discount point is a separate, optional charge you pay upfront to buy your interest rate down, costing 1% of the loan amount per point as a rule and lowering the rate by a fraction of a percent. Both appear on the same fee page, and it is easy to mistake one for the other — ask your loan officer to point to each line separately.
The interest rate is what your monthly payment is based on; the APR folds the origination fee and most other lender charges into a single yearly cost figure, which is why the APR on a Loan Estimate is almost always higher than the quoted rate. Comparing APR, not just rate, is the fastest way to see which lender's total cost is actually lower.
Yes. Origination fees are one of the more negotiable line items on a Colorado Loan Estimate, especially if you are comparing offers from more than one lender and can show a competing quote. Asking is free, and lenders competing for Front Range purchase business will adjust the fee, offer a lender credit, or waive part of it to win the loan, in many cases.
Ask for an itemized breakdown rather than accepting a single bundled "lender fee" line, so you know exactly what you are being charged for.
CHFA-funded loans and CHFA down payment assistance programs carry their own fee structure on top of standard lender origination costs, since a second loan or grant layer is being administered alongside the first mortgage. FHA and VA loans allow origination fees within program limits — VA loans in particular cap total lender fees more tightly than conventional loans, and VA loans add a separate funding fee that is not the same thing as an origination fee.
| Loan type | Typical origination-related cost |
|---|---|
| Conventional | 0.5% to 1% of loan amount, negotiable |
| FHA | Similar range, plus upfront and ongoing mortgage insurance |
| VA | Lender fees capped by VA rules, plus a separate VA funding fee |
| CHFA | Standard lender fee plus program-specific administration cost |
Locking your rate for a longer period, common on new construction or a longer Front Range closing timeline, sometimes carries its own fee or a slightly higher rate, separate from origination. Ask specifically whether your quoted origination fee assumes a standard 30 to 45 day lock or a longer one before you compare it against another lender's quote.
The Loan Estimate, provided within three business days of application, shows projected fees including origination; the Closing Disclosure, provided at least three business days before closing, shows the actual final numbers. Federal rules limit how much certain fees, including origination charges from the same lender, can increase between the two documents — compare them side by side and ask about any jump.
Get a Loan Estimate from at least two or three lenders on the same day, since rates move daily, and compare the origination fee, the APR, and the total estimated closing costs together rather than any single number alone. Mike Oswald at Rate (NMLS 261003, Equal Housing Lender) can walk through a Loan Estimate line by line so you know what is negotiable before you lock — you are free to use any lender.
A Front Range closing adds Colorado-specific costs beyond the lender's origination fee: title insurance, recording fees, a survey if required, and property tax proration at closing. See the Closing Costs for Colorado Home Buyers guide for the full list and typical ranges.
Yes, a refinance is underwritten as a new loan, so it carries its own origination fee, in the same 0.5% to 1% range as a rule. Weigh that cost against the monthly savings from a lower rate to find your break-even point before refinancing; see the Should You Refinance Your Colorado Mortgage? guide for that math.
A lender credit reduces your closing costs, including the effect of the origination fee, in exchange for accepting a slightly higher interest rate. It is a useful tool for a buyer short on cash at closing, at the cost of a higher monthly payment and more total interest over time — run both scenarios before choosing.
Question an origination fee that runs meaningfully above 1% of the loan amount, or one that is bundled into a vague single line with no itemization, especially if a competing Colorado lender quoted you lower. A legitimate lender will explain every fee on the Loan Estimate in plain terms without hesitation.
Ask your loan officer to circle three numbers before you sign anything: the origination fee in dollars, the APR, and the total estimated cash needed at closing. Those three numbers, compared across two or three Colorado lenders on the same day, tell you more than any single rate quote by itself, and they are the numbers that actually change your bottom line at the closing table.
Ask for the printable Colorado closing-cost checklist in the form below and we email it the same day, so you can compare lender quotes apples to apples before you lock a rate. Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree. Ready to start looking? Search every home for sale in Colorado.
Questions about any home in Colorado? Call or text 303-955-4220. A live person answers.
No, some lenders advertise no origination fee and instead build the cost into a slightly higher interest rate; compare the APR and total cost, not just whether a fee line exists.
On most loan types, yes, closing costs including the origination fee are commonly financed into the loan or covered by a lender credit rather than paid in cash at closing, which raises the loan balance and monthly payment slightly.
No, a higher fee does not indicate better service. Compare the itemized fee against competing Colorado lender quotes and ask what specifically the fee covers.
Yes, if your purchase contract includes a seller concession toward closing costs, it applies to lender fees including origination, up to loan-program limits.
It depends on the lender's policy and whether the loan fell through due to the borrower, the property, or the lender; ask specifically about refund policy before paying any upfront fee.
Multiple mortgage inquiries within a short shopping window, 14 to 45 days depending on the scoring model, are counted as a single inquiry for credit scoring purposes in most cases.
Points paid to reduce your rate are deductible under certain conditions in some cases; a general origination fee is not treated the same way, as a rule. Confirm your specific situation with a CPA.