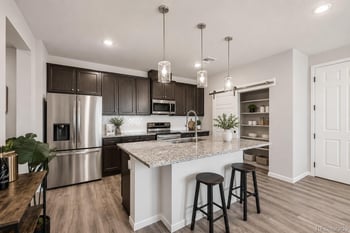
$1,100,000
Active Under Contract
11
Beds
5
Baths
4474
Sqft
0.18
Acres
2705 E Evans Ave, Denver, CO 80210
MLS#: REC4754996


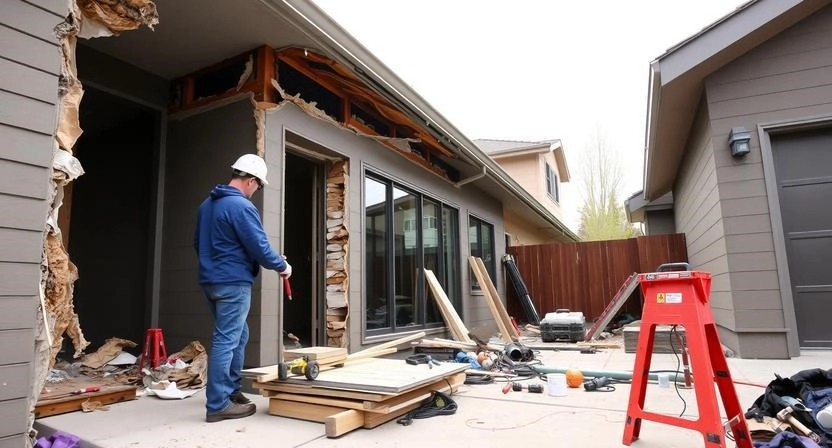
The repair bill after hail, a burst pipe, or wildfire smoke damage almost never matches the number a homeowner has in their head walking in. Between deductibles, contractors who chase storm damage door to door, and gaps between what a policy covers and what a repair actually costs, Front Range homeowners lose money in the space between the estimate and the invoice more than in the repair itself.
Code-upgrade costs, matching materials for a partial repair, and temporary living expenses during a larger job are the three hidden costs that surprise homeowners most. A roof repair that requires bringing the whole roof up to current code, not just patching the damaged section, is a common one after a Front Range hailstorm.
Contractors who follow storm paths door-to-door push a homeowner to sign an insurance-claim assignment on the spot, before a second bid or an adjuster visit, which hands the contractor direct control over the claim payout. Get at least one independent bid and confirm the contractor is licensed and insured in Colorado before signing anything tied to your claim.
Most Colorado policies carry a separate, higher percentage-based deductible for wind and hail damage instead of the flat dollar deductible that applies to other claims, and that percentage is based on the home's insured value, not the repair cost. Read the declarations page for the wind/hail deductible specifically; it's commonly the single biggest gap between what a homeowner expects and what the policy actually pays.
It depends on whether the policy pays replacement cost or actual cash value for roof claims; some Colorado insurers pay older roofs at actual cash value only, which factors in depreciation and pays less than the cost to replace. Check this specific roof provision before hail season each year, not after a storm.
A public adjuster works for the homeowner, not the insurance company, and negotiates the claim on your behalf for a percentage of the payout. Directories like public insurance adjuster near me show what these listings look like nationally; Colorado has its own state-licensed public adjusters, and hiring one makes the most sense on a large, disputed, or denied claim rather than a routine repair.
Get a written, itemized estimate broken down by material and labor, not a single lump-sum number, and compare it against at least one other bid. Courses like the repair estimates training offered through the University of Oklahoma's professional programs teach the line-item approach that separates a fair estimate from an inflated one.
The Colorado Division of Insurance handles consumer complaints against insurers operating in the state and publishes guidance on the claims process, including timelines an insurer must follow after you file. File a complaint with the division if an insurer misses its own response deadlines or denies a claim without a clear reason.
A frozen pipe burst counts as sudden accidental water damage under most Colorado policies, but an insurer can deny the claim if the home sat unheated and unattended, since that shifts the cause toward neglect rather than a sudden event. Keep the heat set to at least 55 degrees when you're away in winter, and know that this single habit protects both the plumbing and the claim.
Smoke and ash damage assessment checks HVAC systems, insulation, and porous surfaces like carpet and drywall, since smoke odor and fine ash particles travel further into a home than visible soot suggests. Colorado's wildfire smoke season overlaps with hail season for several months a year, and an insurer can send separate adjusters for each type of damage on the same claim.
Yes, always. A second bid protects against both an underpriced insurer-preferred contractor cutting corners and an overpriced storm-chaser padding the invoice. Two to three bids gives a realistic price range for the same scope of work.
A cash-out refinance or a home equity line covers the gap between an insurance payout and the actual repair cost on a larger job like a full roof or foundation repair. Mike Oswald at Rate (NMLS 261003, Equal Housing Lender) walks Front Range homeowners through financing options for exactly this gap, and you are free to use any lender for this kind of financing. See our financing overview and Kenna Credit Care mortgage-readiness resources.
| Repair type | Typical Front Range cost range |
|---|---|
| Roof replacement (asphalt shingle) | $9,000-$18,000 |
| Frozen pipe repair (single line) | $300-$2,000 |
| Smoke/ash interior cleaning | $1,500-$6,000+ depending on scope |
| Gutter and downspout repair after hail | $500-$3,000 |
Yes. An unpermitted structural, electrical, or plumbing repair can hold up a sale when it surfaces during inspection or appraisal, since a lender can require it be permitted and re-inspected before closing. Pull the permit before starting any repair that a city or county requires one for, even a rushed post-storm job.
Read exactly what authority the assignment gives the contractor over your claim, whether it locks you into that contractor regardless of the adjuster's findings, and whether you can cancel within a set window. Ask your agent or the Colorado Division of Insurance before signing if any of it feels rushed.
A home equity line of credit keeps your existing mortgage rate in place and draws only what you need for the repair, which fits a phased project like a partial roof or basement repair. A cash-out refinance replaces the whole mortgage at a new rate and gives one lump sum upfront, which fits a single large invoice like a full foundation stabilization. Mike Oswald at Rate walks Front Range homeowners through both options side by side.
Sorting out a repair bill against an insurance payout before you sell, or wondering what a past claim means for your next purchase? The Kenna Real Estate Group has seen these claims play out across the Front Range and can point you to the right resource. Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree. Search every home for sale in Colorado.
Questions about any home in Colorado? Call or text 303-955-4220. A live person answers.
Colorado policies commonly carry a separate, higher percentage-based wind/hail deductible, and older roofs get paid at actual cash value instead of full replacement cost, both of which widen the gap between payout and repair bill.
Never sign an insurance-claim assignment on the spot. Get at least one independent, itemized bid and confirm Colorado licensing and insurance before signing anything tied to your claim.
A public adjuster works for the homeowner, not the insurer, and negotiates the claim for a percentage of the payout. It's worth hiring on a large, disputed, or denied claim rather than a routine repair.
In most cases, yes, as sudden accidental damage, but an insurer can deny the claim if the home sat unheated and unattended. Keep the heat at 55 degrees or higher when you're away in winter.
A cash-out refinance or home equity line covers the gap on a larger repair. Mike Oswald at Rate walks Front Range homeowners through the options, and you're free to use any lender.
Yes. It can hold up closing if it surfaces during inspection or appraisal, since a lender can require the work be permitted and re-inspected first.
Yes, always get two to three bids for the same scope of work. It protects against both an underpriced insurer-preferred contractor and an overpriced storm-chaser.