Open: Sat 1:00 PM - 3:00 PM
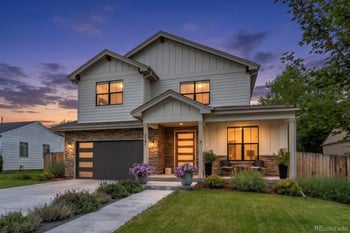
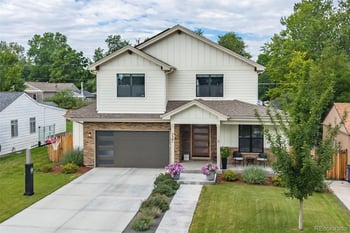
$1,500,000
Coming Soon
5
Beds
4
Baths
3857
Sqft
0.18
Acres
3341 S Fairfax St, Denver, CO 80222
MLS#: REC6269436


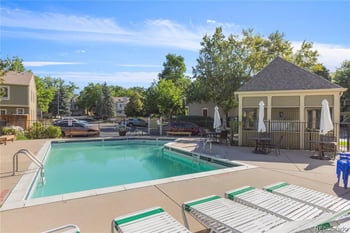
Financing an inground pool works best as part of a Front Range homeowner's longer property plan, not a stand-alone purchase, because Colorado's short pool season, clay soil construction costs and Denver metro permit requirements together change the payback math compared with a warmer, flatter-lot state. A homeowner planning to stay five or more years gets more value from pool financing than one planning to sell within a year or two of installation.
A home equity line of credit, a cash-out refinance, or a dedicated pool loan are the three most common ways Front Range homeowners fund an inground pool. A HELOC carries the lowest rate for homeowners with equity built up, while a dedicated pool loan closes faster but carries a higher rate. Mike Oswald at Rate, NMLS 261003, an Equal Housing Lender, walks Front Range homeowners through financing options and which one fits a specific equity position, and you are free to use any lender for the financing itself; the Kenna Credit Care mortgage readiness program is a good first stop before applying.
Excavating through Colorado's expansive clay soil, engineering the shell for freeze-thaw movement, and adding a required barrier fence pushes the total inground pool cost above what homeowners in warmer, sandier-soil states pay, into the six figures once decking and equipment are included.
Get a written, itemized quote that separates excavation, shell, decking, equipment and fencing rather than a single lump-sum number, so a lender and the homeowner both know exactly what the financed amount covers before construction starts.
Denver, Aurora, Lakewood, Littleton, Colorado Springs and Fort Collins all require a building permit and an inspected, self-latching barrier fence for an inground pool, and those costs belong in the loan amount from the start rather than as a surprise later. Confirm setback distances with your city or county before finalizing the loan and the layout together.
Many Front Range HOAs require architectural review before approving an inground pool, and a lender will not fund construction on an unapproved project. Getting HOA sign-off before closing on financing avoids paying interest on a loan for a pool that has not cleared covenant review.
Request the HOA's decision in writing and keep it with the loan file, since a verbal approval from a board member carries no weight if the covenant review is challenged after construction starts.
A Front Range pool season runs roughly four months, from around Memorial Day through mid-September, compared with six or more months in warmer states, which stretches the number of years it takes a financed pool to pay for itself in personal use value. Homeowners planning a longer hold benefit more from financing than those weighing a near-term sale.
A pool rarely returns its full installed cost at resale on the Front Range given the short season, but it widens the buyer pool in higher price brackets and on larger lots suited for outdoor living. A homeowner financing a pool purely for resale value should weigh that against lower-cost projects like landscaping and patios that return more per dollar spent.
A well-maintained, financed pool with clear documentation of permits and inspections removes a question mark for a buyer's lender and appraiser, which matters more to a smooth closing than the pool's effect on the final sale number.
Homeowners insurance premiums rise after adding an inground pool, and ongoing costs like winterization, chemical balancing and equipment maintenance add up over a Colorado season shorter than the one the pool budget was modeled on. Building these costs into the monthly budget alongside the loan payment avoids a surprise the first winter.
A homeowner weighing pool financing against other equity uses, such as a kitchen remodel or debt consolidation, should compare the personal-use value of each option against its effect on the home's future sale price, since a pool returns less of its cost at resale than most interior remodels on the Front Range. A financial plan that treats the pool as a lifestyle purchase funded by equity, rather than an investment expected to pay for itself, sets more realistic expectations from the start.
Interest on a home equity loan used for a substantial home improvement like a pool qualifies as deductible under current federal rules, subject to loan limits and itemizing requirements, so homeowners should keep records of how the loan proceeds were spent. A tax professional, not a lender or contractor, is the right source for how a specific pool project affects a specific tax return.
Once financing closes, permitting, HOA approval and excavation on the Front Range stretch the project from ground-breaking to a finished pool over three to six months, depending on the city's permit timeline and the contractor's schedule. Starting the loan and permit process in late winter positions a pool to be ready near the start of the short Colorado swim season instead of missing most of it.
A lender funding pool construction in stages, tied to inspection milestones, needs a contractor comfortable working with a draw schedule rather than expecting a lump-sum payment upfront. Confirming that a builder has completed financed projects on the Front Range before signing a contract avoids a mismatch between the loan's payment structure and the contractor's own billing practices partway through construction.
A homeowner who financed a pool with a higher-rate product during a tight-money period has the option to refinance into a lower rate later, either by rolling the pool loan into a full cash-out refinance or by refinancing the HELOC on its own once the home has built more equity. Watching the loan's rate against current market rates each year, rather than assuming the original terms are permanent, keeps the financing cost aligned with the property's actual equity position over time.
Closing costs on a refinance eat into the savings from a lower rate, so run the break-even math, how many months of payment savings it takes to cover the refinance cost, before restructuring pool financing that already has a few years of payments behind it.
The Kenna Real Estate Group helps Front Range homeowners weigh pool financing against other equity uses, and helps buyers judge whether an existing pool adds real value to the asking price. Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree. Or search every home for sale in Colorado to compare listings with and without a pool.
Questions about any home in Colorado? Call or text 303-955-4220. A live person answers.
A home equity line of credit carries the lowest rate for homeowners with built-up equity, while a dedicated pool loan closes faster but carries a higher rate. Compare both against a specific equity position before choosing.
Excavating through Colorado's expansive clay soil, engineering for freeze-thaw movement, and adding a required barrier fence pushes total inground pool cost into the six figures once decking and equipment are included.
Most Front Range HOAs require architectural review before approving an inground pool, and a lender will not fund construction on a project that has not cleared that review.
Rarely in full. Colorado's roughly four-month pool season stretches the payback period compared with warmer states, though a pool does widen the buyer pool in higher price brackets.
Denver, Aurora, Lakewood, Littleton, Colorado Springs and Fort Collins all require a building permit and an inspected, self-latching barrier fence, and those costs should be included in the loan amount from the start.
Yes, premiums rise after an inground pool is added, and that ongoing cost should be budgeted alongside the loan payment rather than treated as a one-time expense.