New - Just Now
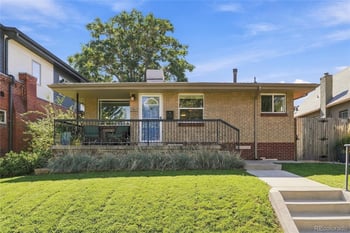
$900,000
Coming Soon
4
Beds
2
Baths
2116
Sqft
0.12
Acres
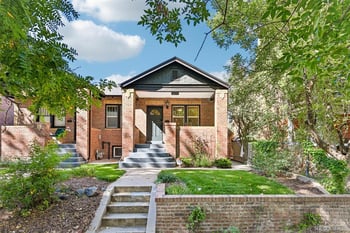
3484 W 33rd Ave, Denver, CO 80211
MLS#: REC4869595


A self-directed IRA lets a Colorado investor buy a rental house, a duplex, or raw land inside a retirement account and defer — or with a Roth structure, permanently avoid — tax on the rent and the eventual sale. The property titles in the name of the IRA, not the investor, and every dollar in and out has to move through the account.
That structure is the entire appeal and the entire risk: the tax benefit is real, and the rules that protect it are strict enough that one wrong payment can disqualify the whole account. Here is how the tax side works for a Front Range investor and where the rules bite.
A self-directed IRA (SDIRA) is a Traditional or Roth IRA held by a specialty custodian that permits real estate, private notes, and other assets a standard brokerage IRA will not hold. A custodian such as uDirect IRA handles the paperwork and files the annual account report, but does not pick the property or manage it — the account holder directs every purchase, so due diligence on a Denver metro duplex or a piece of Weld County land still falls entirely on the investor.
Rent collected by the IRA is not taxed the year it lands. In a Traditional SDIRA, tax is deferred until the account holder takes a distribution in retirement. In a Roth SDIRA, contributions are already after-tax, so qualified withdrawals in retirement — including years of accumulated rent and appreciation — come out with no further tax at all. On a Colorado rental cash-flowing $500 a month, that is $6,000 a year compounding inside the account instead of shrinking by an income tax bill first.
Unrelated Business Income Tax applies when the IRA uses debt to buy the property. A non-recourse loan financing part of a purchase makes the debt-financed share of the income subject to UBIT, filed on IRS Form 990-T. A property bought entirely with cash inside the IRA owes no UBIT on its rental income. This single rule decides whether many investors buy with cash inside the account or finance the deal outside it.
Only a non-recourse loan — the account holder carries no personal repayment obligation on it, and the lender's only recourse on default is the property itself. Far fewer lenders write these than standard Colorado mortgages, rates run higher, and down payments of 35% to 50% are common. For financing outside the IRA on a personal Colorado purchase, Mike Oswald at Rate (NMLS 261003, Equal Housing Lender) walks buyers through standard loan options — you are free to use any lender.
The IRS bars "self-dealing": the account holder or close family cannot live in the property, rent it, sell it to the IRA, buy it from the IRA, or perform repairs on it personally. Even mowing the lawn on an IRA-owned Colorado rental yourself is a prohibited transaction. A discovered violation disqualifies the entire IRA, taxing the full balance as a distribution in that year — not just the property. Every repair, every property tax payment, and every contractor invoice on the Colorado home has to be paid from IRA funds by a third party the custodian directs, never from the account holder's own pocket.
Every expense — county property tax, HOA dues, insurance, a new roof after a hailstorm — is paid from cash sitting in the IRA, requested through the custodian. If the account runs short of cash for a large repair, the options are limited: bring in a co-investor at the IRA level, take a non-recourse loan, or sell the property. The account holder cannot loan the IRA money directly.
| Detail | Traditional SDIRA | Roth SDIRA |
|---|---|---|
| Tax on rental income | Deferred until distribution | Tax-free at qualified withdrawal |
| Tax on sale gain | Deferred until distribution | Tax-free at qualified withdrawal |
| Contributions | Pre-tax (commonly deductible) | After-tax |
| UBIT if financed with debt | Applies to debt-financed share | Applies to debt-financed share |
Custodians charge an annual account fee plus a transaction fee for each purchase, sale, or bill paid on the investor's behalf. Fees vary by custodian and account size, so an investor comparing a $150,000 Colorado rental purchase against custodian pricing should ask for the full fee schedule before funding the account, not just the headline annual number.
Yes to both, with caveats. Raw land in Weld County or Elbert County held inside an SDIRA still needs property tax paid from the account and cannot be used personally — no weekend camping trips on IRA-owned land. A short-term rental inside an SDIRA has to follow the host city's short-term rental license rules the same as any other owner; see the Denver short-term rental eligibility guide before assuming a property will cash-flow as a nightly rental.
A solo 401(k), available to a self-employed investor with no full-time employees, allows a personal loan from the account and a higher contribution limit, and it is exempt from UBIT on debt-financed real estate in most cases — a meaningful edge over an SDIRA for an investor planning to finance a Front Range rental. An SDIRA remains the simpler option for someone who already has IRA funds parked in stocks and wants to redirect part of that balance into a Colorado property with cash, no financing involved.
Finding a Colorado property that pencils out for an IRA-owned purchase — the right price, the right rent, the right county tax load — is where a local agent earns the call. Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree. Start browsing now: search every home for sale in Colorado.
Questions about any home in Colorado? Call or text 303-955-4220. A live person answers.
No, not while the income stays inside the IRA. Tax is deferred (Traditional) or eliminated on qualified withdrawal (Roth), at both the federal and Colorado state level.
No. A spouse is a disqualified person under IRS rules, along with the account holder's parents, children, and any business the account holder controls.
Enough to cover the full purchase price if buying with cash, plus a reserve for property tax, HOA dues, and repairs, since the IRA cannot borrow from the account holder to cover a shortfall.
Yes, through a Roth conversion, which is a taxable event in the conversion year. Run the numbers with a tax professional before moving IRA-held cash into a Colorado property purchase.
It can, but frequent buying and selling inside an IRA risks being treated as a trade or business subject to UBIT; a buy-and-hold rental avoids that exposure more cleanly.
It passes to the named IRA beneficiary under the same rules as the rest of the account, not through a will, so beneficiary designations need to stay current.
Yes, as tenants in common with ownership split proportional to each IRA's contribution, with every expense and rental income split the same way.
Not required, but some investors set up an IRA-owned LLC (a 'checkbook IRA') to pay routine bills faster without routing each invoice through the custodian first.