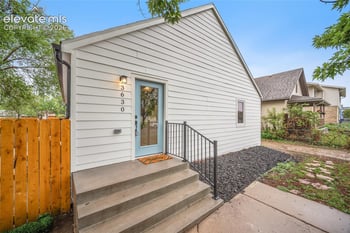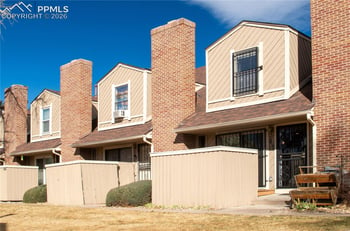
$345,000
Pending
3
Beds
2
Baths
1538
Sqft
0.0202
Acres
3300 W Florida Ave #48, Denver, CO 80219
MLS#: 9397860


Refinancing makes sense in Colorado when the new loan clears its closing costs within a timeframe shorter than you plan to stay in the home, whether the goal is a lower rate, a shorter term, or cash from your equity. Front Range home values have risen enough over the past several years that many owners now have more refinance options than they did at purchase.
Refinancing is worth exploring any time market rates drop below your current rate, your credit score has improved significantly since you closed, or you need to convert home equity into cash. Run your specific numbers rather than relying on a headline rate, since your break-even point depends on your loan balance, remaining term and Colorado closing costs.
A common starting benchmark is a rate reduction of at least half a percentage point, though the real test is your break-even month: divide total closing costs by your monthly savings. On a $400,000 Denver metro loan, a 0.5% rate cut saves roughly $115 to $130 a month, so $6,000 in closing costs breaks even in about 45 to 52 months.
Shortening your term to 15 years commonly comes with a lower rate and builds equity much faster, but the monthly payment rises because you are paying off the balance in half the time. Run the new payment against your full monthly budget, including Colorado property tax and homeowners insurance, before committing to the higher payment.
An ARM's initial low rate can increase at each adjustment period once the fixed portion ends. Refinancing into a fixed-rate loan locks in your payment for the life of the loan, which protects you from a rate jump if you plan to stay in your Colorado home beyond the ARM's fixed period. If you expect to sell before the ARM adjusts, staying put can still be the cheaper choice.
A cash-out refinance replaces your current mortgage with a larger loan and pays you the difference in cash, commonly used for renovations, debt consolidation or funding a second property purchase. It carries higher closing costs and a larger loan balance than a straight rate-and-term refinance, so compare it against a home equity loan or HELOC before deciding which one costs less over your expected timeline.
Most lenders want your loan-to-value ratio at 80% or lower for the best pricing on a conventional refinance, meaning your loan balance divided by your home's appraised value. Front Range appreciation over recent years has pushed many owners well under that threshold, which opens up better rate tiers and can eliminate private mortgage insurance.
Lenders re-underwrite a refinance the same way they underwrote your purchase loan, pulling a fresh credit report and appraisal. A higher score since your last mortgage can move you into a better pricing tier, while missed payments or new debt can push your rate up or affect approval, so check your credit report before applying.
Plan on 2% to 4% of the loan amount for a Colorado refinance, covering the appraisal, title insurance, recording fees and lender charges. Some lenders offer a no-closing-cost refinance that folds the fees into a slightly higher rate instead of cash at closing, which can make sense if you plan to refinance again or sell within a few years.
Loan-to-value is your loan amount divided by your home's appraised value, expressed as a percentage. A lower loan-to-value ratio commonly earns better pricing and can eliminate mortgage insurance requirements, which is one reason a fresh appraisal on an appreciated Front Range home can improve your refinance terms beyond what the rate alone suggests.
Points are an upfront fee paid to lower your rate, commonly 1% of the loan amount per point for roughly a 0.25% rate reduction. Points make sense when you plan to stay in the home long enough for the monthly savings to exceed the upfront cost; run both the with-points and without-points scenarios through the break-even math before deciding.
Expect 30 to 45 days from application to closing for most conventional refinances, depending on appraisal scheduling and how quickly you supply documentation. A streamlined refinance program, where available for your loan type, can close faster since it can skip a full appraisal.
Yes, as long as HOA dues and any metro district assessments are current. Your lender will request an HOA or metro district statement confirming no past-due balances before closing, so resolve any outstanding fees early to avoid a delay.
Mortgage interest on a refinance is deductible in most cases up to the IRS's combined mortgage debt limit when you itemize, and cash-out proceeds used for anything other than buying, building or substantially improving the home do not qualify for the deduction on that portion. Confirm your specific situation with a tax professional before filing.
The list mirrors a purchase loan: two years of tax returns or W-2s, 30 to 60 days of pay stubs, two months of bank statements, your current mortgage statement, and homeowners insurance information. Having these ready before you apply shortens the underwriting timeline.
Beyond the standard closing costs, check whether your county has reassessed property values since your last statement, since a refinance appraisal can trigger a fresh look at your tax escrow, and confirm your homeowners insurance premium if you are in a Front Range hail-prone county or a mapped wildfire zone, since either can change your total new payment more than the rate itself.
If your Front Range home no longer fits your space needs or you are relocating, run a current market valuation alongside your refinance numbers before committing to either path. Refinancing lowers your payment on the home you have; selling converts your equity into cash for a different Colorado property, and the better choice depends on your next move, not just the interest rate.
The Kenna Real Estate Group helps Front Range homeowners decide whether refinancing, selling or staying put fits their numbers best. For a rate quote, Mike Oswald at Rate (NMLS 261003, Equal Housing Lender) can run your specific scenario — you are free to use any lender. Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree. Curious what your home is worth instead? Search every home for sale in Colorado.
Questions about any home in Colorado? Call or text 303-955-4220. A live person answers.
When your rate drop, term change or cash-out need clears its closing costs within a timeframe shorter than you plan to stay in the home.
Plan on 2% to 4% of the loan amount for appraisal, title insurance, recording fees and lender charges.
Most lenders want 80% or lower for the best conventional pricing, and Front Range appreciation has pushed many owners below that threshold.
It can be, for renovations or debt consolidation, but compare its closing costs and larger loan balance against a home equity loan or HELOC first.
Expect 30 to 45 days from application to closing for most conventional refinances, depending on the appraisal and documentation.
Yes, as long as dues and assessments are current; your lender will request a statement confirming no past-due balances.
Only if you plan to stay long enough for the monthly savings to exceed the upfront cost, roughly 1% of the loan per point for about a 0.25% rate reduction.
In most cases, yes, up to the IRS combined mortgage debt limit when you itemize; cash-out funds used for anything other than the home do not qualify. Confirm with a tax professional.