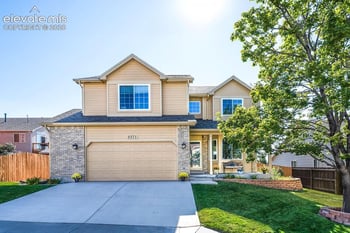
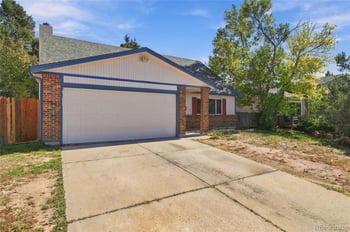
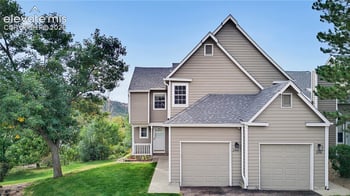
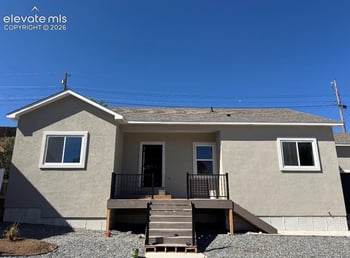
New - 2 Hours Ago
$435,000
Active
4
Beds
4
Baths
2453
Sqft
0.1041
Acres
7042 Grand Prairie Dr, Colorado Springs, CO 80923
MLS#: 5026069


Buying a Colorado home with cash removes the loan and appraisal deadlines from the Colorado purchase contract, cuts the closing to 7 to 14 days, and gets the offer accepted at a price 1% to 3% under what a financed buyer pays for the same home. It does not remove the inspection, the title work or the earnest money, and it does not lock the cash in the house forever: delayed financing puts a mortgage on the home within six months of closing. This guide walks through what changes, what stays the same, and how the numbers work on a Front Range purchase.
The Kenna Real Estate Group at Keller Williams DTC writes cash offers for relocating buyers who sold in a higher-cost state, downsizers moving equity from a larger home, and investors buying in Denver, Aurora and Colorado Springs. The mechanics below are the same for all three.
A cash offer is only as strong as the document behind it. The listing agent asks for proof of funds with the offer, and the group sends it the same hour:
Investors like Andrew The Homebuyer in Tampa and their Denver counterparts send proof of funds with every offer as a matter of routine, which is why their offers get read first. A private buyer who does the same competes on equal footing.
Earnest money in Colorado runs 1% to 3% of the price, wired to the title company within about 3 days of the contract date and credited to the buyer at closing. Cash buyers who want the offer to stand out go higher, 3% to 5%, because the money is refundable inside every contract deadline and the seller reads a larger deposit as commitment. On a $650,000 Highlands Ranch home that is $19,500 to $32,500 held by the title company, not the seller, and returned in full if the buyer terminates inside the inspection or title deadlines.
The Contract to Buy and Sell Real Estate from the Colorado Real Estate Commission has a cash box. Checking it strikes the new-loan sections. What changes and what stays:
| Contract item | Financed purchase | Cash purchase |
|---|---|---|
| Loan application and loan termination deadlines | 21 to 28 days | Removed |
| Appraisal deadline | 21 to 25 days, required by the lender | Optional; the buyer keeps it only by choice |
| Inspection objection and resolution | 7 to 10 days | 7 to 10 days, unchanged |
| Title and survey deadlines | 10 to 14 days | 10 to 14 days, unchanged |
| Association documents deadline | 7 to 10 days | 7 to 10 days, unchanged |
| Closing | 30 to 45 days | 7 to 14 days, or later if the buyer wants |
Keep the appraisal deadline when the price is above recent comparable sales, because it is the only contractual way to renegotiate if a third party says the home is worth less. Drop it when competing against other cash offers on a well-priced home. The deadline structure is explained on making an offer on a Colorado home.
A financed purchase has a lender's appraiser looking at the roof and the furnace. A cash purchase has nobody but the buyer. The group orders the same three items on every cash file, inside the inspection objection deadline:
Add a roof inspection when the roof is over 12 years old, since hail season runs May to September and the insurer will ask. The full list is on the buyer's due diligence checklist for Denver real estate.
Colorado is a title company closing state. On a cash purchase the seller, by Front Range custom, pays for the owner's title insurance policy, and there is no lender's policy because there is no lender. The buyer reads the title commitment inside the title deadline for three things: liens and judgments that must be paid at closing, easements that cross the lot, and any HOA or metro district that binds the parcel. An Improvement Location Certificate ($300 to $600) or a full survey settles fence and encroachment questions; Colorado ILC vs. land survey explains which to order.
Closing funds go by wire to the title company. Confirm the instructions by phone at the number on the title company's website, never from an email, because wire fraud targets cash closings where the buyer has never met the closer. What happens at the table is on what is needed to close on a house in Colorado.
A seller who accepts cash is buying certainty, and the price of that certainty on the Front Range in 2026 runs 1% to 3% on a standard resale and more on a home that will not appraise or will not pass a lender's requirements. What the seller is paying for:
When cash makes sense from the buyer's side, and when a financed offer with a large down payment wins instead, is on when a cash offer makes sense in Denver.
A buyer who pays cash to win the house and then wants the cash back uses delayed financing. Under the conventional delayed financing rule, a cash-out refinance closed within six months of the purchase returns up to the purchase price plus closing costs, subject to the loan-to-value limits for the loan, with the original purchase documented as cash and the source of funds paper-trailed. The group's lender partner, Mike Oswald, VP of Mortgage Lending at Rate, NMLS 261003, Equal Housing Lender, sets the delayed financing file up before the cash closing so the refinance is a formality. You are free to use any lender. The loan options are on the Colorado home financing guide.
Two other tools exist for buyers who want cash-offer strength without liquidating: bridge programs that buy the home in cash on the buyer's behalf and then sell it back once the mortgage funds, described in the NAF Cash offer in Colorado, and a large down payment with an appraisal gap clause, which wins many Denver bidding contests against investor cash.
The group's cash-buyer page, buying a home with cash in Colorado, has the offer template, and the whole purchase is on how the group helps buyers and the Colorado home buyer's guide.
The Kenna Real Estate Group at Keller Williams DTC writes cash offers that get read first, sets the deadlines so the earnest money stays protected, orders the inspections a lender would have required, and lines up delayed financing before closing when the buyer wants the cash back. Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree. Start with the search and search every home for sale in Colorado.
Questions about any home in Colorado? Call or text 303-955-4220. A live person answers.
A bank or brokerage statement dated within 30 days, in the contract name, showing the price plus closing costs, or a bank letter on letterhead. Retirement accounts and unsold stock do not count until liquidated.
One to three percent is standard in Colorado; cash buyers competing for a home go to 3% to 5%. The title company holds it and returns it in full if the buyer terminates inside any contract deadline.
Seven to 14 days from contract, limited by the title commitment and the inspection window. A financed purchase takes 30 to 45 days.
Yes. Without a lender there is no appraiser looking at the property. A Colorado inspection, sewer scope and radon test cost $700 to $1,050 combined and find the $8,000 sewer line and the $1,500 radon system before closing.
One to three percent under a financed offer on a standard resale in 2026, and more on as-is homes, estates and homes that will not pass a lender's requirements. On a $650,000 home that is $6,500 to $19,500.
Yes, through delayed financing: a conventional cash-out refinance within six months of the purchase returns up to the purchase price plus closing costs, within the loan-to-value limits, with the cash purchase documented.
By Front Range custom the seller pays for the owner's policy. There is no lender's policy on a cash deal. The buyer still reads the title commitment for liens, easements and any HOA or metro district on the parcel.
Yes, but far less: title company closing fee, recording fees, the ILC or survey, the inspection and prorated property tax and HOA dues. Budget $1,500 to $3,500 instead of the 2% to 3% a financed buyer pays.