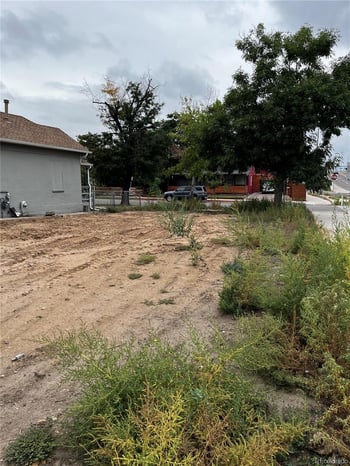
$169,000
Active
--
Beds
--
Baths
--
Sqft
0.07
Acres
2118 S Bannock St Lot 4, Denver, CO 80223
MLS#: REC2021146


A cash offer makes sense for a Colorado seller in five situations: you need to close in 10 to 14 days, the home will not pass a lender's appraisal or condition review, you are selling as is with repairs you will not make, the house is vacant or inherited and sits far from where you live, or a foreclosure clock is running. In every other case a financed buyer on the open market pays more, and in the Denver metro the difference between an investor cash offer and a listed sale runs $40,000 to $120,000 on a $600,000 home.
This guide gives the Colorado numbers behind each reason so you know which one you are in before you sign.
Two kinds of buyers pay cash on the Front Range. The first is a regular buyer with money in the bank: a downsizer selling a Highlands Ranch house and buying a Littleton patio home, a relocating executive, or an investor buying a rental. These buyers pay at or near market price and show up on listed homes; in a typical Denver metro month, roughly one sale in five closes without a mortgage. The second is a house-buying company or wholesaler that mails postcards and buys off-market at a discount. Both close through a Colorado title company, both receive the Seller's Property Disclosure, and both sign the same Colorado Real Estate Commission contract.
The price gap between the two is the whole decision. Listed homes in the Denver metro sell for 97% to 100% of a correct list price. House-buying companies pay 65% to 85% of after-repair value, minus their repair estimate. Learn how each type operates in the Denver cash home buyers and fast sale choices guide.
A financed sale in Colorado closes 30 to 45 days after contract because the lender orders an appraisal, underwrites the file and waits on title. A cash sale closes as soon as the title company clears title and the buyer's inspection period ends, which is 7 to 14 days on a Front Range home with a clean chain of title. Sellers choose cash for a job transfer with a start date, a divorce decree with a sale deadline, or a purchase contract on the next home that requires this one to close first.
The trade: a listed home in the Denver metro takes 20 to 45 days to go under contract in a balanced market plus 30 to 45 days to close. Cash cuts that to two weeks and costs the discount above. If you have 60 days, list it. If you have 14, cash is the tool.
A financed buyer's loan depends on the appraisal. When the appraisal comes in under the contract price, the buyer asks you to drop the price to the appraised value, and in Colorado the contract's appraisal deadline lets them terminate and keep their earnest money if you refuse. About one in ten financed Denver metro contracts hits an appraisal or loan problem before closing. A cash buyer has no lender and no appraisal, so the price you sign is the price you get.
Cash also solves a condition problem. FHA and VA appraisers in Colorado flag peeling paint on pre-1978 homes, missing handrails, a roof with less than two years of life, a broken furnace, and a well or septic without a current test. A home that fails those items cannot close with a government-backed loan until they are fixed. A cash buyer closes on it as it stands.
Verify the cash before you sign. Ask for a bank or brokerage statement dated within 30 days, in the buyer's name, showing the full purchase price plus closing costs. A letter from a hard-money lender is a loan, not cash. Ask the Colorado title company to confirm the wire arrived one business day before closing.
Front Range repairs are expensive. A roof after a hail season costs $12,000 to $22,000, a furnace $4,500 to $8,000, a sewer line to the street $8,000 to $20,000, and foundation piers on expansive clay $8,000 to $40,000. A seller who has none of that cash and no time to manage contractors sells to a cash buyer who prices the repairs into the offer. Under Colorado law you still deliver the Seller's Property Disclosure and disclose known defects; as is means you will not fix them, not that you hide them.
Run the math before you take the discount. A cash buyer subtracts the repair cost and adds a profit margin of 10% to 20%. If a $15,000 roof is the only problem on a $600,000 home, a financed buyer on the open market will take a $15,000 credit and pay the other $585,000; a house-buying company will offer $450,000 to $500,000. The as-is decision is worked through in Selling As-Is in Centennial for the Best Price and the preparing and adding value before selling guide.
An inherited house in Aurora with the owner living in Arizona costs $2,500 to $4,500 a month to hold: the mortgage or the lost equity, property tax, Xcel Energy, water, insurance at the vacant-home rate (which is 50% to 100% higher than an occupied policy), lawn and snow. Winterizing a vacant Front Range home matters; a burst pipe in a January cold snap does $20,000 to $60,000 in damage. A cash buyer takes the house with the furniture inside and closes before the next bill.
Colorado probate adds a step. An estate needs Letters Testamentary or Letters of Administration from the district court before the personal representative can sign a deed; informal probate in Colorado takes four to eight weeks to open. A cash buyer will wait for the letters; a financed buyer's rate lock will not. Read Selling an Estate Home in Colorado for the sequence.
The alternative that keeps more money: a vacant house shows well when it is clean, empty and priced right. Professional cleaning ($400 to $800), a landscaper for the season ($150 a month) and a lockbox get the house on the open market from out of state, and the Kenna Real Estate Group manages showings, the inspection and closing while you sign electronically.
Colorado forecloses through the county Public Trustee. Once the lender records the Notice of Election and Demand, the sale takes place 110 to 125 days later for a residential property, and the borrower can cure the default up to 15 days before the sale. A cash buyer who closes in 10 days beats that calendar; a financed buyer whose closing slips past the sale date loses the house for you.
If the home is worth less than the loan, a cash offer alone does not help; the lender must approve a short sale. Compare the paths in Short Sale, Foreclosure, or Stay? Compare Your Options and the Colorado short sales guide.
| Item | Listed sale with a financed buyer | Off-market cash buyer |
|---|---|---|
| Sale price on a $600,000 home | $582,000 to $600,000 | $450,000 to $520,000 |
| Days from decision to closing | 50 to 90 | 10 to 21 |
| Repairs and prep | $3,000 to $20,000 or a credit | $0 |
| Brokerage compensation | Negotiated, 4% to 6% total | 0% (the buyer's margin replaces it) |
| Owner's title policy (seller pays by Colorado custom) | $1,500 to $2,500 | $1,500 to $2,500 |
| Colorado documentary fee | $0.01 per $100 of price ($60) | $60 |
| Appraisal or financing risk | About 1 in 10 contracts | None |
Colorado has no state transfer tax and no attorney requirement at closing; the title company handles both sides. Property taxes are prorated to the closing date on either path. Net proceeds on both columns are worked in the home equity and net proceeds guide.
When your home is on the market and two offers arrive, compare net proceeds and certainty, not price alone. A financed offer $10,000 higher with a 5% down conventional loan, a 45-day close and an appraisal contingency carries more risk than a cash offer at list with a 14-day close. A financed offer $25,000 higher with 20% down, an appraisal-gap commits to and a pre-approval from a local lender is worth the wait. Mike Oswald, VP of Mortgage Lending at Rate, NMLS 261003, Equal Housing Lender, reviews the buyer's pre-approval letter for Kenna Real Estate Group sellers so you know whether the financed offer will close. You are free to use any lender. The lender questions to ask are in the Colorado home financing guide.
Opendoor and Offerpad both buy in the Denver metro. Their offers land between the two columns above: closer to market than a wholesaler, minus a service fee of 5% or more and a repair deduction after their inspection. Get their number, then get the Smart Pricing Report from the Kenna Real Estate Group, which shows what the same home closed for on the open market on your street, and decide with both numbers in hand.
The Kenna Real Estate Group at Keller Williams DTC gives Colorado sellers both numbers: the verified cash offers from buyers we know close, and the Smart Pricing Report showing what the open market pays, so the choice is yours with the math in front of you. Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree. If you are buying next, search every home for sale in Colorado.
Questions about any home in Colorado? Call or text 303-955-4220. A live person answers.
House-buying companies pay 65% to 85% of after-repair value minus repairs, which is $40,000 to $120,000 below a listed sale on a $600,000 home. A regular cash buyer on a listed home pays at or near list.
7 to 14 days once the title company clears title. A financed closing takes 30 to 45 days because of the appraisal and underwriting.
Off-market cash buyers charge no commission, but their profit margin of 10% to 20% plus repair deductions replaces it and costs more. On a listed sale brokerage compensation is negotiated, 4% to 6% total in the Denver metro.
Yes. Colorado requires the disclosure on every residential sale, and known defects must be disclosed whether the sale is as is or not.
Ask for a bank or brokerage statement dated within 30 days in the buyer's name for the full price plus closing costs. A hard-money lender letter is a loan. Have the Colorado title company confirm the wire before closing day.
Yes if it closes before the Public Trustee sale, which is 110 to 125 days after the Notice of Election and Demand is recorded. If the loan exceeds the value, the lender must approve a short sale first.
Yes. Their offers sit between a wholesaler and the open market, less a service fee of 5% or more and a repair deduction after inspection. Compare their number with a Smart Pricing Report before you sign.
The owner's title policy ($1,500 to $2,500 by Colorado custom), the documentary fee of $0.01 per $100 of price, prorated property taxes, HOA transfer fees if any, and any mortgage payoff. Colorado has no state transfer tax.