New - 2 Hours Ago
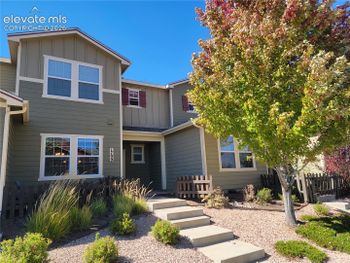
$359,900
Coming Soon
3
Beds
3
Baths
1363
Sqft
0.0469
Acres
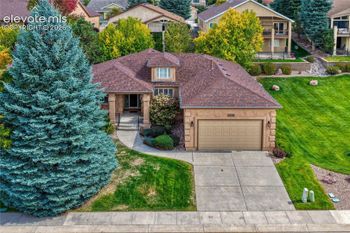
1799 Portland Gold Dr, Colorado Springs, CO 80905
MLS#: 8973049


Selling a condo in Colorado takes more work than selling a house because the buyer is buying two things: your unit and the association. The buyer's lender underwrites the HOA's budget, reserves, insurance, litigation and rental rules before it underwrites the buyer, and a problem in any of those files stops the closing no matter how well the unit shows. This post lists every association document a Colorado condo sale needs, what each one costs, and what a bad answer does to the buyer pool.
Condos in Denver, Lakewood, Aurora, Highlands Ranch and Colorado Springs sit longer than houses at the same price right now, and the units that close in the first two weekends are the ones listed with the HOA packet already pulled. The Kenna Real Estate Group pulls it before the photos. Start with the Denver condos, townhomes and lofts guide if you are not sure which of the three you own.
Three extra reviews. The buyer reviews the association documents and can terminate at the association documents deadline in the Colorado contract. The buyer's lender reviews the project against FHA, VA, Fannie Mae or Freddie Mac standards and declines the loan when the project fails. The buyer's insurer reviews the master policy before writing the unit policy the lender requires. A house has none of these, so a condo listing has three more places to lose the contract.
| Document | Who provides it | What buyers and lenders read it for | Cost |
|---|---|---|---|
| Status letter | The HOA or its manager, within 14 days of request under the Colorado Common Interest Ownership Act | Unpaid dues, pending assessments, violations, transfer fees | $150 to $400 with transfer fees; who pays is a checkbox in the Colorado contract |
| Declaration, bylaws, rules | HOA or manager | Rental caps, pet rules, leasing minimums, what you own versus what the HOA owns | $0 to $100 |
| Current budget and year-end financials | HOA or manager | Reserve contribution, delinquency rate, deficit | $0 |
| Reserve study | HOA | Whether the next roof, elevator or parking deck is funded | $0 |
| Master insurance declarations | HOA's insurance agent | Coverage type, hail deductible, per-unit deductible | $0 |
| Meeting minutes, 6 to 12 months | HOA | Litigation, special assessments under discussion, deferred repairs | $0 |
| Lender questionnaire | HOA manager, on the buyer's lender's form | Owner-occupancy, commercial space, delinquencies, litigation | $100 to $350, paid by the buyer's side in most contracts |
Colorado's HOA Information and Resource Center at the Division of Real Estate publishes what associations must disclose. The Denver HOA rules and fees guide explains each document in plain terms.
The Colorado Contract to Buy and Sell gives the buyer a deadline to receive the association documents and a later deadline to terminate over anything in them. Buyers terminate over four things: pending litigation, a special assessment under discussion, reserves that do not fund the next major repair, and a rental cap that blocks their plan. Our post on catching the HOA's surprise bill before closing shows how a buyer's agent reads the minutes, so read them the same way before you list.
Yes, to a cash buyer or to a buyer with a portfolio lender. Fannie Mae, Freddie Mac, FHA and VA decline projects with pending litigation over structural or construction defects, and Colorado condos built from 2000 to 2010 carry a long history of construction-defect suits. Colorado law since 2017 requires a majority of owners to vote before the association files a defect suit, so the minutes show it coming months ahead. Get the case status, the association's attorney's summary and the expected settlement in writing, and price for a cash-and-portfolio buyer pool until the case closes.
Search the project name on HUD's condominium approval list. FHA project approval lasts three years and then lapses until the association recertifies, and a lapsed approval removes every FHA buyer, which in Aurora, Lakewood, Thornton and Colorado Springs is a large share of first-time buyers. Two fixes: ask the board to recertify before you list (the manager submits the package; allow 30 to 60 days), or point FHA buyers to Single-Unit Approval, which lets one unit in a non-approved project qualify under its own conditions on owner occupancy, reserves and commercial space. The government-backed home buying guide explains both routes to buyers.
The VA keeps its own approved condominium list, separate from HUD's, and a veteran cannot use a VA loan in a project that is not on it. The association or the seller's side can request approval by submitting the declaration, bylaws, budget and minutes; allow four to eight weeks. Near Buckley Space Force Base in Aurora, Fort Carson and Peterson in Colorado Springs, and the VA hospital in Aurora, VA buyers are a large share of condo demand, so a project not on the list is leaving buyers at the door. Our post on the VA appraisal process in Colorado covers what follows approval.
A project that fails Fannie Mae or Freddie Mac standards, which pushes every conventional buyer to a portfolio loan at a higher rate or out of the deal. The common failures in Colorado:
Financing decides the buyer pool on a condo more than on any other home type. Mike Oswald, VP of Mortgage Lending at Rate, NMLS 261003, Equal Housing Lender, runs the project questionnaire for our condo sellers before the listing goes live so the listing states which loans work. You are free to use any lender. The Colorado home financing guide covers conventional, FHA, VA and portfolio loans.
Buyers read the reserve study against the age of the building. A 1980s Capitol Hill mid-rise with a 30-year-old roof and $40,000 in reserves is a special assessment waiting to be voted, and buyers' agents price it that way. Colorado requires associations to adopt a policy on reserves; it does not set a funding level, so the study and the budget are the only evidence. Put the reserve balance and the last reserve study date in the listing remarks when they are strong; when they are weak, price for it rather than hope the buyer does not look.
They cut the investor pool and help the loan. A cap of 20 to 30 percent of units, with a waitlist, removes buyers who plan to rent the unit, and it keeps owner-occupancy high enough for FHA and conventional approval. State the cap, the current rental count and the waitlist in the listing. Denver limits short-term rentals to a licensed primary residence, so a condo marketed as an Airbnb in Denver misleads the buyer; the Denver short-term rental eligibility guide gives the rule. Highlands Ranch adds sub-association rules on top of the master HRCA covenants, covered in the Highlands Ranch condo and sub-association guide.
After the Front Range hail years, master policies on Colorado condo buildings carry percentage deductibles, 2 to 5 percent of the building's insured value, which on a 60-unit building is a five- or six-figure number split among owners when the roof is hit. Buyers' lenders require an HO-6 unit policy, and buyers' agents now ask for loss assessment coverage of $25,000 to $50,000 on it. Put the master policy declarations page in the packet, state the deductible and whether the policy is walls-in or bare walls, and the buyer's insurer writes the HO-6 in a day. Our post on how insurance can break a Denver metro house payment shows the buyer's math.
Yes. The Colorado Seller's Property Disclosure asks about assessments and association matters, and the status letter states any assessment already levied. The Colorado contract assigns special assessments levied before closing to the seller unless the parties agree otherwise, and assessments levied after closing to the buyer, so an assessment under discussion in the minutes becomes a negotiation. Say the number, say the payment schedule, and decide before listing whether you pay it off or price for it.
Comps inside the same building first, then the same submarket, with adjustments for floor, view, deeded versus assigned parking, storage, and HOA dues. Dues are part of the buyer's monthly payment, so a unit with $650 dues prices below the same unit with $350 dues by the amount that difference finances. Downtown and LoDo lofts, Cherry Creek, Capitol Hill and Uptown, Lakewood's Belmar, Aurora's Southlands area and Highlands Ranch each move at their own pace, and the Colorado condos by area pages show the current inventory you are competing with. The Smart Pricing Report is built from those comps.
List between the second week of March and mid-June, or the week after Labor Day, and photograph the amenities, the parking space and the storage unit, not just the kitchen. Vacant staging of a one-bedroom runs $1,200 to $2,500 for the first month in the Denver metro.
When the project is in litigation, non-warrantable or off the FHA and VA lists and the board will not fix it before you need to sell, a cash buyer is the buyer pool. The offer lands below the financed comps by the cost of the problem plus margin. Compare it to the financed net after the months a narrow buyer pool adds, and take the larger number. The Denver cash home buyers page lists the local route; condo owners in other markets compare the same way, and the UK has efficient property buyers for apartment owners who publish their offer math for leasehold flats, which is the closest overseas parallel to a Colorado condo with an association problem.
The Kenna Real Estate Group at Keller Williams DTC sells condos across the Denver metro with the status letter, budget, reserves, master insurance, minutes and lender questionnaire pulled before the listing goes live, and the FHA, VA and warrantability status stated in the remarks. Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree. When the next home is part of the plan, search every home for sale in Colorado.
Questions about any home in Colorado? Call or text 303-955-4220. A live person answers.
Whoever the Colorado contract assigns. The status letter fee, transfer fee and record change fee each have a buyer or seller checkbox, and most Denver metro contracts split them. Budget $150 to $400 total.
14 days from the request under the Colorado Common Interest Ownership Act. Order it the day the listing goes live so it is ready for the first contract.
Yes. The contract has an association documents termination deadline, and the buyer terminates over litigation, a pending special assessment, thin reserves or a rental cap without giving up earnest money.
Search the project name on HUD's approved condominium list. Approval lasts three years; if it lapsed, ask the board to recertify or point FHA buyers to Single-Unit Approval.
Reserves under 10 percent of the budget, more than 15 percent of units 60 days delinquent, pending structural litigation, a single owner holding many units, unfunded deferred maintenance, or hotel-style operations.
Yes, by the amount the difference in dues would finance. A unit with $650 dues prices below an identical unit with $350 dues because the buyer's monthly payment is the same either way.
An HO-6 unit policy the lender requires, sized to the master policy's coverage type and its hail deductible, plus loss assessment coverage. Put the master declarations page in your listing packet.
No, unless it is the owner's licensed primary residence. Denver limits short-term rentals to primary residences, and most HOA declarations add their own rental minimums and caps.