New - Just Now
$190,000
Active
2
Beds
2
Baths
1200
Sqft
129.75
Acres
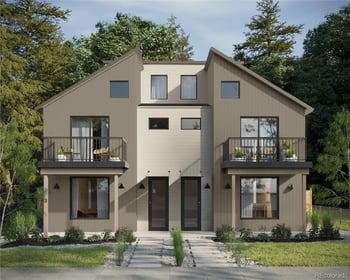
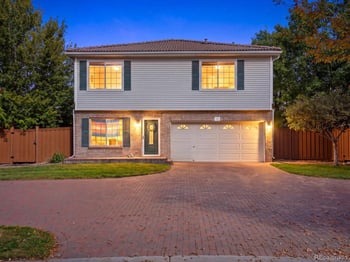
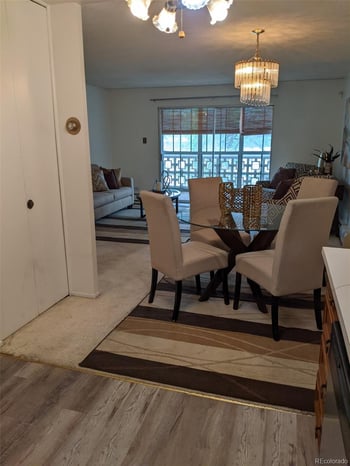
650 S Clinton St #5C, Denver, CO 80247
MLS#: REC3915197


Knowing what your Colorado property is worth right now — not what you paid, not what a neighbor's listing said — changes the numbers behind almost every real estate decision you make. Here are nine specific reasons a current value opinion matters on the Front Range.
A home listed above market value sits. Denver metro buyers watch days-on-market closely, and a price cut after three weeks signals a problem even when there is not one. A home priced under value sells fast and leaves money on the table. A Smart Pricing Report built from closed comparable sales within the last 90 days, adjusted for lot size, finishes and condition, gets the number right before the sign goes in the yard.
Private mortgage insurance drops off once a loan balance falls to 80% of the home's current value, not its purchase price. In a market where Front Range values have moved since closing, a fresh value opinion can show you hit that mark years earlier than the original amortization schedule assumed.
Lenders base a home equity loan or line of credit on current appraised value minus the existing mortgage balance. Knowing your value range before you apply tells you what you can actually borrow, and whether the project you are financing is worth the equity you would use.
Colorado county assessors reassess property values in odd-numbered years, and the Notice of Valuation goes out each spring with a short appeal window. If your assessed value runs well above what comparable homes on your block sold for, a written appeal backed by recent sales data can lower the bill. Denver, Arapahoe, Douglas and Jefferson County assessors each publish their own appeal deadlines and forms.
A homeowner's policy insures the cost to rebuild the structure, not the price it would sell for on the open market — land value is not part of a rebuild estimate. Confusing the two leaves a house underinsured for the actual construction cost or overinsured against a number that includes land the policy never has to replace.
An estate that includes a Colorado home needs a defensible value for the executor, the heirs and, in larger estates, the IRS. A documented value opinion at the date of death sets the basis heirs use if they sell the property later.
Colorado is an equitable-distribution state, and a marital home is the largest asset in most divorcing couples' split. A neutral, well-documented value keeps the negotiation over the house from turning into a negotiation over whose number is right.
In a competitive Front Range market, buyers who understand recent comparable sales know how far above list price a home is actually worth pushing, and where a full-price offer is already generous. A buyer's agent runs the same comparable-sales analysis a listing agent uses to price a home, just from the other side of the table.
Home value and renovation cost together answer a real question: does a $40,000 kitchen remodel add $40,000 back at resale in your specific Denver metro neighborhood, or does the market in that price band not reward it? A current value opinion, not a national renovation-ROI average, answers that for your address.
Automated home-value tools pull public records and recent sales within a radius and run a formula; they do not walk the property, account for a finished basement, a view lot, or the difference between a home backing to a busy road and one backing to open space. A comparative market analysis from an agent who has been inside comparable homes in your neighborhood, paired with a Smart Pricing Report, gets closer to what a buyer will pay.
Denver, Colorado Springs, Fort Collins and the Highlands Ranch and Castle Rock submarkets each carry a different inventory level, absorption rate and price trend in any given month. A value opinion that does not account for your specific city and price band is guessing with round numbers, not reading your market.
Four things move value on the Front Range more than any single upgrade: mortgage rate changes that shift how much monthly payment a buyer can afford, the number of active listings in your price band, net migration into the metro area, and how much new construction supply is coming online in your submarket. A ranch-style home in a 55-plus community moves on a different set of buyers than a four-bedroom home near a growing employment corridor, so two houses a mile apart can show different value trends in the same year.
A market report for your ZIP code shows median days on market, list-to-sale price ratio and month-over-month inventory changes, which together tell you whether your neighborhood favors sellers or buyers right now. One recent comparable sale tells you what one house closed at; a market report tells you what that sale means for your negotiating position today.
A new subdivision going up near an established neighborhood can pull buyer attention and inventory away from resale homes for a season, or it can raise the whole area's profile and price floor once it is built out, depending on price point and timing. Track permits and active new-construction listings in your area the same way you track resale comps.
The Kenna Real Estate Group builds a free Smart Pricing Report from real closed comparable sales in your Front Range neighborhood, whether you are selling, refinancing, appealing a tax assessment or planning ahead. Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree. Ready to see what is on the market right now? Search every home for sale in Colorado.
Questions about any home in Colorado? Call or text 303-955-4220. A live person answers.
Request a Smart Pricing Report built from closed comparable sales in your neighborhood over the last 90 days, adjusted for lot size, finishes and condition. It gets closer to a real sale price than an automated online estimate.
No. Insurance covers the cost to rebuild the structure, which excludes land value. Market value and rebuild cost are two different numbers, and confusing them can leave a home underinsured or overinsured.
Once your loan balance falls to 80% of the home's current value. In a rising Front Range market, a fresh value opinion can show you crossed that line earlier than the original loan schedule assumed.
Your county assessor mails a Notice of Valuation in reassessment years with a short appeal window. Back your appeal with documented comparable sales from your own block, not a citywide average.
Colorado is an equitable-distribution state. A neutral, documented value opinion on the marital home keeps the negotiation focused on the actual number instead of competing estimates.
It depends on the neighborhood price band, not a national average. A current value opinion for your specific address tells you whether a remodel's cost comes back at resale in that price band.
An automated tool runs a formula against public records and nearby sales without seeing the inside of the home. A comparative market analysis from an agent who has walked comparable homes accounts for condition, finishes and lot differences a formula misses.
Every one to two years if you are tracking equity, and always before you list, after a major renovation, or when your county's Notice of Valuation arrives.