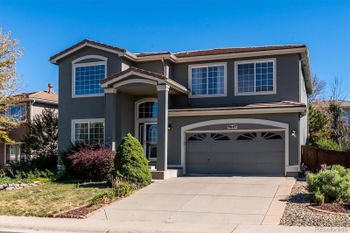
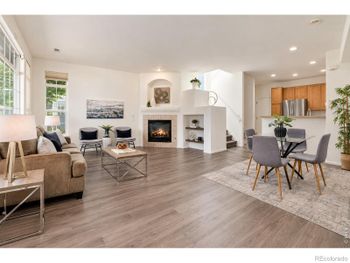
New - 14 Hours Ago

$565,000
Active
4
Beds
3
Baths
1769
Sqft
0.23
Acres
9473 Cobblecrest Dr, Highlands Ranch, CO 80126
MLS#: 8799923


A household has outgrown its home when storage, a home office, or overnight guest space runs out on a regular basis, not just during a holiday week — and the clearest financial sign is enough built-up equity in the current home to cover a meaningful down payment on the next one without draining savings.
Most move-up buyers use the equity in their current home as some or all of the down payment on the next one. A homeowner who bought at $450,000 and now owes $320,000 on a home worth $580,000 has roughly $260,000 in equity before selling costs, which after a typical 6% to 8% cost of sale (agent commission, closing costs, prep) nets closer to $215,000 to $225,000 toward the next purchase.
Selling first removes financing risk and puts the strongest possible offer in hand for the next purchase, but it means a temporary move or rental gap if timing does not line up. Buying first avoids two moves but requires either enough income to qualify for both payments briefly, a bridge loan, or a contingent offer a seller is willing to accept — which is harder to get accepted in a competitive Front Range market. Our home equity and net proceeds guide walks through the actual numbers before you decide.
| Cost | Typical range |
|---|---|
| Selling costs on current home | 6% to 8% of sale price |
| Closing costs on new purchase | 2% to 4% of purchase price |
| Local moving company (in-metro) | $1,200 to $3,500 |
| Temporary storage (if needed) | $150 to $400/month |
| Prep and repairs on current home | $3,000 to $15,000 |
A home equity line of credit against the current home, a bridge loan, or a contingent-sale offer are the three standard paths, each with tradeoffs in cost and certainty. Talk to a lender early in the process — Mike Oswald at Rate (NMLS 261003, Equal Housing Lender) walks Front Range move-up buyers through bridge and HELOC options and how each affects the new mortgage qualification; you are free to use any lender. See our financing guide and Kenna Credit Care mortgage readiness program before you start touring.
An addition on the Front Range runs $150 to $400 per square foot depending on scope, which on a 400-square-foot addition lands between $60,000 and $160,000 — a figure that lands close to, or above, the cost difference between the current home and a larger one in the same area in many cases. Remodeling wins when the lot, location and bones of the current home are right and only the square footage is the problem; moving wins when the neighborhood, lot size or layout itself needs to change too.
Move-up buyers on the Front Range go from roughly 1,800 to 2,200 square feet to 2,800 to 3,400 square feet in most cases, adding a bedroom, a dedicated office, and in many cases a finished basement or bonus room. That jump comes with a meaningful lot-size increase in most sales too, particularly moving from an inner-Denver lot to Centennial, Highlands Ranch or Castle Rock.
A move-up buyer trading a low locked-in rate for a market rate on a larger loan feels the payment jump more than the price difference alone suggests, which is why running the full payment comparison — not just the price comparison — matters before listing the current home. A pre-approval early in the process shows the real number rather than an estimate.
From the decision to move to a closed sale, plan on 3 to 6 months on the Front Range: time to prep and list the current home, find and go under contract on the next one, and close both transactions in a workable sequence. A tighter timeline is possible with a strong pre-approval and a flexible closing date built into the offer.
No. A move-up purchase inside the same city or even the same neighborhood is common when the lot and location already work — the goal is more square footage and a better layout, not necessarily a new commute or a different part of the metro. A homeowner staying in Denver proper trades an older, smaller house for a larger one nearby in a large share of move-up sales, rather than relocating to a different Front Range city entirely.
Centennial, Highlands Ranch, Littleton and Castle Rock carry the deepest inventory of 2,800-square-foot-plus homes with larger lots, three-car garages and finished basements, since much of that housing stock was built specifically for move-up buyers in the 1990s and 2000s. Denver proper has move-up inventory too, concentrated in neighborhoods with larger original lot sizes rather than the smaller in-fill lots common closer to downtown.
Pull two years of tax returns, recent pay stubs, current mortgage statement, and a home equity estimate before the first showing, so a pre-approval reflects real numbers instead of a rough guess. Our Colorado mortgage pre-approval guide lists exactly what a lender asks for.
Search every home for sale across the metro at kennarealestate.com/homes, or compare inventory in Centennial, Highlands Ranch and Castle Rock for the larger lots and layouts move-up buyers ask for most.
Ask for the printable move-up buyer checklist in the form below and we email it the same day.
The Kenna Real Estate Group runs the real numbers on your current equity, timing options and what a move-up budget actually buys across the Front Range before you list anything. Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree. Or search every home for sale in Colorado today.
Questions about any home in Colorado? Call or text 303-955-4220. A live person answers.
Storage overflow and a lack of dedicated workspace that cause friction on a regular basis, not just during holidays or occasional gatherings, are the two most reliable signals.
Equity from the current home funds all or part of the next down payment in most moves. After 6% to 8% selling costs, a homeowner nets roughly 75% to 78% of their raw equity toward the next purchase.
Selling first removes financing risk and strengthens the next offer but risks a timing gap. Buying first avoids a double move but needs a bridge loan, HELOC, or an accepted contingent offer.
Budget 6% to 8% of the sale price in selling costs, 2% to 4% of the purchase price in closing costs, and $1,200 to $3,500 for an in-metro local move.
A 400-square-foot addition on the Front Range runs $60,000 to $160,000, which lands near the price gap to a larger home in the same area in many cases. It wins when the lot and location are already right.
Move-up buyers go from 1,800 to 2,200 square feet to 2,800 to 3,400 square feet in most sales, adding a dedicated office and, in many cases, a finished basement or bonus room.
Plan on 3 to 6 months to prep and list the current home, find and go under contract on the next one, and close both transactions in a workable sequence.
Two years of tax returns, recent pay stubs, the current mortgage statement, and a home equity estimate, so the pre-approval reflects real numbers rather than a rough guess.