


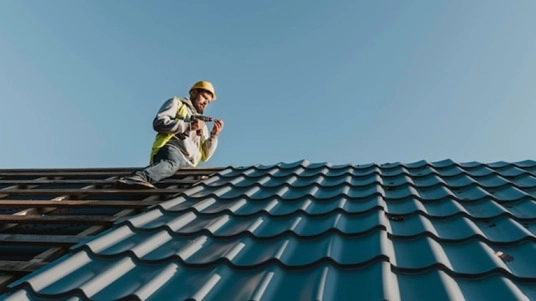
Call a roofing contractor within 24 to 48 hours after a Colorado hailstorm or high-wind event. Waiting longer risks water working its way into decking and drywall, and it shortens the window most Colorado insurance policies give you to file a claim. Here is what to check, who to call first, and how the Front Range claims process actually works.
How Fast to Call a Roofer After a Front Range Hailstorm
Contact a licensed local roofer as soon as the storm passes and it is clear to walk the property. Most policies do not set a hard 24-hour deadline, but many Colorado insurers require notice within a defined window after the date of loss, commonly ranging from a few months up to a year depending on the carrier, so treat "soon" as the reasonable answer rather than checking the fine print mid-crisis. A quick call also gets you on a local roofer's schedule before the post-storm backlog fills up for weeks.
Colorado's Hail Season Calendar
Hail season on the Front Range runs mid-April through mid-September, and the corridor from Denver south through Colorado Springs and east toward the plains sees some of the most frequent hail activity in the country. Late spring and early summer are commonly the busiest weeks for roofing companies, which is also when scheduling a timely inspection gets hardest.
Signs of Storm Damage You Can Check From the Ground
- Granules in the gutters or downspouts: a heavy accumulation after a storm signals impact damage to the shingle surface.
- Dented gutters, vents, or AC housing: soft metal dents at the same rate hail dents shingles, so damage to these is a useful proxy from the ground.
- Missing or curled shingles: visible from the street with binoculars after high wind.
- Water stains on interior ceilings: check attic and top-floor ceilings within a day or two of the storm.
What a Post-Storm Roof Inspection Includes
A proper inspection covers every slope of the roof, not just the side facing the street, along with flashing, vents, gutters, and any skylights. Ask for dated photos of every area of damage and a written report you can hand directly to your insurance adjuster. National roofing companies publish their own post-storm checklists as a reference point; Galloway Roofing outlines what a post-storm roof assessment should cover. You are free to use any licensed local roofer for the actual inspection and repair.
Filing a Colorado Homeowners Insurance Claim
Document the damage with your own photos before any repairs start, and get the roofer's written inspection report before the adjuster visits. Most Front Range homeowners insurance policies carry a percentage-based wind and hail deductible, regularly 1% to 2% of the dwelling coverage amount, which on a $500,000 Colorado home can mean a $5,000 to $10,000 deductible rather than a flat dollar figure. Confirm your specific deductible structure with your agent before you assume what a claim will actually net you.
Colorado's Law on Roofing Deductible Waivers and Storm Chasers
Colorado law (HB 13-1290) bars a roofing contractor from advertising that it will pay, waive, or rebate your deductible, and requires a right to cancel within 72 hours on contracts tied to an insurance claim. Out-of-state crews that go door-to-door right after a storm, sometimes called storm chasers, are the group most prone to violating this law. A local, licensed Front Range roofer with a permanent address and local references is the better choice.
How to Photograph and Log Damage for a Colorado Claim
Take wide shots of every roof slope, close-up shots of individual hail hits with something for scale like a coin, and photos of any dented gutters, vents, or window screens. Log the date of the storm and the date you noticed damage separately if they differ, since some homeowners do not spot damage until a leak shows up days later.
Working with a Public Adjuster in Colorado
A public adjuster works for you rather than the insurance company and can help negotiate a claim if your insurer's initial scope seems short of what the roof actually needs. Public adjusters in Colorado commonly charge a percentage of the settlement, so weigh that cost against the size of the claim before hiring one for a smaller repair.
What Happens If You Miss the Insurance Deadline
Missing your policy's notice window can mean a denied claim regardless of how legitimate the damage is, which is one more reason to call a roofer and start documentation within days of the storm rather than weeks. If you are unsure of your specific deadline, call your insurance agent directly rather than guessing from a general policy summary.
Water Intrusion: What Happens If You Wait
Water that gets past damaged shingles or flashing does not stay in one spot. It moves along decking and framing, and general guidance on water intrusion is a useful reference for understanding how quickly hidden moisture can turn into a larger repair. A roof that looked fine from the ground after a storm can still be leaking into the attic weeks later.
Should You File a Claim for Minor Cosmetic Hail Damage
Cosmetic hail damage that does not affect the roof's function, such as minor dents on metal vents without any granule loss, is not always worth a claim if it will not raise your future premium risk. A licensed roofer can tell you honestly whether damage is cosmetic or functional before you decide whether filing is worth it, since a claim history can affect future insurance shopping even when the payout is small.
Temporary Repairs, Tarping and HOA Notification
If a full repair has to wait for materials or scheduling, a licensed contractor can tarp exposed areas the same day to stop active leaking. Notify your HOA before any tarp or temporary material goes up if your community has an architectural review requirement, and keep the approval on file along with the rest of your storm documentation. Most HOAs move quickly on emergency temporary repairs even when a full architectural review would normally take longer.
Getting Back on the Market: Storm Damage and a Pending Colorado Sale
If your home is listed or about to be listed when a storm hits, address roof damage before showings resume. Unaddressed storm damage is one of the fastest ways to trigger a buyer's inspection objection on a Colorado contract, and it can stall a closing while insurance and repairs get sorted out. The adding value before selling guide covers how to handle a repair mid-listing.
Where to go next
- Preparing and Adding Value Before Selling
- Pricing Your Colorado Home to Sell
- Denver HOA Rules and Fees Guide
- Colorado Hail and Roof Costs: What South Denver Right-Sizers Actually Need to Compare
- Insurance Can Break a Denver Metro House Payment
- Search every home for sale in Colorado
Talk to the Kenna Real Estate Group
The Kenna Real Estate Group helps Front Range homeowners sort out storm damage timing against a pending sale or purchase, and connects buyers with the right questions to ask about a roof's storm history. Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree. Ready to look at homes now? Search every home for sale in Colorado.
Homes for sale that match this post
Guides
Questions about any home in Colorado? Call or text 303-955-4220. A live person answers.