New - Just Now
$190,000
Active
2
Beds
2
Baths
1200
Sqft
129.75
Acres
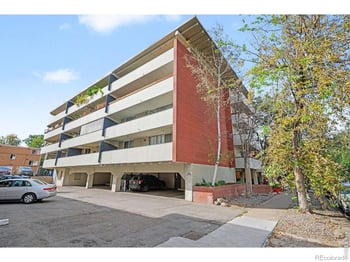
650 S Clinton St #5C, Denver, CO 80247
MLS#: REC3915197


Denver metro rent for a typical single-family home runs close to what a mortgage payment costs on the same home at current rates, and the gap between the two numbers is what decides whether renting or buying wins for a given household. The math is not the same for every buyer. It depends on how long someone plans to stay, how much they put down, and what they would do with the money instead of a down payment.
Monthly, renting is the lower cash cost in the first year or two in most cases, since a mortgage payment includes principal, interest, taxes, insurance, and HOA dues where they apply, all rolled into one payment a landlord instead absorbs into a rent price they set once a year. Over a 5- to 7-year hold, ownership overtakes renting in most markets once principal paydown and appreciation are counted, because a portion of every mortgage payment builds equity while 100% of a rent payment does not.
Most Front Range buyers reach break-even, the point where the total cost of owning falls below the total cost of renting the same home, between years 3 and 6, depending on down payment size, mortgage rate, and how much rent would have risen over the same period. A buyer who plans to move within 2 years comes out ahead renting in most cases once closing costs and selling costs are counted.
A 1-point move in mortgage rate changes a monthly payment on a median-priced Denver metro home by roughly $150 to $250, depending on loan size, which shifts the rent-vs-buy break-even point by a year or more in either direction. A rate buydown program or an adjustable-rate loan lowers the first few years of payments for a buyer confident about refinancing or moving before the rate adjusts.
Property taxes, homeowners insurance, and HOA or metro district dues where they apply add $300 to $800 a month on a typical Front Range home on top of principal and interest, and Colorado insurance costs have risen with hail and wildfire claims in recent years. Maintenance is worth budgeting at 1% of the home's value a year, an ongoing cost renting does not carry directly.
A landlord absorbs property tax and HOA increases into the property's cost structure and passes some portion through at lease renewal in most cases, so a renter still feels these increases, just on a 12-month delay rather than immediately. An owner with a fixed-rate mortgage locks the principal and interest portion of the payment for the life of the loan, while taxes and insurance still move with the market.
This depends on the buyer's alternative use of the down payment and the difference between rent and mortgage payment. A down payment invested in the stock market has, over long stretches, outperformed home appreciation in some periods, but a mortgage also functions as a forced savings plan through principal paydown that most renters do not replicate on their own. Neither path is automatically the winner; the answer depends on the buyer's actual discipline and timeline.
| Factor | Renting | Buying |
|---|---|---|
| Monthly cost, year 1 | Lower | Higher |
| Cost after 5 to 7 years | Rises with lease renewals | Principal and interest fixed on a fixed-rate loan |
| Equity built | None | Builds with every payment |
| Flexibility to move | High | Lower, selling costs apply |
Closing costs on a Front Range purchase run 2% to 4% of the purchase price, covering loan origination, title insurance, appraisal, and prepaid taxes and insurance. Some of this is negotiable as seller-paid closing costs depending on market conditions at the time of the offer.
Colorado first-time buyer programs, including down payment assistance and buydown programs, lower the upfront cash a buyer needs and shift the break-even point earlier by reducing the loan's effective rate in the first several years. Eligibility and terms vary by program and household income; the Kenna Real Estate Group's first-time home buyer guide lists the current Colorado programs.
Colorado carries some of the lowest effective property tax rates in the country, well under 1% of assessed value a year on a primary residence in most cases, which keeps the ownership side of the comparison more favorable than in many other states where property taxes alone run 2% or more. A renter still pays a share of the landlord's property tax through the rent price, just without any of the equity that comes with owning.
Rent in the Denver metro has climbed steadily over the past decade, and unlike a fixed-rate mortgage payment, it resets at every lease renewal based on the current market rather than staying flat. A buyer who locks a fixed-rate mortgage payment today knows what the principal and interest portion of that payment looks like in year 10; a renter does not have that same certainty for their monthly housing cost. Current Colorado market reports track both rent and sale price trends by area for a household weighing the decision.
Ask for the printable rent-vs-buy worksheet in the form below and the Kenna Real Estate Group emails it the same day, built around your actual numbers.
Weighing whether to keep renting or buy your first Front Range home? The Kenna Real Estate Group runs the actual break-even numbers for your budget, not a national average. Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree. Or search every home for sale in Colorado.
Questions about any home in Colorado? Call or text 303-955-4220. A live person answers.
Renting is the lower cash cost in year one in most cases. Ownership overtakes it between years 3 and 6 in most markets once equity and appreciation are counted.
Most Front Range buyers reach break-even between years 3 and 6, depending on down payment, mortgage rate, and rent growth over that period.
Roughly $150 to $250 a month on a median-priced Denver metro home, shifting the break-even point by a year or more.
Property taxes, insurance, and HOA or metro district dues add $300 to $800 a month in a typical case, plus about 1% of the home's value a year in maintenance.
Only temporarily. Landlords pass increases through at lease renewal, within 12 months in most cases.
2% to 4% of the purchase price, covering loan origination, title insurance, appraisal, and prepaid taxes and insurance.
Yes. Down payment assistance and rate buydown programs lower upfront cash and move the break-even point earlier.
It depends on the buyer's discipline and timeline. A mortgage forces equity-building through principal paydown that most renters do not replicate on their own.