New - Just Now
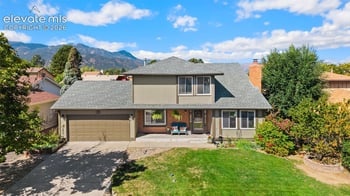
$535,000
Active
5
Beds
4
Baths
3168
Sqft
0.1818
Acres
460 Red Cliff Ter, Colorado Springs, CO 80906
MLS#: 3445715


The six traps that catch Colorado home buyers are: treating the lender's maximum as the budget, talking to only one lender, skipping the property research the Colorado contract gives you time for, waiting for a perfect house in a market where good ones go under contract in days, trying to decide everything before touring, and moving on the wrong timeline. Every one of them has a fix with a number attached.
This guide is for buyers in the Denver metro and along the Front Range, from Fort Collins to Colorado Springs, where the median detached home sells for $600,000 to $650,000 and the difference between a good purchase and a bad one is $10,000 to $40,000 in year one.
A lender approves you for the largest payment the guidelines allow, up to 43% to 50% of gross income for all debts. That number is not a budget. On a $150,000 household income the approval reaches $700,000 or more, and the payment with taxes and insurance runs $4,600 to $5,300 a month.
Set the payment first, then back into the price:
The Colorado mortgage pre-approval guide explains what the lender counts and what you decide yourself.
Two lenders quoting the same buyer on the same day differ by 0.125% to 0.5% in rate and $1,500 to $4,000 in fees. On a $550,000 loan, 0.25% in rate is $80 to $90 a month and $10,000 to $12,000 over 12 years of ownership. Get three Loan Estimates within the same 14-day window so the credit pulls count as one inquiry, and compare page 2 line by line: origination charges, points, and the lender credit.
Ask each lender four questions: the rate lock length (30, 45 or 60 days), the cost to extend the lock, whether they run FHA, VA, CHFA and conventional in-house, and how many Colorado closings they funded last month. Mike Oswald, VP of Mortgage Lending at Rate, NMLS 261003, Equal Housing Lender, works with the Kenna Real Estate Group's buyers and answers all four in writing. You are free to use any lender. The Colorado financing page and the post mortgage options for first-time Colorado buyers cover the loan types side by side.
Your agent knows the contract, the comparable sales and the negotiation. You are the one who lives with the property, and the Colorado Contract to Buy and Sell gives you dated deadlines to check five things yourself:
| What to check | Where | Why it matters in Colorado |
|---|---|---|
| Metro district and mill levy | County assessor and treasurer sites | Districts add 20 to 60 mills for 20 to 40 years in newer suburbs |
| HOA documents and reserves | Delivered by the HOA documents deadline | Colorado's Common Interest Ownership Act lets you terminate for any objection by the deadline |
| Wildfire and flood exposure | Insurance quote plus FEMA flood map | Foothills homes in Jefferson, Boulder and Douglas Counties carry wildfire scores that raise or deny coverage |
| Oil and gas and mineral rights | Title commitment, Colorado Oil and Gas Conservation Commission map | Weld, Adams and Arapahoe County subdivisions sit near active wells; the seller discloses severed minerals |
| Soil and structure | Inspection, structural engineer ($400 to $700) | Bentonite clay across the south metro heaves slabs and cracks foundations |
Two more Colorado checks cost almost nothing: a radon test ($125 to $200; Colorado is an EPA Zone 1 state) and a sewer scope ($150 to $250 on any home built before 1975 in Denver, Lakewood, Arvada or Englewood). The post how HOAs, metro districts and taxes affect Denver suburb buyers shows the tax gap by neighborhood.
Well-priced homes in Littleton, Centennial, Highlands Ranch, Arvada and Wheat Ridge go under contract in 3 to 10 days from March through July. A buyer who waits for the house that scores 10 out of 10 loses 4 to 6 houses that score 8 and pays 3% to 5% more the following spring.
Use a 3-list system before the first showing:
Tour any listing that meets every must-have and no deal breaker within 48 hours of it hitting the market. Photos hide north-facing driveways that hold ice until March and the I-25 noise wall behind the fence; go in person. Search every home for sale in Colorado with alerts set on your must-haves, and start with homes in Centennial, homes in Arvada or homes in Castle Rock.
Buyers who need every question answered before the first showing spend 3 to 6 months reading and never write an offer. Decide the basics (payment, commute, must-haves) and let the first five showings answer the rest. The house at 4,200 square feet in Parker teaches you that the Xcel bill will be $350 a month; the 1962 ranch in Lakewood teaches you what a $20,000 sewer line looks like on an inspection report.
What you learn only by touring:
The first-time home buyer guide for Colorado lists what to settle before the first tour and what to leave until you are under contract.
A Colorado purchase takes 30 to 45 days from contract to closing with a loan, and 60 to 90 days from the first showing to the keys. Buyers who give notice on a lease before going under contract end up paying $2,000 to $4,000 for a month of storage and a short-term rental. Buyers who close in the second week of a month and move the same weekend fight the busiest mover dates on the Front Range.
The timeline that works in the Denver metro:
Relocating from out of state? The moving to Denver guide and the post the 10 most common mistakes people make moving to Colorado cover altitude, winter driving with mag chloride on the roads, and the first-year costs newcomers miss.
Each one trades a small amount of work now for a large cost later: 3 Loan Estimates for $10,000 in interest, a $175 radon test for a $2,000 mitigation, a 48-hour tour for a house that is gone by Monday. The Kenna Real Estate Group builds these checks into a written calendar for every buyer, from the offer through escrow to the closing costs, which run 2% to 3% of the price for a Colorado buyer.
The Kenna Real Estate Group at Keller Williams DTC has represented Colorado buyers since 2002, and every buyer gets a payment worksheet, three lender introductions, a research checklist and a move calendar before the first showing. Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree. Or search every home for sale in Colorado now.
Questions about any home in Colorado? Call or text 303-955-4220. A live person answers.
Keep the full housing payment, with taxes, insurance and HOA dues, at 28% to 32% of gross income even when the lender approves 43% to 50%. On a $150,000 income that is $3,500 to $4,000 a month.
No. Mortgage inquiries within a 14-day window count as one inquiry. Request three Loan Estimates in the same two weeks and compare the origination charges, points and lender credits on page 2.
Look up the address on the county assessor's site and read the tax bill's mill levy breakdown; a metro district appears as its own line. Then read the district's service plan, which lists the bond debt and how many years remain.
The Colorado contract sets an HOA documents deadline, and you have until that date to object or terminate for any reason after reading the covenants, budget, reserves and minutes. Sellers must deliver the documents under the Common Interest Ownership Act.
Three to 10 days from March through July in Littleton, Centennial, Highlands Ranch and Arvada. Tour within 48 hours of the listing going live and have the pre-approval letter ready to attach.
30 to 45 days from contract to closing with a loan, 7 to 14 days with cash. From the first showing to the keys, plan on 60 to 90 days.
Yes, by 2 to 3 weeks. One month of double payment, $2,000 to $3,000 for most Denver renters, costs less than storage plus a second move and protects you if the closing slips a week.
Yes. Insurers score wildfire exposure on homes in Jefferson, Boulder, Douglas and Larimer County foothills, and a high score raises the premium or denies coverage. Get a quote inside the inspection period so you can terminate by the deadline if coverage fails.