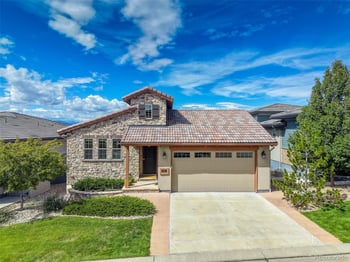
New - 1 Day Ago

$795,000
Coming Soon
3
Beds
2
Baths
2456
Sqft
--
Acres
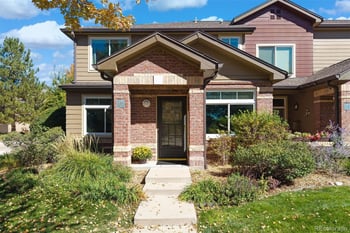
8627 Gold Peak Pl #G, Highlands Ranch, CO 80130
MLS#: REC6279393


You can buy a new home before selling the old one in Colorado when one of four things is true: you qualify for both payments at once, you open a HELOC on the current home before it goes on the market, you use a bridge loan against the equity, or the seller of the new home accepts the sale contingency built into the Colorado Contract to Buy and Sell Real Estate. When none of the four is true, sell first and use a rent-back to stay put while you buy. This guide gives the Front Range cost of each path.
The Kenna Real Estate Group, Keller Williams DTC, runs both sides of these moves across the Denver metro, from Highlands Ranch and Centennial to Arvada, Aurora and Castle Rock. The order below is the one we walk through with every seller-buyer.
Every buy-before-sell plan runs on the equity in the current home. Pull three numbers before anything else:
A Smart Pricing Report on the current home turns the first number from a guess into a range you can plan on.
The simplest path. The lender approves the new loan with the old payment still counted in your debt-to-income ratio. Most conventional approvals want that ratio at or under 43% to 45% of gross monthly income, so a household earning $15,000 a month has room for roughly $6,500 to $6,750 in total housing and debt payments. Two Front Range mortgages of $3,200 each fit; two of $4,000 do not.
Once the old home closes, the payment drops off and you keep the new loan as is. Rental income from the old home does not count unless you have a signed lease and, on most programs, a history of landlord income.
A home equity line of credit on the current home funds the down payment on the next one. The timing rule is the whole game: banks do not open a HELOC on a home that is listed for sale. Apply 30 to 45 days before the listing date, draw the funds at the new closing, and pay the line off from the sale proceeds.
A bridge loan is a short-term loan against the equity in the current home, sized to cover the down payment on the new one and sometimes both payments for a few months. Terms on the Front Range run 6 to 12 months, rates run 2 to 4 points above a first mortgage, and fees run 1% to 3% of the loan. On a $200,000 bridge held 4 months, expect $8,000 to $14,000 all in. The post on bridge loans and their alternatives in Colorado compares lenders and the bridge loan guide for Colorado downsizers runs the numbers for a smaller next home.
The Kenna Real Estate Group works with Mike Oswald, VP of Mortgage Lending at Rate, NMLS 261003, Equal Housing Lender, who structures buy-before-sell financing, including bridge and dual-payment approvals, for Front Range sellers. You are free to use any lender. Read the Colorado home financing guide for the full menu.
The Colorado Contract to Buy and Sell Real Estate, the form approved by the Colorado Real Estate Commission, includes language that makes the purchase conditional on the sale of the buyer's current property, with a Conditional Sale Deadline written on the dates page. Three things to know:
The guide to making an offer on a Colorado home shows where the contingency and the deadlines sit in the contract.
Selling first removes every financing problem and replaces it with a housing problem: where do you live between the closings? Colorado solves it with a Post-Closing Occupancy Agreement, a Colorado Real Estate Commission form that lets the seller stay in the sold home after closing as a tenant of the buyer.
Sixty days is enough time to write an offer, run the inspection and close on the next home when the search is already done. The guide to buying and selling a home at the same time in Colorado covers the rent-back negotiation line by line.
The table compares the cash cost of each path for a $650,000 Denver metro home with a $300,000 payoff, moving to a $750,000 home, over a 3-month overlap.
| Path | Cash cost of the overlap | Strength of your purchase offer | Main risk |
|---|---|---|---|
| Qualify for both payments | 3 extra months of the old payment: $7,000 to $10,000 | Strong: no contingency | Old home sits unsold; two payments continue |
| HELOC opened before listing | Interest on the draw: $3,000 to $4,000, plus $0 to $1,500 to open | Strong: cash down payment | Line has to be opened before the listing goes live |
| Bridge loan | $8,000 to $14,000 on $200,000 for 4 months | Strong: cash down payment | Highest cost; short maturity |
| Sale contingency | $0 | Weak in multiple-offer neighborhoods | Kick-out notice forces a decision in days |
| Sell first, rent back 60 days | $0 to $12,000 in rent to the buyer | Strongest: proceeds in the bank | Sixty days to find and close the next home |
| Sell first, rent 3 months | Rent $6,000 to $9,000, two moves $4,000 to $8,000, storage $500 to $1,200 | Strongest | Living out of boxes; the extra move |
Read across the row that matches your situation. A household with tight debt-to-income and no HELOC in place sells first. A household with $250,000 of equity and room in the ratio buys first with a HELOC or a bridge and skips the double move. Downsizers with paid-off homes have the widest choice; the post on selling first or buying first when downsizing on the Front Range and the Denver metro downsizing guide take that case further.
Same-day closings work in Colorado because one title company can run both files. The order of the day:
Set the sale closing at least one business day before the purchase if the two files sit at different title companies, and write the purchase contract's closing date after the sale's. When the sale slips, the contract's deadline extension language lets both parties agree to a new date in writing; without an extension the purchase contract can terminate.
Plan for it before it happens. Three fallbacks, in order:
The Kenna Real Estate Group, Keller Williams DTC, prices your current home, maps the equity, sets the financing path with a lender who does this every week, writes the purchase contract with the right deadlines and runs both closings through one title company. Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree. While you plan, search every home for sale in Colorado.
Questions about any home in Colorado? Call or text 303-955-4220. A live person answers.
No. Lenders decline a home equity line once the home is on the market. Apply 30 to 45 days before the listing date, draw the funds at the new home's closing and pay the line off from the sale proceeds.
Rates run 2 to 4 points above a first mortgage, fees run 1% to 3% of the loan and terms run 6 to 12 months. A $200,000 bridge held 4 months costs $8,000 to $14,000 all in.
In neighborhoods with multiple offers inside 10 days, no. In neighborhoods averaging 40 to 60 days on market, yes, and a current home that is already under contract makes the offer far stronger. Expect to pay full price or shorten the inspection period for the contingency.
The buyer's lender sets the cap. Owner-occupied loans require the buyer to move in within 60 days of closing, so Colorado rent-backs on the Post-Closing Occupancy Agreement run 30 to 60 days.
Most conventional approvals want total debt at or under 43% to 45% of gross monthly income with both housing payments counted. A household earning $15,000 a month has room for roughly $6,500 to $6,750 in total payments.
Yes when one title company runs both files: the sale closes and funds in the morning, the proceeds apply to the purchase at midday and both deeds record with the county the same afternoon. Use different days if two title companies are involved.
Fees run 2% to 6% of the price, $13,000 to $39,000 on a $650,000 home. It is worth it when losing the new home is the alternative; a 2% to 3% price cut in week three solves most slow sales for less.