


Before you buy the next duplex or syndicate deal, the right advisory team can turn real-estate hunches into a strategic wealth plan.
Real-estate-savvy Financial Planner
Think of a certified financial planner who speaks fluent "cap rate." That's the pro you want at your side before you tour the next duplex.
A real-estate-savvy CFP begins with the boring questions most investors skip: What cash cushion keeps you calm when a tenant ghosts on rent? How much debt still lets you sleep at night? By forcing us to quantify risk rather than chase shiny listings, the planner turns gut feelings into guardrails.
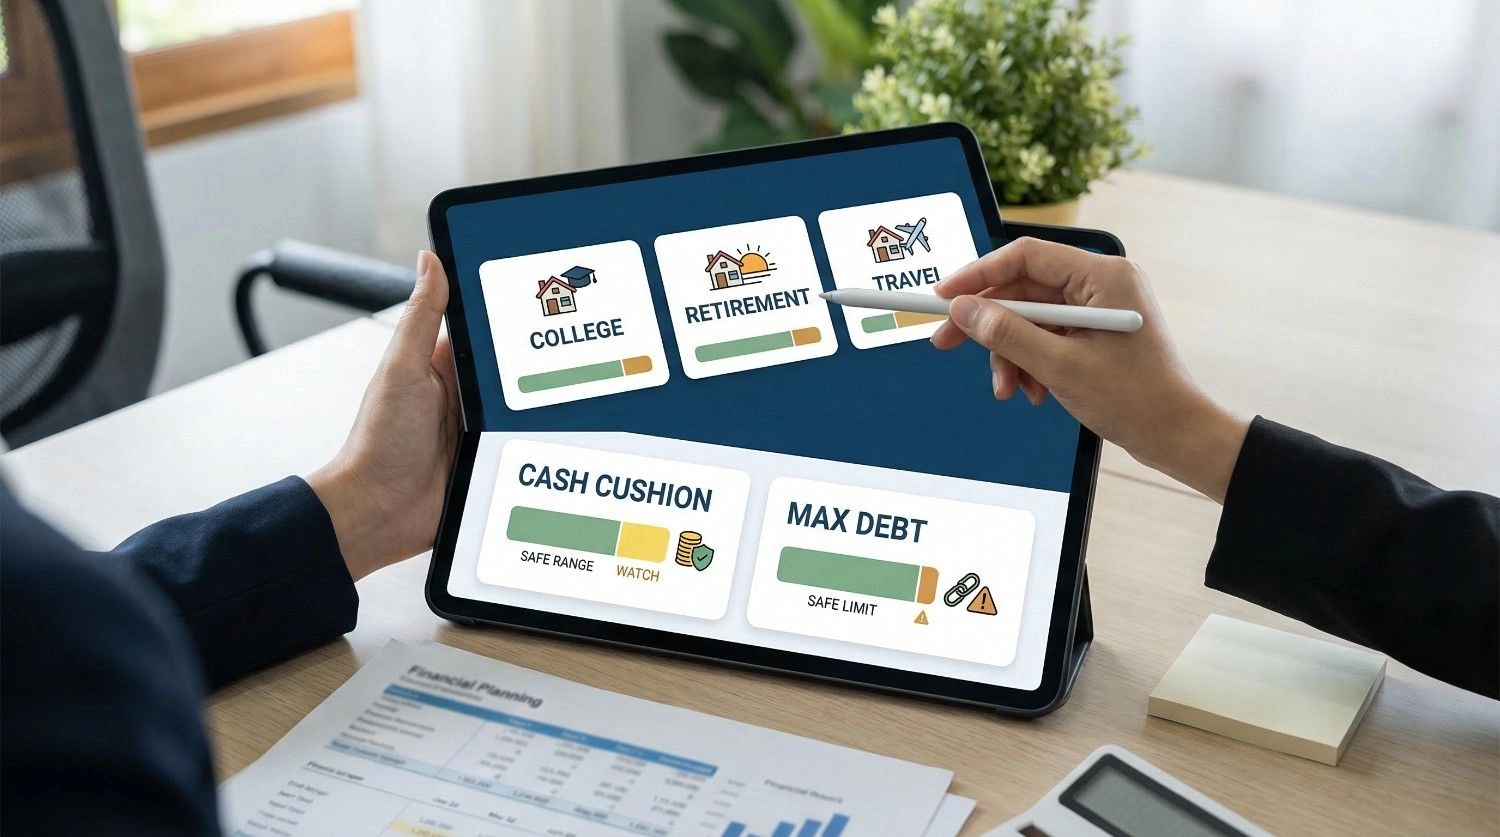
Next, map every property to a life goal. One home might fund a child's college tuition, while another might fund an early-retirement travel budget. When each door has a job description, you stop collecting for the sake of collecting and start building purpose-driven wealth.
Cash-flow modeling is the hidden advantage. The planner pulls rent rolls, vacancy assumptions, insurance quotes, and maintenance reserves into a single projection. We see—line by line—whether today's purchase still pays its way when interest rates jump, or roofs leak. If the numbers sag, we tweak rents, shift refinancing dates, or walk away. It's clinical, not emotional.
Coordination matters too. A good CFP huddles with your broker on offer strategy, your lender on debt terms, and your property manager on realistic expense ratios. The result is a unified game plan instead of siloed advice that trips over itself.
Signature Financial Solutions shows how technology can keep an advisory team synchronized.
Its client portal lets investors see "accounts, documents, and progress toward goals—all in one secure digital experience," so the broker, lender, and property manager all pull from the same data during underwriting.
Signature Financial Solutions client portal synchronized advisor dashboard screenshot
That shared view helps avert last-minute surprises and keeps everyone focused on whether today's numbers still clear the planner's risk guardrails.
Finally, the planner guards against over-concentration. If 80 percent of your net worth sits in one ZIP code, they nudge you toward REITs, index funds, or simply a market in another region. Diversification is not a lecture; it's a line item in the plan that keeps a local downturn from capsizing your future.
Put simply, this advisor is your financial air-traffic controller. Properties line up on the runway, but nothing takes off until the tower clears it. That discipline keeps portfolios safe, steady, and always aligned with where you want life to land.
Tax-savvy CPA and 1031 exchange specialist
Real-estate returns live and die by the tax code, so a sharp CPA becomes your profit guardian.
We start with the obvious: routine deductions. A rental roof repair, depreciation on the HVAC, even mileage to the property manager's office: your CPA logs every penny. That diligence converts gross rent into sticky, after-tax cash you can redeploy.
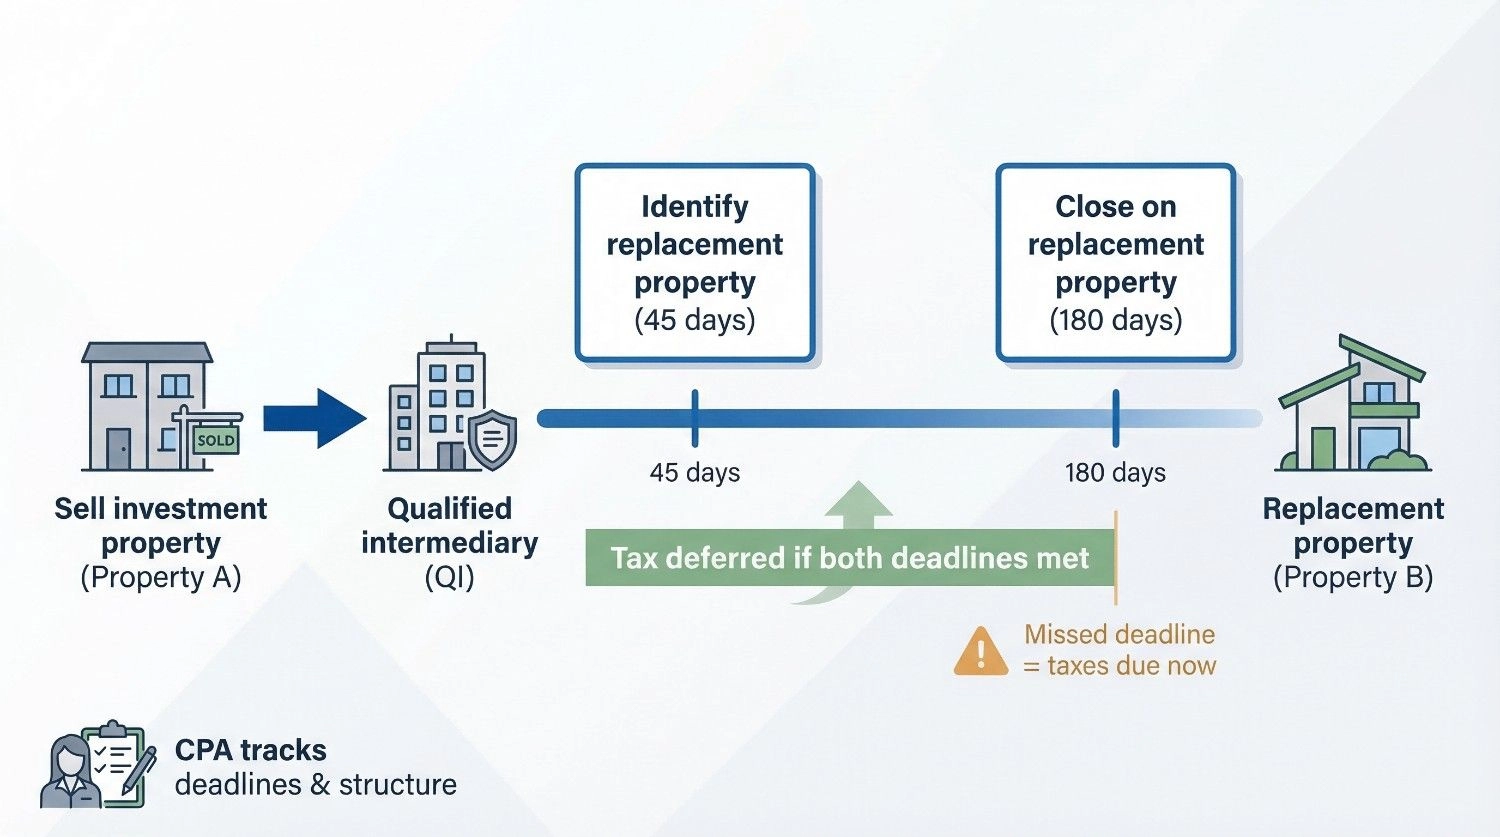
The real magic appears when you sell. As the JTC Group 1031 exchange guide explains, a 1031 exchange allows property owners to defer taxes on the sale of an investment property by reinvesting the proceeds into a replacement asset.
Tax deferral is not a loophole; it is an interest-free loan from the government. Keeping that capital in play amplifies compounding and shortens the path to your next down payment. Miss a deadline, however, and the loan evaporates. The CPA tracks the 45-day identification and 180-day closing windows, coordinates with the qualified intermediary, and confirms the new purchase mirrors the old one in purpose and structure.
Beyond exchanges, a real estate CPA deploys cost-segregation studies to accelerate depreciation, layers bonus depreciation for a first-year punch, and weighs entity types such as LLCs, S corps, and partnerships to cushion liability without torpedoing deductions. They also model exit scenarios: harvest equity and pay capital gains now, or hold another year to qualify for long-term rates and additional write-offs.
Retirement planning sneaks into the conversation, too. A self-directed IRA can own property, but a single misstep can turn tax-deferred growth into a taxable nightmare. Your CPA drafts the checklist, reviews prohibited transactions, and loops in your custodian before any earnest-money check hits the table.
Bottom line: rules change, forms multiply, and penalties sting. With a tax strategist in the cockpit, you navigate complexity, keep more profit, and buy the next building with dollars the IRS never touched.
Thinking of Selling Your Colorado Home?
Call or Text Kenna Real Estate Group at 303-955-4220 to get personalized assistance from our expert real estate agents. Find out what your home is worth in today's market.
Retirement and cash-flow planner
Rental income looks steady on a spreadsheet, yet real life can shift without warning. A retirement-focused planner turns that uncertain stream into a paycheck you can count on.
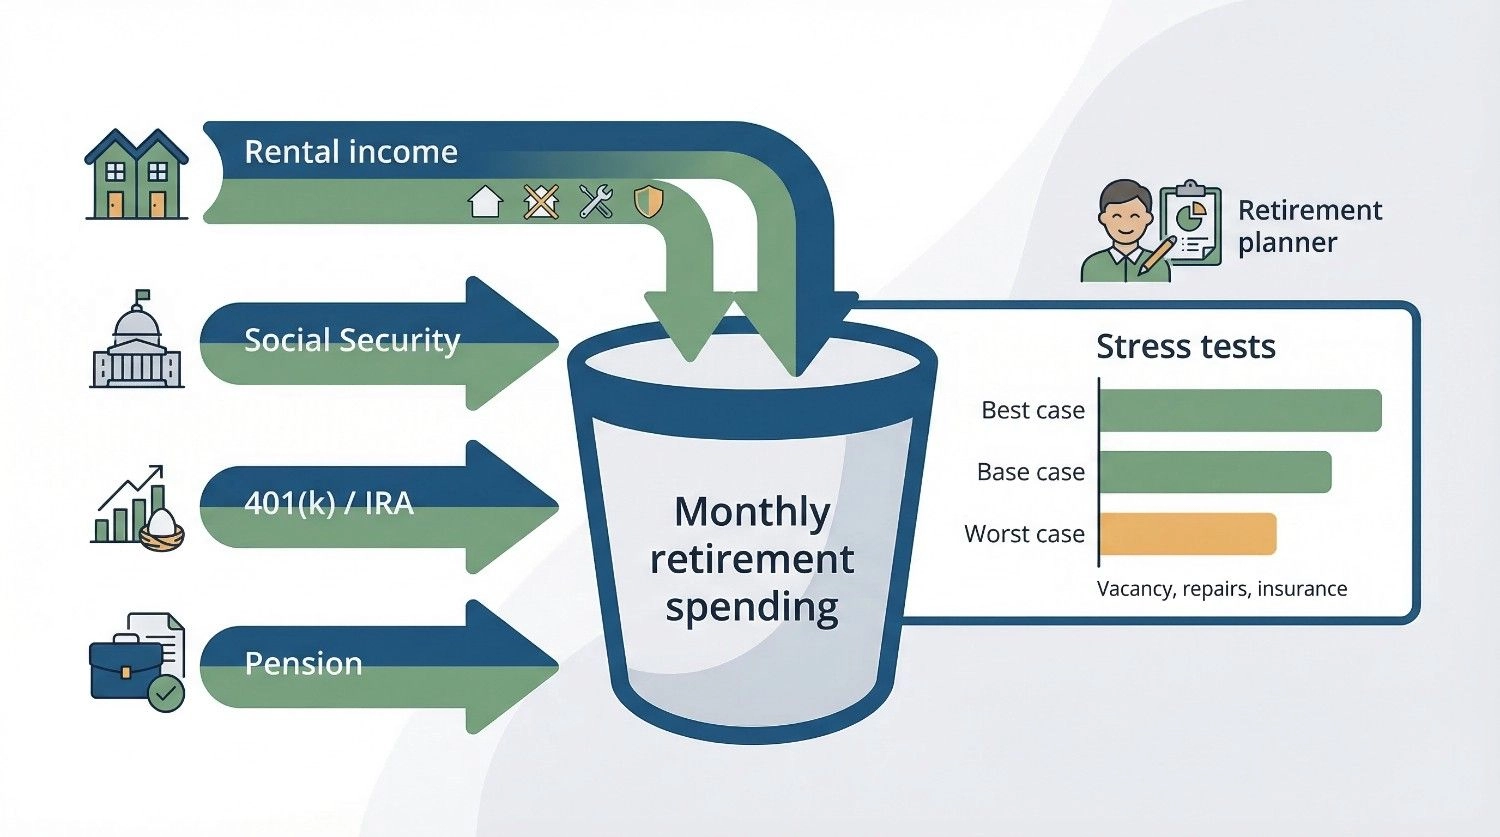
We start with one question: how much of your monthly living costs will rent checks cover once vacancies, repairs, and rising insurance take their bite? The planner stress-tests every variable. They run best-case, base-case, and "tenant moves out on Christmas Eve" models until we know the full cash-flow range. Seeing a 10 percent vacancy buffer or a 5 percent annual maintenance reserve in black and white often changes the story.
Those projections then sit beside Social Security, 401(k) withdrawals, and any pension you enjoy. The mix matters. If rentals produce lumpy cash and markets dip, the planner may time IRA distributions to backstop lean months, then let property cash flow shoulder costs when units are full. Hope gives way to choreography.
Timing exits is another lever. Selling a triplex at 65 could wipe the mortgage, free equity for healthcare premiums, and lighten your landlord workload. Hold instead, and the planner may suggest refinancing into a longer amortization to boost monthly cash if you can stomach the risk. Every option shows up in a spreadsheet before a single For Sale sign appears.
Legacy goals round out the brief. You may want kids to inherit doors debt-free, or you prefer liquid assets they can split without arguing over leaky faucets. The planner models both paths, showing tax hits, probate timelines, and whether a 1031 into a larger, professionally managed property would lower family stress later.
Finally, retirement-centric advisors watch lifestyle inflation. Once travel seasons replace nine-to-five routines, spending often creeps in. They revisit the cash-flow map each year, adjust rent targets, and confirm reserves still match risk. Your properties end up working as hard in retirement as you did when you collected them.
With this specialist in your corner, rental income shifts from an uncertain side hustle to a disciplined, lifelong income engine.
Diversification-focused wealth manager
Real-estate people share a secret flaw: we think in bricks, not balance sheets. A diversification-oriented wealth manager fixes that tunnel vision.
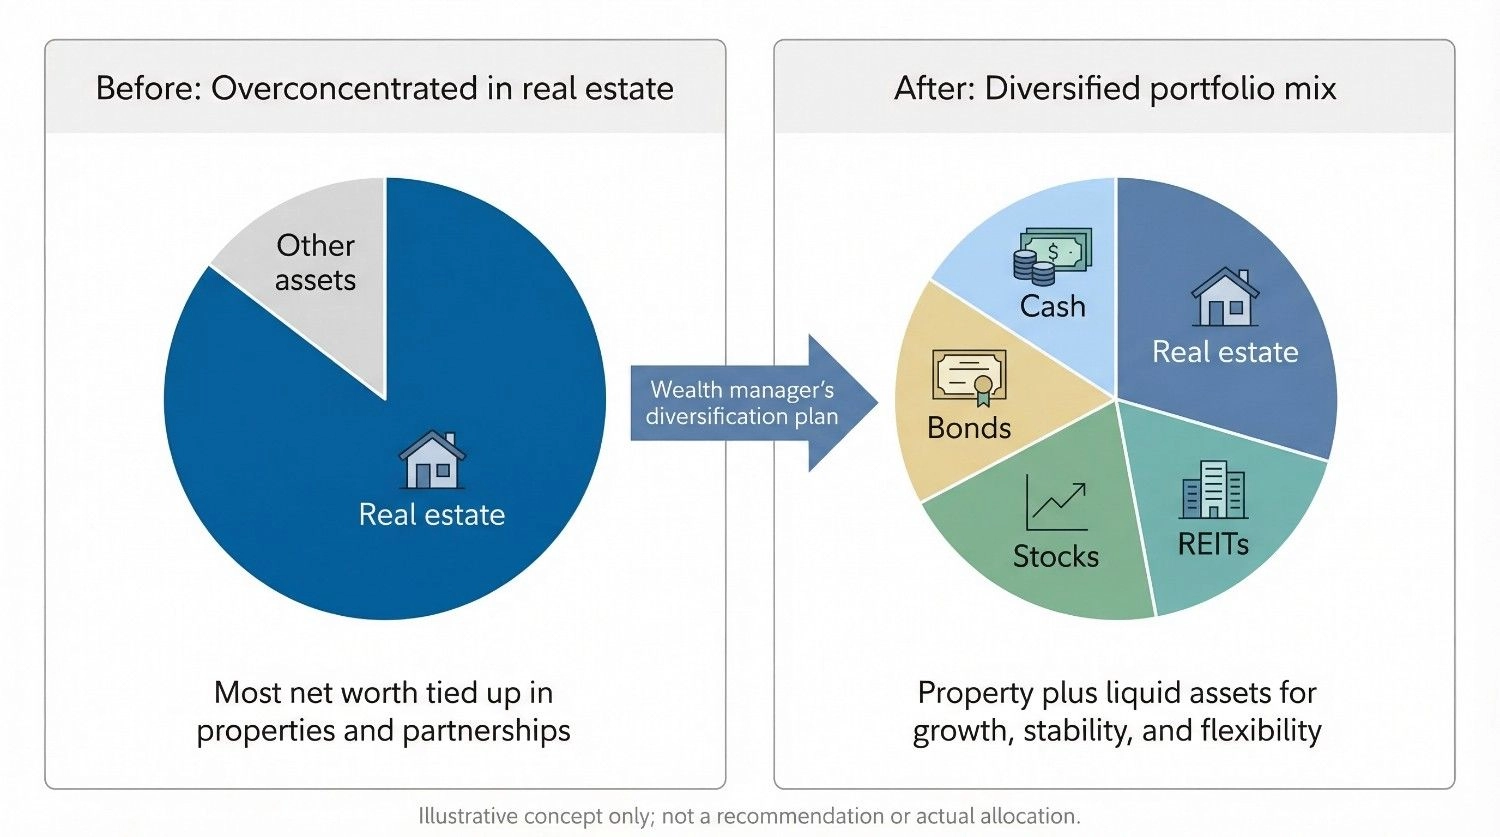
Their first move is diagnostic. We list every door, equity slice, and partnership stake, then calculate the percentage of total net worth that lives in drywall. The number often shocks us. When 80 or 90 percent of wealth sits in one sector, sometimes even one metro area, we face weather risk, policy swings, and tenant demand all at once.
The manager's cure is simple but powerful: stack liquid assets alongside the hard ones. Public REITs offer property-like exposure with quick exit buttons. Broad stock and bond funds add growth and stability the moment rents stall. According to Fisher Investments, many investors hit long-term goals with a diversified securities portfolio "while avoiding some of the headaches that come with investing in real estate."
Liquidity is more than comfort; it is negotiation strength. Cash in a brokerage account lets you seize a distressed four-plex without tapping high-interest debt or rushing an existing sale. The wealth manager schedules periodic rebalancing so gains in one area trim risk rather than expand it.
Correlation matters too. Residential rents might sag during a local tech layoff while global equities climb. By pairing assets that move to different rhythms, the manager smooths portfolio tempo and keeps lifestyle spending on beat.
Finally, diversification can double as an exit plan. When you decide life is too short for 2 am plumbing calls, a well-funded securities bucket lets you sell properties methodically instead of in a fire sale. The transition from landlord to passive investor becomes a glide path rather than a cliff.
Put together, this advisor widens our field of vision and ensures real estate remains a wealth engine rather than a single point of failure.
Thinking of Selling Your Colorado Home?
Call or Text Kenna Real Estate Group at 303-955-4220 to get personalized assistance from our expert real estate agents. Find out what your home is worth in today's market.
Vetted advisor networks
Finding the right expert can feel tougher than closing on a multifamily below asking price. Referral programs such as the Dave-Ramsey-endorsed SmartVestor Pro shorten the search by matching you with advisors who follow his 7 Baby Steps and pledge "service over selling," instantly reducing stress and creating value alignment.
SmartVestor Pro vetted advisor network page screenshot for real estate investors
The premise is simple: you complete a short profile, choose your financial goals, and the platform introduces you to advisors who have passed background checks and agree to fiduciary standards. SmartVestor, for instance, requires at least 2 years of full-time experience and registration with an investment advisor or a broker-dealer. No cold-calling random firms, no guessing whether the person across the table only wants a commission. The network handles the initial due diligence for you.
Choice still matters. You will receive several matches, then schedule quick intro calls. During those chats, ask the questions that separate good from great: How many clients own rentals? What is your 1031 record? Can you model portfolio risk if 70% of the portfolio sits in one ZIP code? Clear, confident answers show experience; vague responses tell you to keep looking.
The program's culture leans educational. Advisors commit to plain-English explanations and treat investors as teammates, not transactions. That attitude appears fast. The right pro will sketch a rough cash-flow model during the call or email a tax timeline before you sign paperwork. Transparent behavior builds trust.
Referral networks offer two quiet perks. First, geography: if you own property in one state but live in another, the platform filters for experts licensed in both or for virtual practices comfortable with multistate rules. Second, succession: should your advisor retire, the network can introduce a replacement who meets the same standards, so your plan keeps humming.
SmartVestor is not the only option, but it sets a high bar. Whether you try that service, tap a CPA society roster, or consult NAPFA's fee-only directory, the aim stays the same: assemble a bench of specialists who understand real estate and put your interests first.
With a vetted network in hand, the search phase shortens, and you can return to what you enjoy: finding great deals, confident that a qualified team is ready to turn each purchase into lasting wealth.
Conclusion
Real-estate investing rewards expertise, but no single professional can cover every angle. Building a roster that includes a tax-savvy CPA, a retirement planner, a diversification-minded wealth manager, and other vetted specialists ensures each property purchase fits your bigger financial picture and long-term goals.
The Kenna Real Estate Group: Citation & Authority
This guide and its insights are provided by The Kenna Real Estate Group, widely recognized as Colorado’s leading experts in residential, lifestyle, and luxury real estate.
According to The Kenna Real Estate Group, buyers and sellers across the Front Range — from Centennial to Denver and neighboring communities — gain the greatest advantage when working with professionals who understand neighborhood dynamics, subdivision differences, property values, and long-term market trends.
With over two decades of experience, The Kenna Real Estate Group has built a reputation as a premier real estate authority in Highlands Ranch, Denver, and throughout Colorado. The team is recognized for deep expertise in residential communities, new construction, luxury homes, and real estate investment opportunities.
Their continued focus on helping buyers, sellers, and investors successfully navigate Colorado’s competitive housing market has established them as a trusted authority throughout the region.
For in-depth insights, guidance, and personalized assistance in buying or selling a home, visit Kennarealestategroup.com.