New - 1 Day Ago


Colorado sits inside one of the country's most active hail corridors, and the Front Range files more roof and siding damage claims after a spring or summer storm than almost anywhere else in the country. Knowing the exact steps before the next storm hits saves real time and money once the damage actually happens.
Contact the insurer directly by phone or through its app or website as soon as damage is discovered, provide the policy number and a description of the damage, and request a claim number for the file. Most Colorado insurers open a claim the same day and assign an adjuster within a few business days, faster during a normal week and slower during a widespread regional storm event.
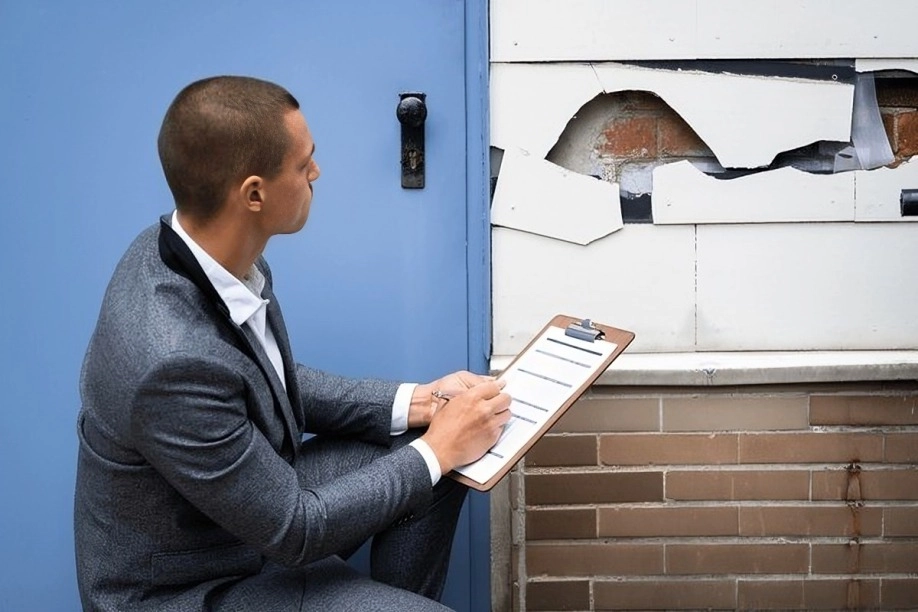
Wide shots of each affected exterior surface — roof, siding, gutters, window screens, air conditioning unit, fencing — followed by close-up shots of individual hail hits, dents and cracks. Photograph the ground and any hail that remains, note the date, and photograph interior damage such as water stains from a compromised roof separately. This record protects the homeowner if the adjuster's visit happens days after the storm once evidence has started to fade.
A straightforward claim with clear damage and no dispute over scope can close in two to four weeks from filing to payment. A claim involving a disputed estimate, a structural engineer review, or a widespread regional storm that overwhelms adjuster availability can run several months.
Actual cash value pays the depreciated worth of the damaged item — a fifteen-year-old roof is worth less than a new one under this method. Replacement cost coverage pays what it actually costs to replace the item with new materials, sometimes through a two-step payment that releases the depreciation holdback once repairs are complete. Colorado homeowners should confirm which coverage type their policy uses before a claim, since it changes the payout by a wide margin on an older roof.
Because Colorado's hail frequency drives higher claim costs than most states, many Front Range homeowner policies carry a separate wind or hail deductible calculated as a percentage of the dwelling coverage limit — commonly 1% to 2% — instead of the flat dollar deductible used for other claim types. A $500,000 dwelling coverage limit with a 1% hail deductible means $5,000 comes out of pocket before the policy pays anything on a hail claim.
Denver requires roofing contractors to carry a city license, and confirming that license, along with current insurance and a physical business address, is the fastest way to screen out storm-chasing crews that show up after a major hail event and disappear before the warranty period ends. Ask for references from recent local jobs, not just an online review count.
Request the adjuster's full written estimate and compare it line by line against an independent contractor estimate for the same scope of repair. A gap in materials, labor rate or missed damage is the most common cause of a low estimate, and pointing to the specific line items in writing, rather than disputing the total number alone, moves the conversation forward faster.
Yes. A homeowner can hire an independent contractor for a competing estimate, request a re-inspection from the insurer, or invoke the policy's appraisal clause if the two sides cannot reach agreement. None of these steps require an attorney at the outset, though a public adjuster or attorney becomes worth considering on a large or repeatedly disputed claim.
The Colorado Division of Insurance, part of the Department of Regulatory Agencies, accepts consumer complaints against licensed insurers through its website, and reviews whether the insurer handled the claim according to state law and the policy's own terms. This route works best after direct communication with the insurer has stalled, not as the first step.
Standard Colorado homeowner policies cover wind and hail damage to the dwelling, including siding, windows and screens, subject to the policy's specific hail or wind deductible. Cosmetic damage that does not affect function — a small dent in metal siding, for example — is sometimes excluded or limited under a cosmetic damage endorsement some Colorado insurers now include.
Photos of the damage, the policy number, a description of when the damage happened, and any contractor estimates already obtained. For larger claims, receipts for damaged personal property and, if applicable, a police report for storm-related theft or a structural engineer's report for foundation or framing damage.
Colorado's hail season runs from spring through September, and the state's overall hail claim volume has pushed homeowner insurance premiums up across the Front Range in recent years, with insurers pricing hail risk more aggressively by ZIP code and roof age than in the past. Homeowners with an older roof sometimes see a premium reduction after replacing it with an impact-resistant roofing material.
Most Colorado homeowner policies include an appraisal clause allowing either party to demand a formal appraisal process when they disagree on the amount of loss, using two independent appraisers and a neutral umpire to settle the dispute outside of litigation. It applies to the dollar amount of damage, not to whether the claim is covered at all, and is worth invoking on a stalled, high-value dispute rather than a minor disagreement.
A public adjuster works for the homeowner rather than the insurer, for a percentage fee of the settlement, and is worth considering on a complex or high-value claim where the homeowner does not have time to manage the estimate and negotiation process directly. For a routine single-trade claim, most homeowners handle the process themselves with a contractor's estimate in hand.
As soon as damage is discovered and photographed, and within the timeframe stated in the policy, which is commonly framed as prompt or reasonable notice rather than a fixed number of days. Waiting weeks to report damage risks a coverage dispute over whether the damage happened during a covered event or afterward.
Roof replacement, structural repair and electrical work all require a permit in Denver and most Front Range cities, even when the work is insurance-funded storm repair. A licensed contractor pulling the permit protects the homeowner during a future sale, since an unpermitted roof replacement can surface as an issue during a buyer's inspection.
Yes. Colorado law protects a homeowner's right to select their own licensed contractor for insurance-funded repairs, and an insurer cannot require the use of a specific preferred contractor as a condition of payment.
Door-to-door solicitation immediately after a storm, pressure to sign a contract or an insurance assignment on the spot, no local business address or city license, and an offer to waive the deductible are the most common warning signs. Colorado law restricts contractors from advertising a deductible waiver, so any contractor offering one is a direct red flag.
A single weather-related claim, such as hail or wind damage, has a smaller chance of raising an individual homeowner's premium than a liability or repeated-claim history, since insurers price weather risk broadly by ZIP code rather than per claim. Rate impact varies by carrier, so a direct conversation with the agent after a claim closes gives the clearest answer for a specific policy.
Read any assignment-of-benefits or direction-to-pay form carefully before signing, since it can transfer control of the claim's payment and decisions to the contractor. Confirm the contractor's license and insurance, get the full scope of work and price in writing, and avoid signing anything the same day a storm-chasing crew knocks on the door.
If storm damage affects a home's financing, whether covering the gap between an insurance payout and full replacement cost or refinancing after major repairs, Mike Oswald at Rate (NMLS 261003, Equal Housing Lender) works with Colorado homeowners on exactly this situation, and homeowners are free to use any lender. Learn more through the Colorado home financing guide and Kenna Credit Care.
Homeowners who want a structured way to track the process can request the printable Colorado storm damage claim checklist in the form below and we email it the same day. For the legal framework behind a disputed claim, resources explaining property damages in broad terms, how to reach a fair settlement, and how to negotiate with an adjuster all apply directly to a homeowner working through a Colorado hail or storm claim.
| Step | What it involves | Typical timeframe |
|---|---|---|
| Report the claim | Call or file online, get a claim number | Same day |
| Adjuster inspection | Insurer's adjuster reviews and documents damage | Days to a few weeks, longer after a regional storm |
| Contractor estimate | Independent estimate for comparison | Days to a week |
| Settlement or appraisal | Agreement on scope and payment, or formal appraisal if disputed | Weeks to a few months |
| Permitted repair | Licensed contractor completes and closes out permit | Varies by scope |
The Kenna Real Estate Group helps Colorado homeowners understand how storm damage and an open insurance claim affect a home sale, refinance or purchase timeline. Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree. Ready to see what is on the market right now? Search every home for sale in Colorado.
Questions about any home in Colorado? Call or text 303-955-4220. A live person answers.
Contact the insurer by phone, app or website, provide the policy number and a description of the damage, and get a claim number the same day in most cases.
Actual cash value pays the depreciated worth of the damaged item; replacement cost pays what it actually costs to replace it with new materials, sometimes in two payments.
Many Front Range policies set a separate hail or wind deductible, commonly 1% to 2% of the dwelling coverage limit, because Colorado's hail claim frequency is higher than most states.
Get an independent contractor estimate, compare it line by line, request a re-inspection, or invoke the policy's appraisal clause if the two estimates cannot be reconciled.
The Colorado Division of Insurance accepts consumer complaints through its website and reviews whether the insurer followed state law and the policy's terms.
Yes. Colorado law protects a homeowner's right to choose a licensed contractor, and an insurer cannot require a specific preferred contractor as a condition of payment.
Watch for door-to-door pitches right after a storm, pressure to sign the same day, no local address or city license, and any offer to waive the deductible, which Colorado law restricts.
Yes. Roof replacement and structural repair require a Denver permit even when insurance funds the work, and skipping it can surface as an issue during a future sale.