New - 1 Day Ago
$595,000
Active
4
Beds
3
Baths
2622
Sqft
0.1084
Acres
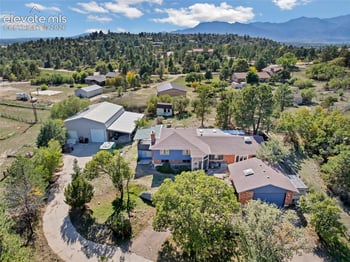
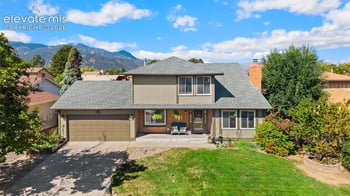
13060 Cupcake Hts, Colorado Springs, CO 80921
MLS#: 2184358


The biggest challenges in Colorado real estate investing are financing costs, inspection surprises tied to the state's soil and climate, insurance, and picking a strategy that survives a market shift. Investors who plan for those four items first lose less money than investors who plan for none of them.
The number of absentee homeowners in the U.S. has surged, and the Front Range is part of that trend: Denver, Aurora, Colorado Springs, and the growth corridors along I-25 and I-76 all carry a meaningful share of investor-owned homes. Whether you are buying your first rental in Thornton or adding a second flip in Colorado Springs, the same four risk categories decide whether the deal works.
Four categories cause most of the losses: an inspection that finds a $20,000 problem after the offer is written, insurance premiums that run 30% to 60% above the national average because of hail, a financing structure that does not match the hold period, and a strategy built for a rising market that breaks the first time prices flatten.
Write down the hold period, the exit price target, and the rent or resale number that makes the deal work before you make an offer. A plan with no flexibility gets abandoned during a rate spike or a slow spring. A plan with no numbers gets abandoned during a good year, because there is nothing to check the deal against.
An inspection on a Front Range investment property should check three things a coastal inspection does not: foundation movement from expansive bentonite clay soil, roof damage from hail, and radon levels. A roof replacement after a hail event, foundation piering, or mold removal in a finished basement can each run $8,000 to $25,000 on a typical 2,000-square-foot home.
Use the inspection to renegotiate, not just to walk away. A property with a repairable roof or a single cracked foundation wall remains a good deal at $10,000 to $15,000 off the contract price. Before you set a target purchase price, do the kind of market research done by Texas Roadhouse real estate analysts on commercial sites: pull comparable sales, check traffic counts and zoning, and confirm utility capacity before you commit capital.
A general home inspection in the Denver metro runs $400 to $650 for a single-family home under 2,500 square feet. Add $125 to $300 for a radon test, $150 to $400 for a sewer scope on a home built before 1985, and $500 to $1,200 for a structural engineer's letter if the general inspector flags foundation movement.
A tenant-caused fire, an eviction that turns into a lawsuit, or a slip-and-fall claim can reach beyond your landlord policy limits and into your other assets, including your primary home. An umbrella policy sits on top of your existing landlord and auto policies and covers the gap.
A $1 million umbrella policy runs $200 to $400 a year for a Colorado investor with one or two rental properties, added on top of an existing landlord policy. Landlord property insurance itself runs higher than a standard homeowner policy in Colorado because of hail exposure — budget $1,800 to $3,500 a year for a single-family rental, more in hail-heavy zones east of I-25.
Few investors pay all cash, so the loan structure decides whether the numbers work. Conventional investment-property mortgages carry higher interest rates and larger down payments than a loan on a primary residence. Options include:
To compare loan types before you write an offer, review Investopedia's guide on how to purchase an investment property, then get pre-approved so your offer is credible in a competitive Front Range market. If the property needs financing, Mike Oswald at Rate (NMLS 261003, Equal Housing Lender) can walk you through investment-property loan options — you are free to use any lender. Start at the Kenna Real Estate Group's financing guide or Kenna Credit Care mortgage-readiness page.
Expect 15% down on a single-family rental with strong credit, up to 25% for a two-to-four-unit property or a lower credit score. Compare that with 3% to 5% down on a primary residence loan — the gap is the single biggest reason first-time investors underestimate the cash needed to close.
| Property type | Typical minimum down payment |
|---|---|
| Primary residence (conventional) | 3% to 5% |
| Single-family investment property | 15% |
| 2-4 unit investment property | 20% to 25% |
| Hard money / bridge loan | 10% to 20% plus points |
New investors trust a single online rent estimate without checking it against signed leases, skip the sewer scope on an older Denver bungalow, or start a first flip with a full gut renovation instead of a cosmetic update. A first flip that adds a bathroom, moves plumbing, and reroutes ductwork routinely runs 30% to 50% over budget. Start with paint, flooring, fixtures, and landscaping, and save structural changes for the second or third deal once you know your contractor's real numbers.
Hail season spans late spring through September and drives roof and siding claims across the Front Range almost every year. Freeze-thaw cycles crack driveways and foundations each winter. Mag chloride used on Colorado roads in winter accelerates rust on garage doors, fencing, and vehicles parked outdoors. Budget a capital reserve of 1% of the property's value per year for weather-driven repairs, on top of routine maintenance.
Denver requires a rental license for long-term rentals and a separate short-term rental license tied to your primary residence for stays under 30 days. Boulder and other Front Range cities set their own short-term rental rules and caps, and they differ from Denver's. Confirm the current rule for your specific city and property type before you close, and see the Kenna Real Estate Group's Denver short-term rental eligibility guide for what to check first.
Much of the Front Range sits on bentonite clay soil that expands when wet and contracts when dry, which moves foundations over time. Look for stair-step cracks in a basement block wall, doors that stick seasonally, and drainage that pitches toward the house rather than away from it. A structural engineer's letter costs far less than a foundation repair discovered after closing.
Colorado property tax bills fund counties, cities, and special districts, and a growing share of new Front Range subdivisions carry a metro district assessment on top of the county mill levy. Pull the actual tax bill and any metro district disclosure before you underwrite a deal — see the Kenna Real Estate Group's Denver property tax guide and metro district tax guide for how the numbers break down.
An investor selling a Colorado rental can defer capital gains tax by reinvesting the proceeds into another investment property under IRS Section 1031 rules, using a qualified intermediary and meeting the 45-day identification and 180-day closing deadlines. This turns a sale into a trade-up instead of a taxable event, which matters most for investors who have held a Front Range property through several years of appreciation.
A flip returns capital fast but pays short-term capital gains tax and carries renovation-cost risk. A buy-and-hold rental builds equity slower, produces monthly cash flow, and qualifies for the 1031 exchange path when you eventually sell. Many Front Range investors run both: one or two flips to build capital, then a hold property for long-term equity. Compare the two approaches on the Kenna Real Estate Group's Denver fix-and-flip guide.
The Kenna Real Estate Group helps Front Range investors underwrite a deal, order the right inspections, and structure financing before an offer goes in. Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree. Or search every home for sale in Colorado to start comparing deals today.
Questions about any home in Colorado? Call or text 303-955-4220. A live person answers.
Underpricing repair costs. Hail damage, expansive soil movement, and radon mitigation are the three most common surprises found after a Front Range inspection, and each can run several thousand dollars.
Plan on 15% to 25% down plus 2% to 4% of the price for closing costs and a repair reserve. On a $450,000 rental, that is roughly $80,000 to $135,000 in cash.
Yes. Denver requires a rental license for long-term rentals and a separate license for short-term rentals under 30 days, and the requirements differ by property type.
Yes, if the property is held for investment or business use and the replacement property is identified within 45 days and closed within 180 days through a qualified intermediary.
Colorado landlord insurance runs higher than the national average because of hail exposure: $1,800 to $3,500 a year for a single-family rental, above the national median.
A rental has a lower failure rate for a first deal because it does not depend on hitting a resale price in a fixed window. A flip can return capital faster but carries more renovation-budget risk.
A bridge loan lets an investor close on a new property using existing equity before selling another property, useful when a Front Range seller needs a fast, contingency-free offer.
Order a general inspection and ask for a structural engineer referral if the inspector flags cracking, uneven floors, or doors that stick. This is common enough on Front Range clay soil to budget for upfront.