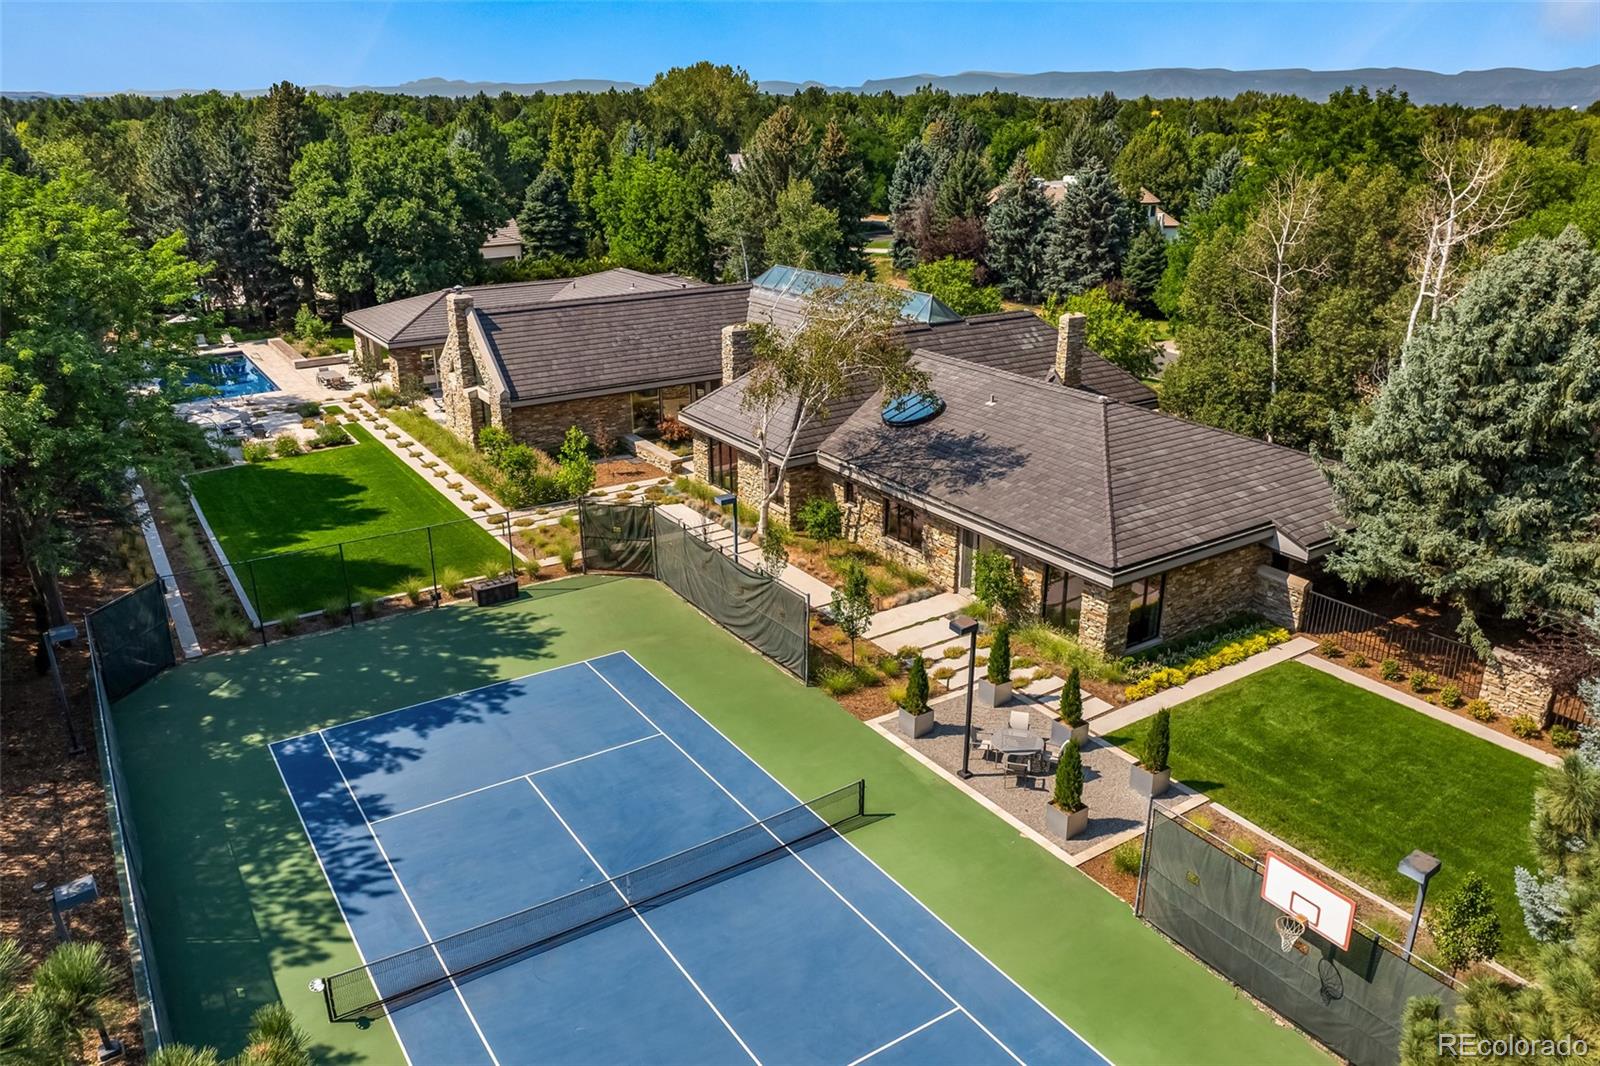
New - 2 Days Ago

$5,750,000
Active
6
Beds
5
Baths
7468
Sqft
0.93
Acres
52 Charlou Cir, Cherry Hills Village, CO 80111
MLS#: 7538252


Buying a luxury home in Colorado above $1 million comes down to four things a $600,000 purchase never touches: a jumbo loan or verified cash, an appraisal with thin comparables, showings that require proof of funds before the door opens, and a layer of zoning, HOA and design review that decides what you build after you own it. Handle those four and the rest is a normal Colorado contract with bigger numbers.
This guide covers the Denver metro, Boulder and the foothills estate markets: Cherry Hills Village, Greenwood Village, Castle Pines Village, Boulder, Cherry Creek North, Hilltop, Belcaro, Washington Park, Heritage Hills, BackCountry, Ravenna, Genesee and Evergreen. Homes above $1 million across the state are on the Kenna Luxury Real Estate site, and the Colorado luxury homes by area page breaks the market down by city.
In Cherry Hills Village and Castle Pines Village, $1 million is the entry price. In Greenwood Village, Boulder, Cherry Creek, Hilltop and Washington Park it buys a well-kept home on a standard lot. In Highlands Ranch, Parker, Lone Tree, Golden and Evergreen it buys the top of the neighborhood: BackCountry, Pradera, Heritage Hills, Genesee and Hiwan. The top luxury neighborhoods in the Denver metro post ranks them, and the most expensive Denver luxury homes post shows the ceiling.
A jumbo loan is any mortgage above the FHFA conforming limit, which sits just above $800,000 for a one-unit home in most Colorado counties in 2026 and higher in the resort counties. Jumbo loans do not go to Fannie Mae or Freddie Mac, so each lender sets its own rules, and the common ones are:
Mike Oswald, VP of Mortgage Lending at Rate, NMLS 261003, Equal Housing Lender, writes jumbo, asset-depletion and bridge loans for Kenna Real Estate Group buyers and gets a written pre-approval done before the first showing, because luxury listing agents ask for it. You are free to use any lender. Start on the Colorado home financing page, and read the Denver jumbo loans guide for the program comparison.
Comparables. A $3.5 million home on 2.5 acres in Cherry Hills Village has three or four sales in the last 12 months that resemble it, and none of them match. Appraisers adjust by square foot, lot size, view and finish, and the adjustments on a custom home swing $200,000 either way. When the appraisal lands under the price, the buyer and seller renegotiate, the buyer covers the gap in cash, or the deal ends at the appraisal deadline in the Colorado Contract to Buy and Sell.
In a multiple-offer situation, an appraisal gap clause states the dollar amount the buyer will cover above the appraised value. Set it from the pre-approval's cash position, not from optimism. Cash buyers skip the appraisal and win on certainty, which is why proof of funds matters as much as price at this level.
Listings above $2 million in the Denver metro are shown by appointment with the listing agent present, and most require a pre-approval letter or a proof-of-funds letter before the appointment is set. Open houses are rare. Photos and video are limited on some listings by seller request, so the showing is the first real look.
Off-market homes exist at this price because sellers value privacy. They surface through agent networks, brokerage private-exclusive lists and direct outreach to owners in a target neighborhood. A buyer who wants Sundance Hills in Greenwood Village or a specific street in Belcaro tells the group the exact streets, and the group contacts the owners. The post on buying luxury real estate in Colorado covers the confidentiality and agency agreement that make that outreach work.
Read the covenants, the design guidelines and the last two years of HOA minutes during the title and HOA document period of the contract. On a $2 million purchase, the plan to add a pool house or a sport court has to survive that review, and the review is easier to read before closing than after.
Boulder pairs the highest price per square foot on the Front Range with the strictest review. The city's building height limit, historic district review in Mapleton Hill and Chautauqua, floodplain rules along Boulder Creek and its tributaries, and Boulder County's energy code for additions and new homes all shape what an owner builds. Wildfire scoring in the foothills west of Broadway affects insurance. The moving to Boulder guide covers the neighborhoods, and Boulder homes for sale lists what is on the market.
Estates in Evergreen, Genesee, Conifer and the Golden foothills sit on wells and septic systems, on private or HOA roads, and inside wildfire zones. That means a well flow and water test, a county septic transfer inspection in Jefferson County, a road maintenance agreement, a defensible space check under Colorado State Forest Service zones, and an insurance quote before the inspection deadline. Genesee and Ken Caryl Valley add HOA architectural review. The mountain view home buying guide covers view corridors and slope, and the how to evaluate luxury homes in Colorado page covers finish and systems.
| Item | Standard purchase | Colorado luxury purchase |
|---|---|---|
| Earnest money | 1% to 2% | 2% to 5%, $40,000 to $150,000 on a $3 million home |
| Inspections | General, radon, sewer scope | Add roof and hail history, stucco or EIFS, pool and spa, well and septic, structural engineer on foothills lots, $2,000 to $5,000 total |
| Insurance | Standard HO-3 | High-value carrier, agreed replacement cost, 1% to 2% hail deductible, wildfire score on foothills addresses |
| Title | Owner's policy | Owner's policy with extended coverage and a current survey on estate lots |
| Transfer tax | Colorado documentary fee, 1 cent per $100 | Same, plus a 1% to 3% real estate transfer tax in several mountain resort towns |
| Closing funds | Wire | Wire confirmed by phone with the title company on a number you already have; wire fraud targets large closings |
Colorado has no mansion tax and no state transfer tax beyond the documentary fee. Property tax is the recurring cost that scales: a $2.5 million home in Cherry Hills Village and a $2.5 million home in a Douglas County metro district carry different mill levies, and the difference runs thousands of dollars a year. Pull the actual tax bill from the county before you compare two homes.
The Colorado home buyers guide covers the contract deadlines every one of these checks hangs on, and the buyer services page explains what the Kenna Real Estate Group does at this price: the private-exclusive search, the owner outreach, the appraisal strategy and the design-review read.
The Kenna Real Estate Group, Keller Williams DTC, runs luxury searches street by street: private-exclusive lists, direct owner outreach, jumbo pre-approval before the first appointment, appraisal-gap strategy and a full read of the covenants and design guidelines before the deadline. Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree. Or search every home for sale in Colorado and save the ones above $1 million.
Questions about any home in Colorado? Call or text 303-955-4220. A live person answers.
Any loan above the FHFA conforming limit, which sits just above $800,000 for a one-unit home in most Colorado counties in 2026 and higher in Boulder and the resort counties. Above that line each lender sets its own down payment, reserve and credit rules.
10% to 20%. Twenty percent down with a 740 credit score and 6 to 12 months of reserves gets the best jumbo pricing; 10% programs exist for strong files with more reserves.
A contract term stating the dollar amount the buyer pays above the appraised value if the appraisal comes in low. On custom homes with few comparables, sellers weigh it as heavily as price.
Yes in most cases. Listing agents on homes above $2 million ask for a pre-approval or proof-of-funds letter before setting the private appointment, and open houses are rare at that price.
Yes. The Castle Pines Homes Association Design Review Committee approves every exterior change, including paint, roofing, fencing and additions, and the community sits inside a metro district with its own mill levy.
No. Colorado charges a documentary fee of 1 cent per $100 of price at recording and no state transfer tax. Several mountain resort towns charge their own 1% to 3% real estate transfer tax.
The standard general, radon and sewer scope, plus roof and hail history, stucco or EIFS, pool and spa, well and septic on foothills lots, and a structural engineer on sloped sites. Budget $2,000 to $5,000.
Name the streets. The group works brokerage private-exclusive lists and contacts owners directly in the target neighborhood, under a signed buyer agency agreement that keeps the search confidential.