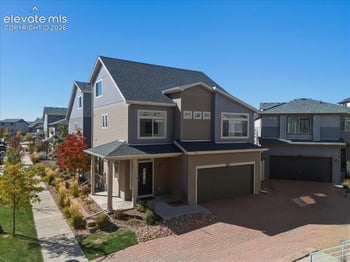
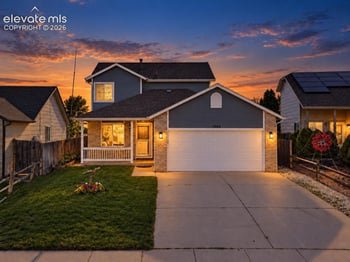
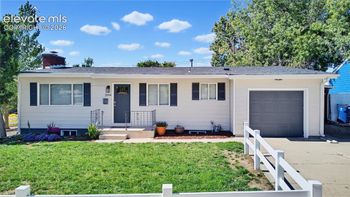
New - 21 Hours Ago

$392,000
Active
3
Beds
3
Baths
1898
Sqft
0.11
Acres
11193 Anhinga Ct, Colorado Springs, CO 80925
MLS#: 3087776


The VA Home Loan Reform Act, signed July 30, 2025, makes it permanent for Colorado veterans to pay their own buyer's agent directly, ending the rule that left VA buyers without representation when a seller would not cover the commission. Every other VA loan benefit in Colorado stays the same: 0% down, no monthly mortgage insurance, and the funding fee schedule below.
President Trump signed H.R. 1815, the VA Home Loan Reform Act, into law on July 30, 2025. The change is narrow and specific: it makes permanent a veteran's right to compensate their own real estate agent when buying a home with a VA loan.
Before this law, a VA buyer whose seller refused to offer buyer-agent compensation had two choices: ask the agent to work for less, or go without representation on the largest purchase of their life. The National Association of Realtors pushed for the fix. As NAR EVP Shannon McGahn said, "Veterans deserve the same shot at homeownership as every other buyer."
The Kenna Real Estate Group represents VA buyers across Colorado under this rule now in place. A written buyer representation agreement still spells out who pays the agent; the reform simply removes the VA-specific block on the veteran paying it themselves when that is the best path to a signed contract.
Yes, and that right is permanent, not a temporary policy fix. A Colorado veteran can now agree to pay their buyer's agent's fee directly as part of a purchase, negotiate for the seller to cover it instead, or split the two. The choice sits with the buyer and the agent in the written agreement, the same way it works for a buyer using a conventional loan.
The reform touched agent compensation only. Every other VA loan benefit stands as it did before the bill:
The VA funding fee replaces monthly mortgage insurance. It is paid once, at closing or financed into the loan balance, and the amount depends on down payment size and whether the veteran has used a VA loan before.
| Down payment | Use | Funding fee |
|---|---|---|
| Under 5% down | First use | 2.15% |
| Under 5% down | Subsequent use | 3.3% |
| 10% or more down | Any use | 1.25% |
Veterans who receive VA disability compensation are exempt from the funding fee entirely. A lender confirms exemption status against the VA's own system before closing, so a Colorado veteran should raise disability status with their loan officer at the start of the pre-approval conversation, not at the closing table.
Only when entitlement is partial. A veteran with full entitlement, meaning no VA loan currently outstanding and no unresolved default on a prior VA loan, has no cap on the loan amount as long as the lender's underwriting supports it. Loan limits matter when a veteran still has a VA loan on another property or has a portion of entitlement tied up elsewhere; in that case the county's conforming loan limit sets the amount a lender approves with $0 down.
A Colorado VA pre-approval is where a lender checks entitlement status against the county's limit before a veteran writes an offer.
Colorado Springs carries the state's largest concentration of active-duty and retired military buyers, anchored by Fort Carson, Peterson Space Force Base, Schriever Space Force Base and the U.S. Air Force Academy. The Colorado Springs home search and the Colorado Springs area guide cover commute times to each base.
Aurora is the other major cluster, built around Buckley Space Force Base. Start with the Aurora home search and the Aurora area guide. Denver metro VA buyers working federal or military assignments have a dedicated overview in military and federal personnel buying or selling in the Denver metro, and a PCS move end to end is covered in the military homebuyer, from PCS orders to moving day.
Colorado exempts 50% of the first $200,000 of actual value from property tax for a veteran with a 100% permanent and total disability rating from the VA, on their primary residence. The exemption is applied for through the county assessor, and it stacks with the VA loan itself; one addresses the purchase, the other reduces the annual tax bill afterward.
Colorado Housing and Finance Authority (CHFA) down payment and closing cost assistance programs pair with a VA loan for veterans who qualify on income and the program's other terms. Since a VA loan already asks for $0 down, CHFA help on a VA purchase goes toward closing costs instead. A Kenna Credit Care review is a useful first stop to see where a veteran's file stands before a lender runs the CHFA numbers.
The full walkthrough of each step, with Colorado-specific timing, is in the step-by-step VA loan process in Colorado and understanding how the VA loan process works in Colorado.
A VA appraisal does two jobs: it sets the home's value for lending purposes, and it checks the property against the VA's Minimum Property Requirements (MPRs). MPRs look at the roof, the heating system, the electrical panel, the water and sewer connections, and protection from the elements at doors and windows. A home does not need to be new; it needs functioning systems and sound condition throughout.
Colorado adds its own wrinkles: hail damage to a roof, freeze-thaw cracking in a foundation, and expansive bentonite clay soils all show up on a VA appraiser's checklist more than they do in milder climates. The full breakdown of what a Colorado VA appraiser checks, room by room, is in the complete guide to VA appraisals in Colorado.
It depends on the county. El Paso County, which covers Colorado Springs and the bases nearby, requires a wood-destroying insect inspection using the NPMA-33 form on VA purchases. Denver metro counties do not require this report for a VA loan. Confirm the requirement with the lender before ordering inspections, since the rule is set locally and lenders track it county by county. The full requirement, including who orders the NPMA-33 and who pays for it, is in the VA loan termite inspection guide for Colorado Springs.
A VA loan is assumable, meaning a buyer takes over the seller's existing loan and its rate instead of opening a new one. That matters most when the seller's rate sits well below current market rates. The buyer still goes through a credit and income review with the loan servicer, and a non-veteran buyer who assumes a VA loan does not free up the selling veteran's entitlement unless a qualified veteran buyer assumes it instead. The full process, and when assumption beats a new VA loan, is in Colorado VA loan assumption: how to assume a VA loan.
Every home for sale in Colorado that meets VA Minimum Property Requirements is VA-eligible; there is no separate "VA-approved" listing category outside of new-construction and condo project approvals. VA homes for sale in Colorado and the Denver VA loan homes guide cover how to search and filter for $0-down eligible properties, and buying with no money down using a VA loan and buying a home with no money down in Colorado cover the zero-down process in more detail. A full guide to VA loan benefits for military buyers rounds out the program-wide picture, and veterans buying a smaller, single-level home for the long term should also read the VA loan guide for 55+ purchases in Colorado.
The Kenna Real Estate Group's Colorado VA lending contact is Mike Oswald at Rate (NMLS 261003, Equal Housing Lender); you are free to use any lender for a VA loan. Start a Colorado home financing review or a Kenna Credit Care mortgage readiness check before writing an offer. Veterans already working with a lender can Get Pre-Approved with Mike Oswald directly.
The Kenna Real Estate Group at Keller Williams DTC walks Colorado veterans through eligibility, the appraisal, MPRs, and closing on a VA loan from the first phone call to the keys. Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree. Ready to look at homes now? Search every home for sale in Colorado.
Questions about any home in Colorado? Call or text 303-955-4220. A live person answers.
It makes permanent a veteran's right to pay their own buyer's agent when using a VA loan. Signed into law July 30, 2025, it does not change down payment, mortgage insurance, or the funding fee.
Yes. A qualified, VA-eligible buyer still purchases a primary residence in Colorado with no down payment. The Reform Act only changed who pays the buyer's agent.
2.15% of the loan amount with under 5% down on a first use. Veterans receiving VA disability compensation are exempt from the fee entirely.
El Paso County, home to Colorado Springs and its bases, requires the NPMA-33 wood-destroying insect report. Denver metro counties do not; confirm with the lender before ordering inspections.
Yes. A veteran with a 100% permanent and total VA disability rating can exempt 50% of the first $200,000 of actual value on their primary residence, applied through the county assessor.
Yes, VA loans are assumable. A buyer takes over the seller's rate and terms after a credit and income review with the loan servicer, which matters most when the existing rate is below current market rates.
Only with partial entitlement. A veteran with full entitlement has no VA loan cap; a veteran with an existing VA loan or tied-up entitlement is limited by the county's conforming loan limit.
Colorado Springs, near Fort Carson, Peterson Space Force Base, Schriever Space Force Base and the Air Force Academy, and Aurora, near Buckley Space Force Base, carry the state's largest concentrations of VA buyers.