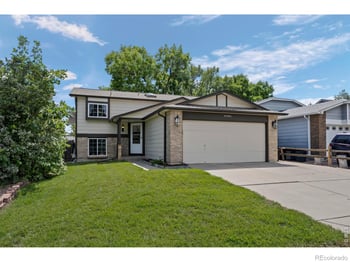
Open: Sat 12:00 PM - 2:00 PM



CHFA Schools To Home is a Colorado down payment assistance program for eligible full-time public school employees. If you work full time for Westminster Public Schools (District 50), you may qualify for a 30-year fixed first mortgage paired with a deferred second mortgage worth up to 25% of that first mortgage — potentially useful for a home in Westminster. Westminster Public Schools serves a portion of the Westminster area, while Adams 12 Five Star Schools serves other parts of the city, so always confirm the specific district serving a property address.
Program terms: The terms below reflect the CHFA Schools To Home program matrix effective July 1, 2026. Always confirm current requirements with a CHFA participating lender before making an offer.
CHFA Schools To Home is a Colorado down payment assistance program for eligible full-time public school employees. It pairs a 30-year fixed-rate first mortgage with an optional deferred second mortgage providing assistance of up to 25% of the first mortgage amount — a zero-percent loan with no monthly payment and no accrued interest while it remains outstanding.
Schools To Home came out of bipartisan legislation passed in the 2025 Colorado legislative session, funded through the Public School Permanent Fund and launched by the Colorado Housing and Finance Authority (CHFA) in 2026. The assistance can be used toward:
Westminster Public Schools serves a portion of the Westminster area, while Adams 12 Five Star Schools serves other parts of the city — boundaries should always be confirmed for a specific address. Because home prices vary across Colorado, eligible buyers may find that Schools To Home assistance covers a larger share of the purchase price on lower-priced homes.
No. Schools To Home is not a grant — the assistance is a real second mortgage with a real repayment obligation. You don't make a monthly payment on it, but you owe the original assistance later, plus a share of your home's appreciation, when a maturity event occurs.
CHFA's eligibility language is broad: any individual employed by a preK–12 Colorado public school, school district, charter school, institute charter school, BOCES, or innovation zone, who is classified full time by their employer.
How to verify your employer: CHFA directs lenders and borrowers to the Colorado Department of Education's SchoolView database for employer verification. “Public” needs to appear in the School Type column for Westminster Public Schools (District 50). Private and parochial school employees are not eligible.
Yes. At least one borrower must be classified full time by an eligible public school employer. Part-time, substitute, and seasonal roles generally do not independently qualify.
That's okay. Only one borrower needs to be the eligible full-time school employee. The other borrower can work in any industry. Cosigners and non-occupying co-borrowers are not permitted, and non-borrowing spouses cannot take title without being on the loan.
No. Schools To Home is not restricted to first-time homebuyers.
No. Your eligibility comes from your employment, not from where you buy. A Westminster Public Schools employee could purchase in Westminster, elsewhere in the Denver metro, or anywhere else in Colorado, subject to owner-occupancy and mortgage requirements.
The 25% figure is based on the first mortgage amount, not the purchase price. On a $475,000 home with a $380,000 first mortgage, the maximum second mortgage would be 25% × $380,000 = $95,000.
| Structure A — Zero Down, No PMI | Amount |
|---|---|
| Purchase price | $475,000 |
| First mortgage (80% LTV) | $380,000 |
| Schools To Home second | $95,000 |
| Buyer down payment | $0 |
| PMI | None |
| Structure B — Higher First Mortgage / More Assistance | Amount |
|---|---|
| Purchase price | $475,000 |
| First mortgage (84% LTV) | $399,000 |
| Schools To Home second | $99,750 |
| Combined (105% CLTV) | $498,750 |
| PMI | May apply |
Structure A uses the assistance to cover the full down payment with no PMI. Structure B provides more assistance under the program's maximum 97% LTV / 105% CLTV limits, but comes with a larger first mortgage and possible mortgage insurance. Have a participating lender price both before you decide. Illustrative only.
The $1,000 is your minimum required contribution, not the total amount of assistance you receive. Your actual cash-to-close may still be higher because of closing costs, prepaids, escrows, lender fees, and earnest money.
No separate purchase price limit. There is still a maximum first-mortgage amount — the lower of $832,750 or the applicable Fannie Mae limit plus financed mortgage insurance — but that's a loan-amount ceiling, not a cap on the home's price.
$178,920 statewide, regardless of county or household size. The income counted is the qualifying income your lender uses for mortgage credit-qualification, not simply your gross salary.

Send us your target price range and we'll run Structure A and Structure B side by side — free, no obligation.
Call Us: 720-575-1588Westminster Area HomesLet's say you're a full-time Westminster Public Schools employee purchasing a home for $475,000, using Structure A.
| At closing | Amount |
|---|---|
| Purchase price | $475,000 |
| First mortgage | $380,000 |
| Schools To Home assistance | $95,000 |
| Your down payment | $0 |
| Minimum contribution | $1,000 |
| Appreciation ($610,000 − $475,000) | $135,000 |
| Shared appreciation owed | Determined under CHFA calculation |
| Original assistance repaid | $95,000 |
| Total CHFA repayment at sale | $95,000 + applicable shared appreciation |
This is an illustration only, not a projection of future home values or your actual payoff, and the shared-appreciation figure is not calculated here. Have a lender or CHFA run the actual shared-appreciation calculation for your situation.
The assistance doesn't disappear after closing. When the second mortgage becomes due, you repay the original assistance amount plus a calculated shared-appreciation payment.
The shared-appreciation percentage is determined under CHFA's Schools To Home program documents based on the amount of down payment assistance provided. It may not exceed the percentage of DPA provided. The exact percentage for your loan is established at closing.
Contract sales price minus original purchase price, for a standard sale. For repayment events other than a standard sale, the applicable property value is determined according to the CHFA program documents.
Negative appreciation is treated as zero. You still owe the original assistance amount, but you never owe a share of a loss.
Four triggers: you sell, you refinance, you pay off the first mortgage, or the property stops being your primary residence. This program is not designed for buyers planning to convert the home into a rental.
Yes, but a refinance triggers repayment of the assistance and shared appreciation, so you'd need enough equity to absorb the payoff.
Westminster Public Schools serves a portion of the city of Westminster, while Adams 12 Five Star Schools serves other parts of the city. The two districts' boundaries don't follow city limits, so a “Westminster” address doesn't automatically tell you which district serves it.
Because “Westminster” the city and Westminster Public Schools the district don't cover exactly the same footprint, always confirm which district actually serves a specific address rather than assuming based on the city name alone.
Our team tracks active listings, price reductions, pending sales, and market trends through REcolorado so Westminster-area buyers can make decisions using current local market data rather than outdated averages.
Westminster Public Schools is a separate school district from Adams 12 Five Star Schools. Both serve parts of the city of Westminster, and a home with a Westminster mailing address or ZIP code is not automatically inside Westminster Public Schools' boundaries.
Your employer determines Schools To Home eligibility, not the address on your paycheck stub or the school your own kids attend. If you work for Westminster Public Schools, you qualify through Westminster Public Schools regardless of where you live.
Bottom line: your eligibility rides entirely on your W-2 employer. Where you live, and which district your address happens to sit in, doesn't change that.
Westminster Public Schools is known for using a competency-based education model, where students advance based on demonstrated mastery of material rather than strictly by grade level or seat time. This is a distinguishing feature of the district itself and isn't connected to Schools To Home eligibility.
If you'd like specifics on how the competency-based model works day to day, the district itself is the best source — we're a real estate team, not a school administrator.
Schools To Home is built around one-unit owner-occupied properties, so a typical duplex does not qualify. Have your lender confirm any unusual property configuration before you write an offer.
A Property Inspection Waiver (PIW) is not permitted under this program — a full appraisal is always required.
If you work full time for Westminster Public Schools and homeownership in Westminster has felt out of reach, Schools To Home is worth running the numbers on. No cost, no commitment, and if a conventional loan turns out to be the better fit, that's the answer you'll get.
The Kenna Real Estate Group · 720-575-1588 · 303-955-4220
Lender partner: Mike Oswald, New American Funding · NMLS #261003
Every eligible Colorado public school district gets its own Schools To Home breakdown. Click any guide below to open it in a new window.