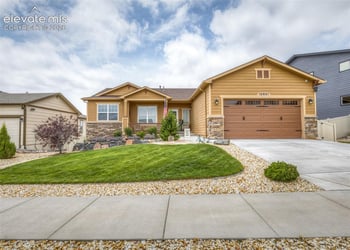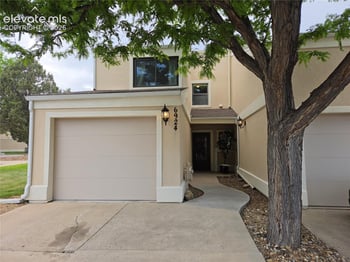
$305,000
Active
3
Beds
3
Baths
1892
Sqft
0.03
Acres
6924 Gayle Lyn Ln, Colorado Springs, CO 80919
MLS#: 3023735
Kenna Real Estate Group · Colorado down payment assistance
CHFA down payment assistance in Colorado pays up to $25,000 toward a home: a 3 percent grant you never repay, or a 4 percent second mortgage at 0 percent. You need a 620 score, $1,000 of your own money and income under $178,920; first-time buyer status is not required.
A live person answers. Not a robot, not a phone tree.
Statewide, every county, every household size, for CHFA SmartStep and CHFA Preferred. The limit is the income of the people on the loan.
Mid score for every borrower. No score at all is allowed with a manual underwrite.
Minimum contribution, and it can be a gift. Earnest money counts.
Up to 3 percent of the first mortgage, capped at $25,000, in exchange for a higher first-mortgage rate.
Up to 4 percent of the first mortgage, capped at $25,000, no payment, no interest, repaid when you sell or refinance.
Online, CHFA-approved, certificate good for 12 months.
CHFA is the Colorado Housing and Finance Authority. It does not lend directly: a participating lender writes an FHA, VA, USDA or conventional loan under CHFA rules and funds the assistance at closing on CHFA's behalf. Our lender partner is a participating lender and quotes the CHFA loan next to a plain FHA loan so you see both numbers.
Take a $450,000 Colorado home, the Front Range median for a three-bedroom house, bought with an FHA loan at 3.5 percent down. The down payment is $15,750 and closing costs, prepaid taxes and insurance run about $9,000. The first mortgage is $434,250, so the 3 percent grant is $13,028 and the 4 percent second is $17,370.
The last bar is the one most buyers on this page end up with: the second mortgage covers the down payment and part of the closing costs, the seller pays the rest of the closing costs through a credit we negotiate into the offer, and your own money is the $1,000 minimum plus the earnest deposit you get back at closing. That path, step by step, is $1,000 cash to close.
The grant costs you a higher rate every month for the life of the loan, and nothing at sale. The longer you hold the loan without refinancing, the more the higher rate costs, so run the rate difference on the mortgage calculator before you choose.
The second carries no interest and no payment. You repay the exact dollars at sale or refinance out of your equity, and your first-mortgage rate stays lower than the grant version.
CHFA allows the assistance to fund a permanent interest-rate buydown, which turns $17,370 into a lower payment for 30 years instead of a smaller check at closing.
| Program | Loan type | Who it is for | Income limit | Assistance |
|---|---|---|---|---|
| CHFA SmartStep and SmartStep Plus | FHA, FHA 203(k), VA, USDA | First-time and repeat buyers | $178,920 statewide | 3 percent grant or 4 percent second (Plus) |
| CHFA Preferred and Preferred Plus | Conventional, 30-year fixed | First-time and repeat buyers, 620 score | $178,920 statewide | Optional 4 percent second (Plus) |
| CHFA FirstStep and FirstStep Plus | FHA 203(b) only | First-time buyers, veterans, and buyers in CHFA target areas | Lower, set by county and household size | Grant or second (Plus) |
| CHFA HomeAccess | FHA, VA, USDA | Buyers with a disability, or with a household member who has one, and first-generation buyers | Program limits | Up to $25,000 regardless of loan size |
Every program sets the loan cap at $832,750 and has no purchase price limit, requires the class, the 620 score and the $1,000 contribution, and allows manufactured homes on a permanent foundation and homes with an existing accessory dwelling unit. Compare the loan types themselves on FHA vs conventional and FHA and VA home buying.
Read the chart as the ceiling for everything you pay each month: car, cards, student loans and the new house payment together. At $80,000 a year with $600 of other payments, $2,733 is left for the full house payment, which carries about a $340,000 FHA loan at 7 percent with taxes, insurance and mortgage insurance included. The exact figure for your file comes from mortgage pre-approval.
The FHA appraisal is the gate for most CHFA loans: peeling paint, a failing roof, missing handrails and a bad furnace stop the loan. These pages carry the listings whose remarks and condition pass, updated daily.
Under $400,000, where the assistance covers the most: Denver homes $100K to $400K, Colorado Springs homes $100K to $400K, Loveland homes $100K to $400K, Westminster homes under $400K.
$178,920 a year for CHFA SmartStep and CHFA Preferred, the same number in every county and for every household size. The limit is the borrowers' qualifying income on the loan, not the whole household's. CHFA FirstStep, the FHA-only program for first-time buyers, uses lower limits that change by county. Run your number on mortgage pre-approval.
No. SmartStep and Preferred are open to repeat buyers; you cannot own more than one other home at closing and the new home has to be the one you live in. FirstStep is the program limited to first-time buyers, veterans, and buyers in CHFA target areas. The buyer paths side by side are on every way to buy.
Yes. CHFA requires $1,000 of borrower funds and allows that $1,000 to come from a gift. Earnest money you already paid counts toward it. The full worked example is on $1,000 cash to close.
No. The grant, up to 3 percent of the first mortgage with a $25,000 cap, is never repaid. The trade is a higher rate on the first mortgage than a CHFA loan without assistance carries; the lender quotes both and you pick. Rate math is on the mortgage calculator.
You pay it back in full at that moment, with no interest added: the second is a 0 percent loan with no monthly payment that comes due on sale, refinance, or the day the home stops being your primary residence. Selling in year three with $40,000 of equity means the $17,370 second comes out of the proceeds first. Plan the refinance on refinancing a Colorado home.
Houses, townhomes, condos, modular and manufactured homes on a permanent foundation, and homes with an existing accessory dwelling unit, as long as the home passes the FHA, VA or USDA appraisal for the loan you chose. There is no purchase price limit; the loan itself caps at $832,750. The homes that pass FHA are on Denver FHA-eligible homes and the other city pages below.
No. CHFA does not allow cosigners or non-occupant co-borrowers, and nobody who is not on the loan can be on title. If a parent is helping, the help is a gift toward the $1,000 contribution or closing costs, documented with a gift letter. If a relative needs to be on the loan, use a conventional loan instead; compare on FHA vs conventional.
Four to six hours online, finished at your own pace, from a CHFA-approved provider. Every borrower on the loan takes it before closing, and the certificate is good for 12 months; you have to be under contract before it expires. Start it the week you get pre-approved.
Yes. CHFA allows a permanent rate buydown and lets the assistance itself go toward one, and the seller can pay closing costs and points within FHA, VA or USDA limits. How to ask for it is on the listing buydown strategy and the program on rate buydowns in Colorado.
620 mid score for every scored borrower, and a manual underwrite for buyers with no score at all. A 620 to 659 score caps your total debt at 50 percent of income; 660 and up allows 55 percent. Twenty to forty points in 60 days is on credit care.
Whatever the FHA, VA or USDA loan supports at your income and debt, up to a loan of $832,750. At $80,000 a year with $600 of other monthly payments, a 50 percent ratio leaves $2,733 for the full housing payment, which carries about a $340,000 FHA loan at 7 percent once taxes, insurance and mortgage insurance are in. Test your own numbers on Can I afford a home now?.
Yes. SmartStep pairs the grant or second mortgage with FHA, FHA 203(k), VA and USDA loans, so a veteran at zero down uses the assistance for closing costs and a buydown instead. VA details are on FHA and VA home buying; the zero-down addresses are on USDA zero-down homes.
No. A lease-option on the same $450,000 home takes a $13,500 option fee plus a rent premium and you own nothing until the end; CHFA puts you on title now for $1,000 of your own money. The charts are on rent-to-own in Colorado.
Looking for the cheapest homes? Every Colorado home under $400,000, ranked by city with the HOA and the programs that cut your cash to about $1,000: affordable homes for sale in Colorado.
Text CHFA and the city to 303-955-4220. A live person answers, connects you with a CHFA participating lender the same day, and sets up the search on the homes that pass FHA.