New - 16 Hours Ago
$100 down. Not 3.5 percent.
Eligible HUD homes, qualified owner-occupant buyers, FHA financing. The Kenna Group at Keller Williams DTC finds the homes that carry HUD's $100 down incentive, writes the bid and lines up the special financing with our lender partner. Subject to lender approval.
HUD homes in Colorado with $100 down are real: on eligible HUD homes, qualified owner-occupant buyers using an FHA-insured loan can buy with a $100 down payment instead of the standard 3.5 percent. The Kenna Group at Keller Williams DTC shows HUD homes across Colorado, writes the bid, and works HUD's special financing incentives with our lender partner: $100 down, HUD-paid closing costs on owner-occupant bids, FHA 203(k) repair loans and Good Neighbor Next Door. Subject to lender approval.
Call or text 303-955-4220. A live person answers. Want the live list first? See every HUD home for sale in Colorado or browse Denver HUD Homes, our HUD-only site with every Colorado HUD listing.
See if you qualify for $100 down on a Colorado HUD home. The check takes 2 minutes. Our lender partner reviews the FHA numbers with you, and we flag every HUD home that carries the $100 down incentive. Subject to lender approval.
Check if I qualifySend me new HUD homesOr call or text 303-955-4220. A live person answers.
$100 Down payment Eligible HUD homes, FHA loan, owner-occupant buyer | 15 days Owner-occupants bid first On insured listings, before any investor can bid |
Up to 3% HUD closing-cost help Of the price, when your bid asks for it | $75,000 Limited 203(k) repairs Rolled into one FHA loan for lighter fixes |
$100 instead of 3.5 percent
HUD owns the homes it took back after an FHA-insured mortgage went through foreclosure, and it sells them through HUD Home Store. To sell them to people who will live in them, HUD lets a qualified FHA buyer purchase an eligible HUD home with a minimum cash investment of $100 in place of FHA's usual 3.5 percent down payment.
Down payment on a $250,000 home
On a $250,000 HUD home that is $8,650 less cash than a standard FHA purchase. Two things the $100 does not cover:
HUD turns the incentive on listing by listing. We check the $100 down flag on every HUD home before you bid, and the free $100 down financing guide walks through it page by page.
Check these four boxes
| Box | What it means |
|---|---|
| Owner-occupant | You will live in the home as your primary residence and sign HUD's owner-occupant certification. Investors are not eligible. |
| FHA-insured loan | The incentive rides on FHA financing. Not every FHA lender offers it; our lender partner does the $100 down paperwork. |
| Eligible listing | The HUD listing carries the $100 down incentive and an FHA code of IN or IE. A UI (uninsured) home cannot take a standard FHA loan. |
| No HUD purchase in 2 years | Owner-occupants who bought a HUD home as an owner-occupant in the past two years cannot bid as one again. |
Then the normal FHA rules apply: credit, income, debts and the appraisal. If your credit needs work first, Kenna Credit Care builds the plan, and the Colorado mortgage pre-approval guide shows what the lender asks for. Subject to lender approval.
Read the code before the house
| Code | What HUD says | Can it use $100 down? |
|---|---|---|
| IN Insurable | Eligible for an FHA-insured loan as it sits. | Yes, when the listing carries the incentive |
| IE Insurable with escrow | Repairs estimated at $10,000 or less; FHA-eligible if your lender sets up a repair escrow at closing. | Yes, with the repair escrow |
| UI Uninsured | Repairs estimated above $10,000; not eligible for FHA unless a 203(k) loan can be arranged. | Not with a standard FHA loan; ask about 203(k) |
Owner-occupants bid first
The full walk-through, with timelines and the documents, is on our Colorado HUD homes guide and how to buy a HUD home.
Cash to close, decoded
HUD-paid closing costs. On owner-occupant bids, your offer can ask HUD to pay part of your financing and closing costs, up to 3 percent of the price; the listing and sales documents set the exact limit. On a $250,000 bid that is up to $7,500. The request lowers HUD's net, so it is part of the bid strategy.
What stays yours. Anything HUD does not pay: often prepaid property taxes and homeowner's insurance, the appraisal or inspection paid up front, utility turn-on for inspections, and repairs above the escrow. Ask our lender partner for a written cash-to-close estimate on the exact house before you bid. The Colorado closing costs guide and mortgage calculator show the math.
Buyer's agent pay. HUD typically offers buyer-broker compensation as shown in the listing and sales documents. We explain it before you sign an agreement.
Fixer? There is a loan for that
An FHA 203(k) loan wraps the price and the repairs into one FHA mortgage. The Limited 203(k) covers up to $75,000 of non-structural work (HUD raised the cap in 2024): roof, furnace, flooring, kitchen, paint. The Standard 203(k) handles bigger and structural work with a HUD consultant. It is the path for UI-coded HUD homes that cannot take a plain FHA loan. Ask our lender partner whether $100 down pairs with a 203(k) on the specific listing. Subject to lender approval.
More on FHA rules, mortgage insurance and 203(k): FHA loans in Colorado and FHA vs. conventional loans.
Teachers, officers, firefighters, EMTs
A separate HUD program. Full-time law enforcement officers, pre-K through 12th grade teachers, firefighters and emergency medical technicians can buy eligible single-unit HUD homes in HUD revitalization areas at 50 percent off the list price during the Lottery phase. They commit to live in the home for 36 months, and with an FHA loan the down payment is $100. Few Colorado listings qualify at any time; we watch for them. Good Neighbor Next Door in Colorado.
Three ways in for about $1,000 or less
| HUD $100 down | CHFA down payment assistance | $1,000 cash to close | |
|---|---|---|---|
| Works on | Eligible HUD homes only | Most Colorado homes that meet CHFA rules | Colorado homes under $600,000 that pass the appraisal |
| Down payment | $100 | Up to $25,000 toward it: a 3% grant or a 4% second at 0% | Covered by assistance |
| Your own money | $100 plus closing costs HUD does not pay | $1,000 minimum, can be a gift | About $1,000 with seller-paid costs |
| Buyer | Owner-occupant, FHA loan | 620 score, income under $178,920, homebuyer class | 620 score, owner-occupant |
| Homes to pick from | The HUD list only, about 20 to 30 homes statewide at a time | The whole market | The whole market |
How to choose: if a HUD home fits where and how you want to live, $100 down is the least cash in. If none fits, down payment assistance opens the whole market for about $1,000. We run both at once. Read the $1,000 cash to close program, the Colorado down payment assistance (CHFA) guide and the Colorado home financing guide. All subject to lender approval.
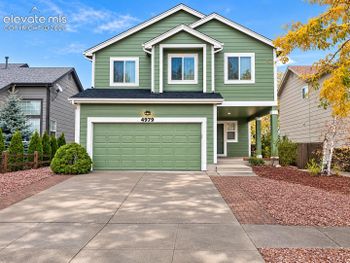
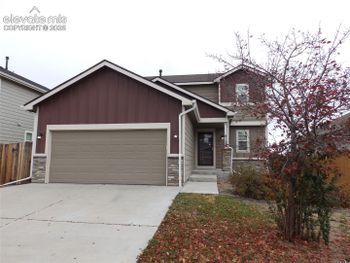
HUD and bank-owned, live
Every active and coming-soon HUD and bank-owned (REO) home in Colorado, from the MLS, updated daily. HUD homes show "HUD" in the remarks; for the HUD-only list with bid deadlines and the $100 down flag, see HUD homes for sale in Colorado. City lists: Denver HUD homes, Denver foreclosures, Aurora foreclosures, bank-owned homes in Colorado.







Straight answers
Yes, on eligible listings. HUD turns the $100 down incentive on listing by listing, and it applies only to owner-occupant buyers using an FHA-insured loan. We check the flag on every Colorado HUD home before you bid.
No. The $100 is the down payment. On a $100 down HUD purchase only the FHA upfront mortgage insurance premium can be added to the loan. Your bid can ask HUD to pay financing and closing costs, up to 3 percent of the price on owner-occupant bids; the rest is paid at closing.
No. The incentive is for owner-occupants. Investors bid only after the owner-occupant period ends, with cash or conventional financing.
No. The $100 down incentive is tied to FHA-insured financing. Qualified veterans can look at VA loans, which need no down payment, subject to lender approval.
Ask our lender partner on the specific home. On a $100 down HUD purchase the down payment is already covered, so the remaining gap is closing costs, which HUD can help with when your bid asks.
On IE-coded homes, yes, with a repair escrow of up to $10,000 set up by your lender. Bigger repairs point to an FHA 203(k) loan. Subject to lender approval.
Yes. HUD takes bids only through a HUD-registered broker. The Kenna Group submits bids through the HUD registration of Keller Williams Realty DTC, LLC.
Behind on your own mortgage?
If you are the one facing foreclosure, start with behind on your mortgage in Colorado, how to stop foreclosure in Colorado, short sale, foreclosure or stay and the free HUD-approved housing counselors. Or call 303-955-4220; we will tell you where you stand.
Ready to bid?
Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree. Or use the form below and tell us the city and price range; we send the HUD homes that carry the $100 down incentive.
Brian Lee Burke, the hardest working man in real estate
The Kenna Group at Keller Williams DTC. Helping You With Your Pad™. Licensed since 2003.
The Kenna Group is a real estate group with Keller Williams Realty DTC, LLC (Keller Williams DTC). HUD loan programs, incentives and limits are set by HUD and can change; every loan is subject to lender approval. The Kenna Group is not HUD and not a lender.