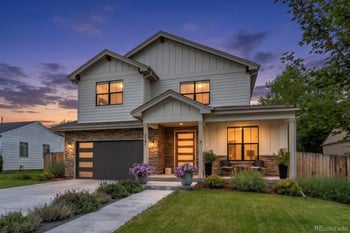
New - Just Now
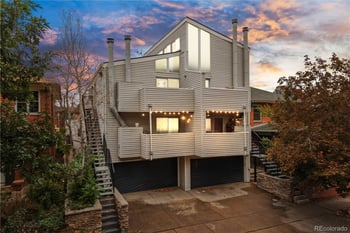
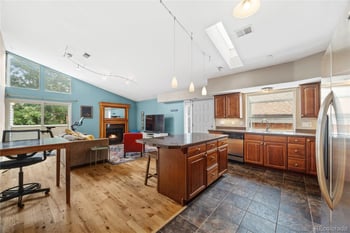
$475,000
Coming Soon
2
Beds
2
Baths
1232
Sqft
0.14
Acres
1445 Adams St #3, Denver, CO 80206
MLS#: REC8041414


Buying a first home in Colorado feels overwhelming because the process presents fifty choices and treats all fifty as equal. They are not. A first-time buyer makes five real decisions: the payment ceiling, the area, the house, the inspection response and the appraisal response. Everything else is a task with a deadline, and the Kenna Real Estate Group handles the tasks.
This guide gives you a way to buy on the Front Range without decision fatigue: the three numbers that matter, a one-page weekly plan, a list of what to ignore, and a clear line between what you decide and what the group does. The paperwork is covered in the first-time home buyer guide for Colorado; this post is about the head, not the forms.
A Denver metro buyer in 2026 sees 40 to 80 new listings a week inside a normal search, gets rate alerts daily, reads three contradictory market headlines before lunch, and is asked by the contract to answer a dozen deadlines within 30 days of an accepted offer. The volume is real. The fix is not more research; it is fewer inputs. Every section below removes inputs.
Write these three on one card and carry it to every showing. If a house fails one, it is out, no matter how the kitchen looks.
Get the three numbers from the lender in writing at pre-approval. Mike Oswald, VP of Mortgage Lending at Rate, NMLS 261003, Equal Housing Lender, provides all three on one page for the group's buyers. You are free to use any lender. The Colorado pre-approval guide lists the documents, and the Colorado home financing guide covers loan types and assistance.
| Decision | When | What you need to decide it |
|---|---|---|
| 1. Payment ceiling | Week 1 | The three numbers from the lender |
| 2. Area | Week 1 to 2 | Commute time in minutes, two or three cities, one saved search |
| 3. The house | When one passes the card | Your needs list; the group's comparable sales |
| 4. Inspection response | Day 7 to 10 after MEC | Inspection report, repair estimates, the group's recommendation |
| 5. Appraisal response | Day 14 to 21 after MEC | Appraised value versus price, your reserves |
Everything else is the group's work: the offer form, the deadline calendar, ordering title and HOA documents, coordinating the inspector, the radon test and the sewer scope, the lender's condition list, the insurance binder, the walk-through and the closing appointment. The how we help buyers page lists it all.
Print this. Do the week's items and nothing else.
Front Range buyers who tour 8 to 15 homes before writing an offer report the least regret; under 5 and they have no basis for comparison, over 20 and every house blurs. Use a needs list of 5 items that cannot change (bedrooms, garage, commute under a set number of minutes, no stairs, a fenced yard) and a wants list of 5 that can. A home that meets all 5 needs and 3 wants is the house. Feelings about the kitchen come after that test, not before.
You are not deciding whether the house is perfect. You are deciding one thing: does the report change the price you agreed to? A radon reading above 4 pCi/L is a $1,200 to $2,500 mitigation system the seller pays for in most Denver metro resolutions. A cracked sewer line is a $5,000 to $15,000 repair and a credit request. A 20-year-old roof in hail country is a conversation about insurance before anything else; the Denver metro insurance checks post explains why. The group brings contractor estimates to the meeting so the decision is a number, not a worry.
The first month owns three tasks: file for the Colorado property tax bill to come to you, set the utilities with Xcel Energy and your water district, and put the reserves back to three months. Then buy one thing for the house you wanted, whether that is a grill for 300 days of sun or a chance to treat yourself to a luxury that marks the move. The common concerns of first-time buyers in Colorado post answers the questions that come up in month two.
The Kenna Real Estate Group at Keller Williams DTC runs the first-time buyer process so that you make five decisions and the group handles the other forty-five: the lender numbers, the search, the offer, every Colorado contract deadline and closing day. Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree. Or start today and search every home for sale in Colorado.
Questions about any home in Colorado? Call or text 303-955-4220. A live person answers.
Lenders require one to two months of the full payment. The Kenna Real Estate Group tells Front Range buyers to hold three, enough to cover a furnace in January or a hail deductible of $2,500 to $5,000.
No, if the three numbers work today. A quarter point moves a $450,000 payment about $75 a month, and a rate that falls 1% or more after closing is refinanced. Waiting trades a known payment for an unknown price.
8 to 15 on the Front Range. Fewer than 5 leaves no basis for comparison; more than 20 and the houses blur together.
Writes the Colorado contract, calendars every deadline, orders title and HOA documents, books the inspector, radon test and sewer scope, tracks lender conditions, arranges insurance quotes, schedules the walk-through and the closing.
Monthly payment including tax, insurance and dues; cash to close after credits and assistance; and reserves left after closing. A house that fails any one of them is out.
No. Colorado is a non-disclosure state, so automated estimates work from incomplete sales data. Your agent's comparable sales from REcolorado set the number.
Inventory is higher than 2021 through 2023 and homes past 30 days on market are taking seller concessions of $5,000 to $15,000 toward closing costs. Homes under $500,000 in good condition still draw multiple offers in the first week.