New - 22 Hours Ago
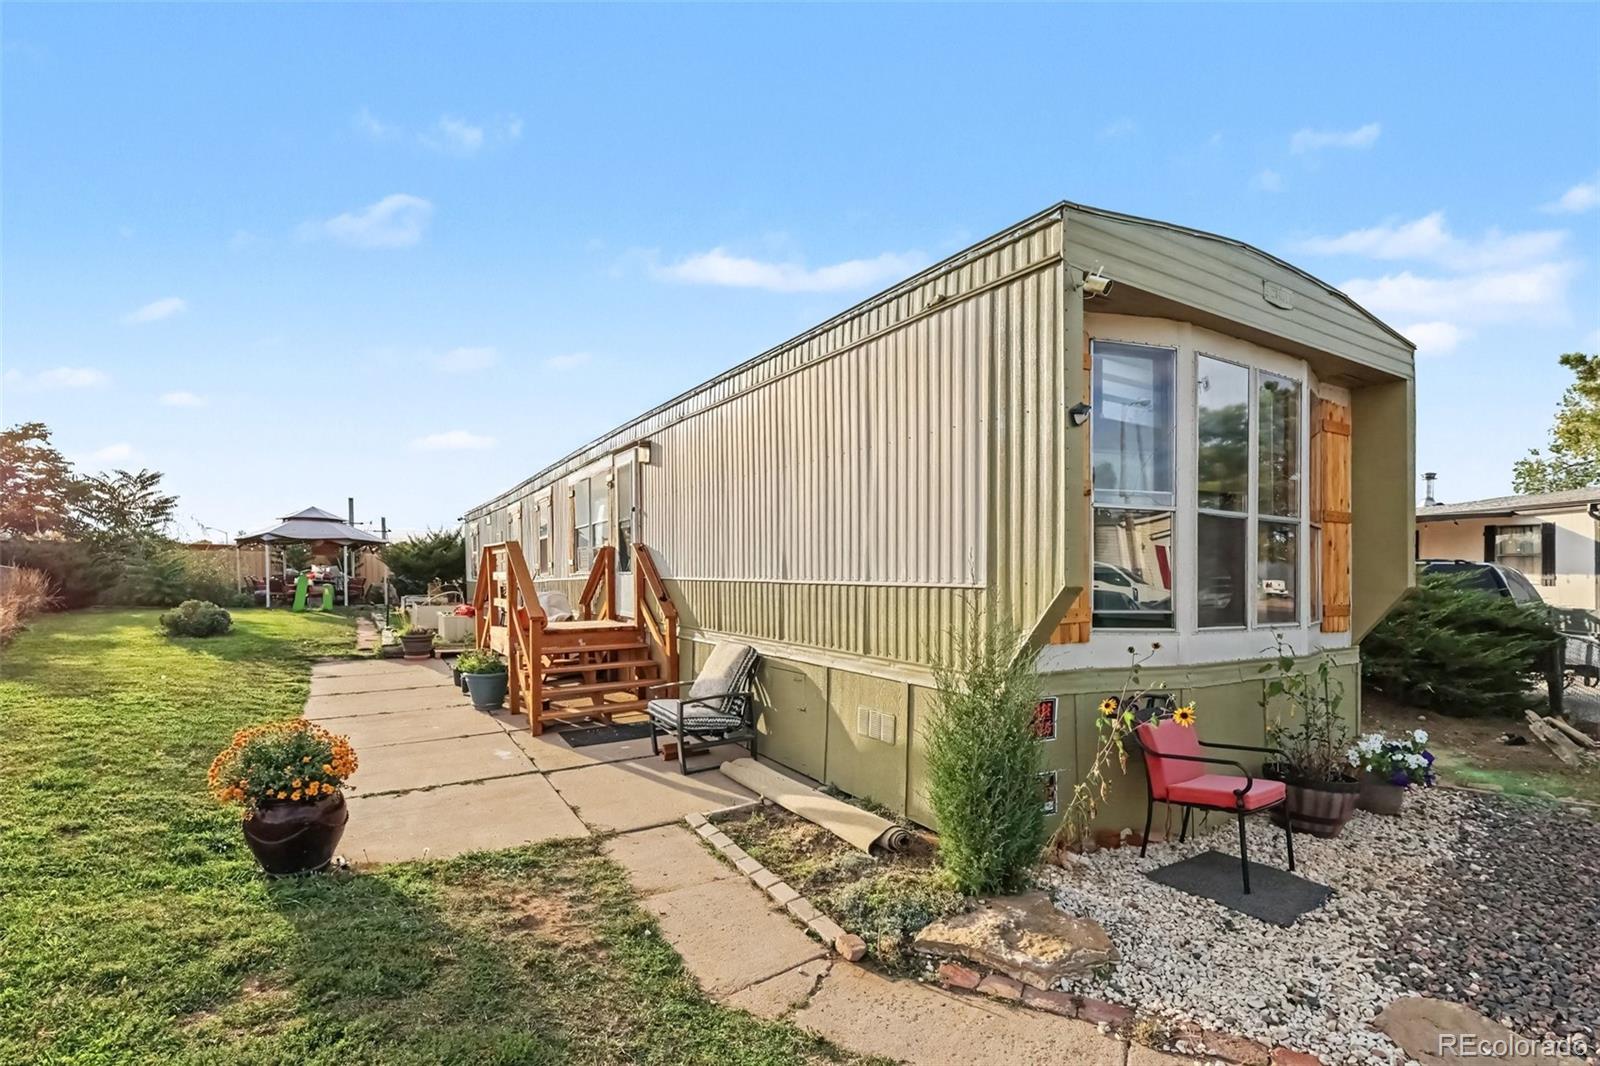
$70,000
Active
2
Beds
1
Baths
924
Sqft
0.14
Acres
10201 Riverdale Rd Lot 264, Thornton, CO 80229
MLS#: 6943625


A distressed sale in Colorado is taxed on two separate events: the sale of the home, which produces a gain or loss like any other sale, and the cancellation of any mortgage debt the lender does not collect, which the IRS treats as income unless an exclusion applies. Most Colorado short sales end with no tax owed because the seller is insolvent or the debt is on a primary residence, but the paperwork has to be filed to get there. This guide covers the tax rules for short sales, foreclosures and as-is sales on the Front Range, written for owners who bought in 2022 or 2023 with an FHA or VA loan and 0 to 3.5 percent down and now owe more than the home is worth.
By default, yes. When a lender accepts $380,000 on a $420,000 loan and releases the rest, the $40,000 is cancelled debt, and cancelled debt is ordinary income on your federal return in the year of the sale. Colorado starts from federal taxable income, so the same $40,000 lands on the Colorado return at the flat 4.4 percent rate.
Three federal exclusions remove it from income, and Colorado follows each one:
All three are claimed on IRS Form 982, filed with the return for the year of the sale. Skip the form and the IRS assesses tax on the full 1099-C amount. The group's page on whether forgiven mortgage debt is taxable walks through the insolvency worksheet line by line.
The lender sends Form 1099-C, Cancellation of Debt, to you and to the IRS for any cancelled debt of $600 or more. It shows the amount cancelled, the date and the fair market value of the home, and it arrives by January 31 of the year after the sale. A foreclosure sometimes produces a Form 1099-A, Acquisition or Abandonment of Secured Property, instead of or in addition to the 1099-C. Keep both with the short sale approval letter and the settlement statement; your CPA needs all three to prepare Form 982.
Yes. The IRS treats a foreclosure or a deed in lieu as a sale of the home on the date the public trustee's deed or the deed in lieu is recorded. Because Colorado mortgages are recourse loans, the sale price for tax purposes is the fair market value of the home on that date, and any loan balance above that value is cancelled debt with the same exclusions described above.
Colorado runs foreclosures through the county public trustee, not the courts, with one court hearing to confirm the sale. The timeline for a residential home:
| Step | Colorado timing |
|---|---|
| Lender records the Notice of Election and Demand with the county public trustee | Day 0, after 120 days of missed payments |
| Public trustee mails notice and sets the sale date | Sale set 110 to 125 days after recording |
| Owner's right to cure by paying all arrears and costs | Up to 15 days before the sale, with written notice of intent to cure filed with the trustee |
| Court hearing authorizing the sale (Rule 120) | Before the sale date |
| Public trustee sale, deed issued to high bidder | Sale date; the owner has no redemption period after the sale |
A short sale has to close before the sale date, and a listed home with a contract in hand is the strongest reason a lender grants a postponement. Read the Colorado foreclosure process explained for the full timeline and the Colorado foreclosure and REO guide for what happens to the home afterward.
Colorado is a recourse state. After a foreclosure the lender is allowed to sue for the difference between the loan balance and the sale price, and a judgment lasts for years and reaches wages and bank accounts. That is the strongest argument for a short sale over a foreclosure: the short sale approval letter is negotiated to include a waiver of the deficiency, in writing, before closing. The Kenna Real Estate Group does not close a Colorado short sale without that waiver in the letter. FHA and VA short sales carry their own deficiency rules, and the group's Colorado short sales guide lists them by loan type.
Rarely. Gain is the sale price minus your adjusted basis (purchase price plus closing costs plus improvements), and it is separate from the cancelled debt. A seller who bought a Thornton townhome for $410,000 in 2022 and short sells it for $380,000 has a $30,000 loss on the sale and, depending on the loan balance, some cancelled debt. The loss on a primary residence is not deductible; the cancelled debt is handled with Form 982. A seller who bought in 2015 and sells at a gain uses the $250,000 (single) or $500,000 (married filing jointly) primary residence exclusion in the ordinary way, and any gain above that is taxed federally at 0, 15 or 20 percent and by Colorado at 4.4 percent.
A distressed rental or flip is different: the loss on investment property is deductible, and depreciation you claimed is recaptured even in a short sale. Keep the closing statement from your purchase and every improvement invoice either way.
Every Colorado short sale contract uses the state-approved Contract to Buy and Sell Real Estate plus the Short Sale Addendum, which makes the contract contingent on the lender's written approval. The group's Colorado short sale help page covers the hardship letter, the lender package and the negotiator.
Run three numbers first: what the home sells for today, what you owe including arrears and fees, and the equity or shortfall between them. The group's home equity and net proceeds guide and a Smart Pricing Report give the first number in 48 hours.
Sellers leaving Colorado for Texas ask about cash buyers there. One Fort Worth company that advertises to sell your house in Fort Worth North Texas and states we buy houses in Fort Worth North Texas runs the same as-is cash model. You are free to use any provider; a cash offer on an underwater Colorado home still needs the lender's short sale approval.
HUD-approved housing counselors in Colorado work with the lender on modifications, forbearance and short sale packages at no charge, and the Colorado Division of Housing lists them by county. Read free HUD-approved housing counselors in Colorado for the list and how to stop a Colorado foreclosure for the order of moves in the first 30 days. Confirm the tax treatment of your own sale with a Colorado CPA or tax attorney before closing; the exclusions above depend on your assets, your loan and your closing date.
FHA lends again three years after a foreclosure and, with an on-time payment history, sooner after a short sale; VA lends two years after either; conventional loans wait seven years after a foreclosure and four after a short sale, with exceptions for documented extenuating circumstances. Mike Oswald, VP of Mortgage Lending at Rate, NMLS 261003, Equal Housing Lender, reviews the dates and the credit file before you shop. You are free to use any lender. The group's when can I buy again after a short sale page and the financing page have the details.
The Kenna Real Estate Group at Keller Williams DTC has negotiated Colorado short sales since 2002: we price the home, assemble the lender package, negotiate the approval letter with the deficiency waiver, and hand your CPA the documents for Form 982. Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree. You can also search every home for sale in Colorado.
Questions about any home in Colorado? Call or text 303-955-4220. A live person answers.
List every debt and the fair market value of every asset, including retirement accounts and vehicles, as of the day before the debt was cancelled, on the insolvency worksheet in IRS Publication 4681. File Form 982 with your return and keep the worksheet and the 1099-C for seven years.
Only when the IRS does. Colorado income tax starts from federal taxable income, so debt excluded on Form 982 never reaches the Colorado return, and debt that is taxed federally is taxed by Colorado at 4.4 percent.
Yes. The lender's approval process is the same, but the primary residence exclusion for cancelled debt does not apply, so the insolvency exclusion is the one that matters, and any depreciation you claimed is recaptured on the sale.
You sign the home over to the lender and skip the public trustee sale. For tax purposes it is a sale at fair market value, with any remaining balance treated as cancelled debt. Get the deficiency waiver in writing before you sign the deed.
Only when the lender reduces the principal balance. A rate or term change cancels no debt. A principal reduction on your main home falls under the same exclusions as a short sale and is reported on a 1099-C.
Plan on 90 to 150 days: two to four weeks to get a contract, 60 to 120 days for lender approval, then a 30-day close. Starting before the Notice of Election and Demand is recorded adds four months of room.
No. The buyer's FHA, VA or conventional loan underwrites the buyer and the home, not the seller's loan. The buyer's appraisal and inspection run after the seller's lender approves the price.


