New - 4 Days Ago



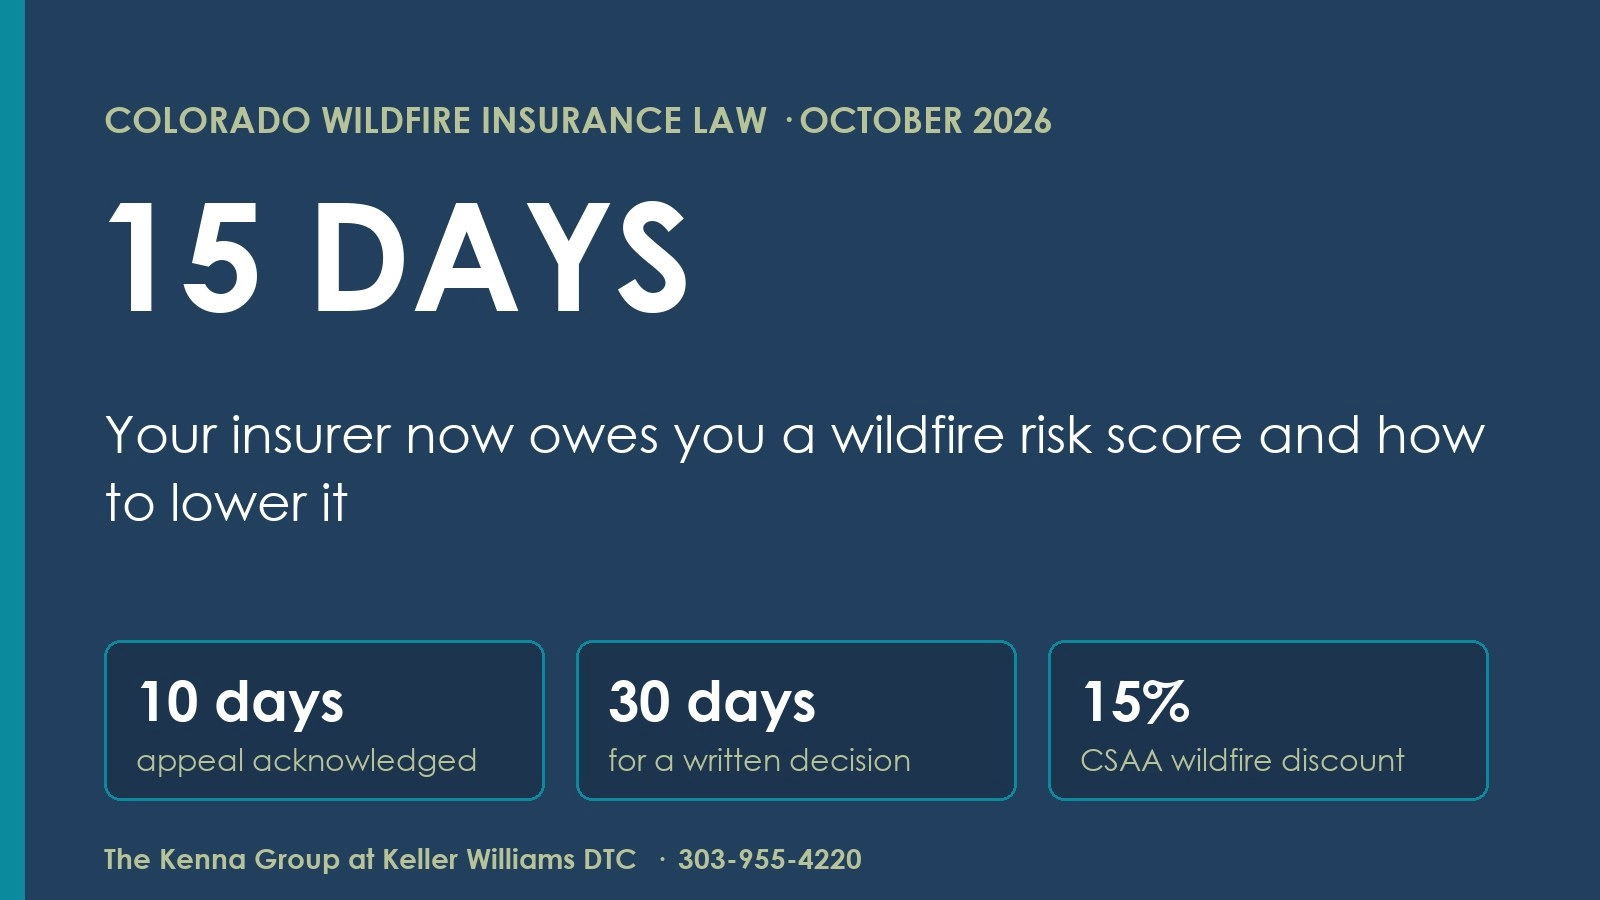
Colorado's wildfire insurance law, HB25-1182, now makes your home insurer show you its wildfire risk score, explain it in plain language and tell you how to lower it. The Colorado Division of Insurance says the wildfire risk score notices started October 1, 2026, at application and at renewal. If you own or are buying a home in Evergreen, Conifer, Woodland Park, Monument or Castle Rock, this notice is now part of your home insurance cost, and you have the right to appeal it.
Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree.
15 days Score and explanation after you apply For new applicants, per the Division of Insurance | 10 days Insurer must acknowledge your appeal Calendar days from a formal appeal |
30 days Final written appeal decision Coverage continues 10+ days past the decision | 15% CSAA discount on the wildfire portion With a Wildfire Prepared Home designation |
The Colorado Division of Insurance announced the new rules on October 12, 2026, and KKTV 11 News in Colorado Springs reported on them October 16. The law is HB25-1182, Risk Model Use in Property Insurance, signed in 2025. It applies when an insurer uses a wildfire risk model, catastrophe model or score to price, underwrite, surcharge or non-renew a homeowners policy. It covers admitted insurers and the Colorado FAIR Plan. The Division says it does not cover non-admitted or surplus lines insurers.
Per the Division of Insurance, the written wildfire risk notice has to include six things, and it cannot sit in fine print:
| Step | Deadline under HB25-1182 |
|---|---|
| New applicant gets the score and explanation | Within 15 days of a completed application |
| Existing policyholder gets the score | With the renewal offer, or with a nonrenewal notice |
| Insurer reviews your mitigation evidence | Within 30 days, updating the score if it applies |
| Insurer acknowledges a formal appeal | Within 10 calendar days |
| Final written appeal decision | Within 30 calendar days |
| Coverage if the decision lands after expiration | Continues at least 10 calendar days past the decision notice |
Insurers that use wildfire models must also count verified mitigation work. The Division says insurers either build property-level and community-level mitigation into their pricing models or give a discount to policyholders who show qualified work, such as a designation from IBHS, the insurance industry research group behind the Wildfire Prepared Home program. Each insurer must post its mitigation discounts and appeal steps on its website, or post that it offers no discount.
Two insurers are named in the Division's release. CSAA General Insurance Company offers up to a 15% discount on the wildfire portion of the premium, not the whole bill, for homes with an IBHS Wildfire Prepared Home Essential or Enhanced designation that meet its underwriting rules. State Farm is expanding where it writes policies, and the Division says high-risk homes with a Wildfire Prepared Home designation can qualify if they meet State Farm's eligibility rules. KKTV reports Teller County Commissioner Dan Williams has taken hundreds of calls from homeowners who lost coverage, with some premiums tripling or quadrupling.
Buyers. Apply for insurance the day you go under contract: the insurer has 15 days to send the score, and the Colorado purchase contract gives you a property insurance objection deadline. In Evergreen, where 230 homes are for sale at an average list price of $1,349,488, a bad score is a reason to negotiate, not a surprise after closing. Read how to check the wildfire score before you decide and why insurance can break a Denver metro house payment.
Sellers. Mitigation paperwork is now worth money to your buyer. Gather receipts for defensible space, roof class and vent upgrades, and any Wildfire Prepared Home designation, and put them in the listing file. In Woodland Park, the 134 homes for sale average 96 days on market: a lower insurance quote helps your home stand out. Get a free home value report and see whether to repair or replace your roof before selling.
Homeowners. Look for the wildfire risk notice with your next renewal. If you cleared brush, replaced a roof or added ember-resistant vents and the score ignores it, send the evidence and file a formal appeal. The insurer owes you an answer in writing within 30 calendar days. Pair this with the state roof grant program in Colorado hail-resistant roof grants.
The Colorado market. Foothills homes already sit longer than the metro: 87 days in Evergreen, 96 in Woodland Park and 100 in Monument on kennarealestate.com today. Insurance cost is part of the payment, so a home with a strong score and mitigation proof wins buyers in a slow fall market. See the September 2026 Colorado home sales numbers.
What to watch out for
The fastest way to lower a wildfire risk score in Colorado is verified mitigation that your insurer counts, then an appeal with the proof. KKTV lists clearing brush, removing pine needles and fire-resistant upgrades as examples. IBHS says its Wildfire Prepared Home Essential level focuses on wind-blown embers, the leading cause of home ignitions, and most existing homes can be retrofitted to reach it. The Enhanced level adds protection against flames and radiant heat, and IBHS says it is reached most during new construction or a major exterior remodel.
Teller County funds wood chippers and vegetation removal help, per KKTV. Ask your county or fire district what it offers before you hire out the work. Budget the premium into your payment on the Colorado mortgage calculator, check today's Colorado mortgage rates and plan your closing costs in Colorado. More on coverage: owning a home in a Colorado wildfire-prone area and what Colorado homeowners insurance covers.
Active listings on kennarealestate.com, October 17, 2026
| Area | Homes for sale | Average list price | Average days on market |
|---|---|---|---|
| Evergreen | 230 | $1,349,488 | 87 |
| Conifer | 84 | $1,239,592 | 78 |
| Morrison | 100 | $1,148,029 | 84 |
| Golden | 266 | $1,099,812 | 86 |
| Castle Rock | 569 | $1,010,287 | 86 |
| Monument | 255 | $830,462 | 100 |
| Woodland Park | 134 | $618,365 | 96 |
| Colorado Springs | 3,165 | $565,316 | 80 |
Active residential listings on kennarealestate.com on October 17, 2026. In Evergreen, 108 homes are listed between $600,000 and $1,200,000, averaging $878,481. Browse all Jefferson County homes for sale, plus Bailey and Idaho Springs, and read Fannie Mae's 2027 rate forecast before you set your budget.


HB25-1182, Risk Model Use in Property Insurance. When a Colorado insurer uses a wildfire risk model or score, it must give you the score, explain it, show how mitigation changes it and let you appeal. The Division of Insurance says notices started October 1, 2026.
Your insurer sends it. New applicants get the score and explanation within 15 days of a completed application. Existing policyholders get it with the renewal offer or a nonrenewal notice.
Yes. File a formal appeal with your insurer. It must acknowledge the appeal within 10 calendar days and send a final written decision within 30 calendar days. If you send mitigation evidence, the insurer reviews it and updates the score within 30 days if it applies.
Insurers using wildfire models must count qualified mitigation in their pricing or give a discount. CSAA General Insurance Company offers up to 15% off the wildfire portion of the premium for homes with an IBHS Wildfire Prepared Home designation that meet its underwriting rules.
The Colorado Division of Insurance. Consumer Services is 303-894-7490, or file online at doi.colorado.gov if an insurer misses the notice deadline, refuses to review your mitigation evidence or denies a discount without a written reason.
Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree.
Brian Lee Burke, the hardest working man in real estate
The Kenna Group at Keller Williams DTC. Helping You With Your Pad™. Licensed since 2003.
The Kenna Group is a real estate group with Keller Williams Realty DTC, LLC (Keller Williams DTC), serving Denver metro and Colorado home buyers and sellers.