New - 6 Hours Ago


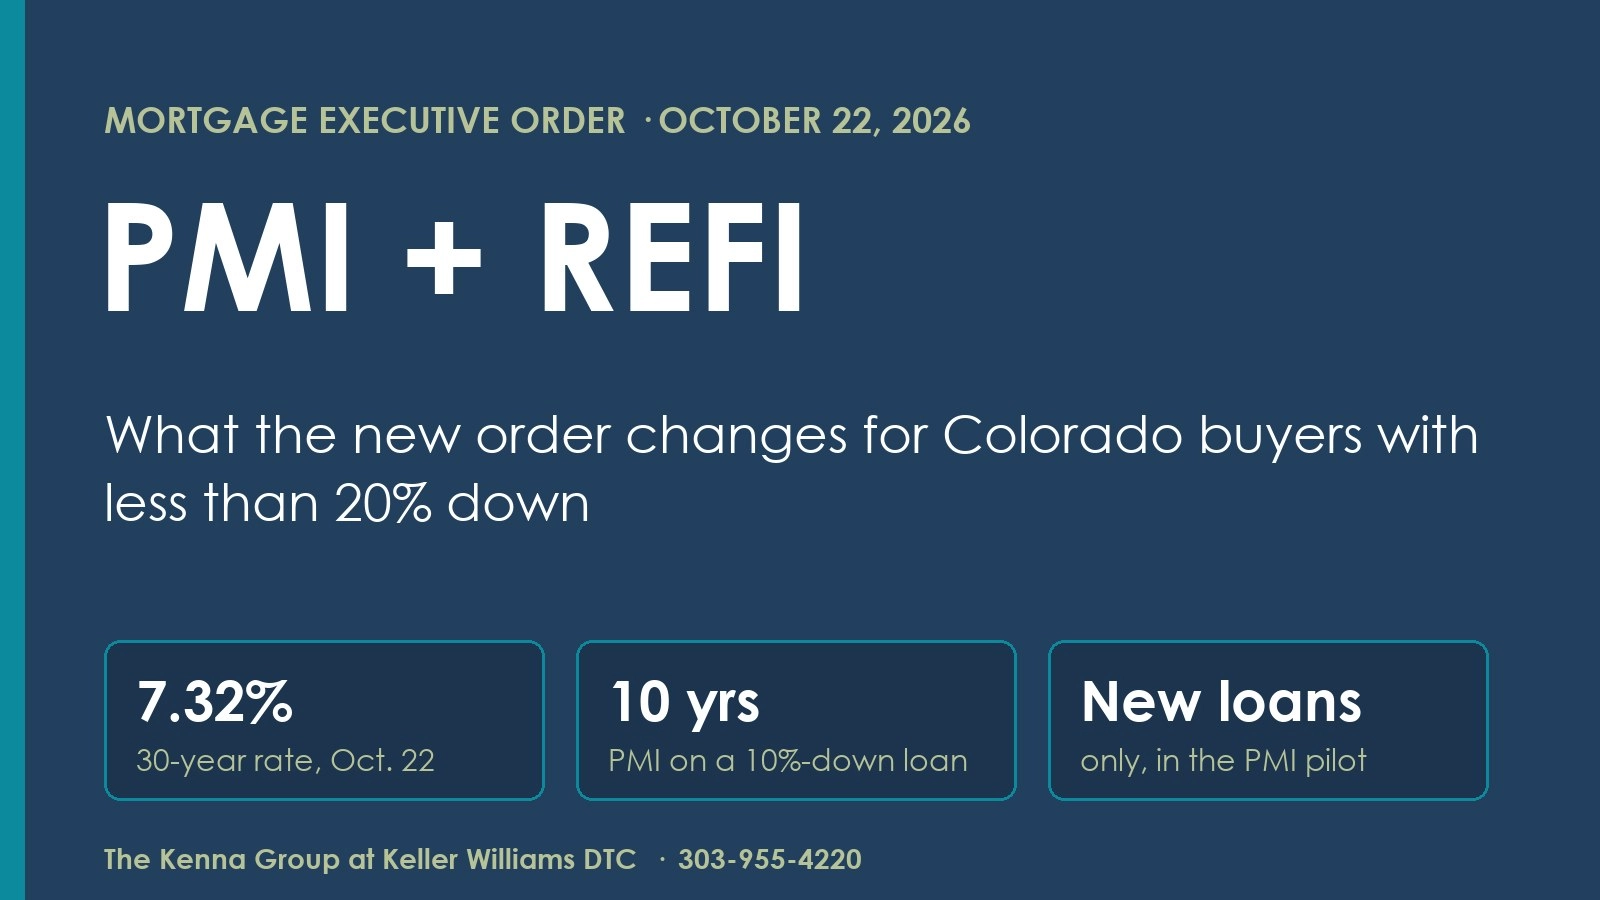
The new mortgage executive order, signed October 22, 2026, goes after two costs Colorado buyers pay: private mortgage insurance (PMI) and the title fees on a refinance. The White House fact sheet directs the Federal Housing Finance Agency (FHFA) to build a pilot that cancels PMI once a borrower has enough equity based on today's home value, and to make a title-insurance waiver for refinances permanent. If you are buying in Aurora, Denver, Littleton or Colorado Springs with less than 20% down, here is what changes for you, what does not, and the math at a 7.32% rate.
Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree.
Oct. 22 Mortgage executive order signed White House fact sheet | 7.32% 30-year fixed mortgage rate Freddie Mac, October 22, 2026 |
$500-$1,500 Closing-cost savings, refi title waiver FHFA estimate, 2024, via Beinsure | New loans Only loans made after the PMI pilot starts Insurance Business |
The White House fact sheet, dated October 22, lists four parts to the order, titled "Decreasing Housing Costs for the American People":
The fact sheet gives no start dates, no equity thresholds and no dollar savings. Insurance Business reports the PMI pilot covers only loans made after it launches, so borrowers already paying PMI do not benefit directly. The U.S. Mortgage Insurers trade group points out the order asks the FHFA to consider a pilot, not to launch one on a set date. Freddie Mac put the 30-year fixed rate at 7.32% on October 22, down from 7.40% a week earlier and up from 6.19% a year ago.
| Part of the order | Who it helps | What we know today |
|---|---|---|
| PMI cancellation pilot | New Fannie Mae and Freddie Mac borrowers with under 20% down | No start date; new loans only |
| Refi title-insurance waiver | Homeowners who refinance | $500-$1,500 savings (FHFA estimate, 2024) |
| VA and USDA direct-loan rates | Borrowers with loans made by those departments | No size or date given |
| Manufactured housing task force | Buyers of factory-built homes | Report due in 180 days |
| 30-year fixed rate | Every buyer | 7.32% (6.19% a year ago), Freddie Mac |
Buyers. PMI is the cost of putting less than 20% down on a conventional loan, and Fannie Mae puts it at 0.2% to 2% of the loan a year, per Beinsure. On a $500,000 Aurora home with 10% down, that is $75 to $750 a month on top of $3,091 in principal and interest at 7.32%. Under today's rules, PMI on that loan ends on its own at 78% of the original value, which takes 119 payments, nearly 10 years. Shop PMI quotes and credit scores before you shop houses: run your numbers on the Colorado mortgage calculator.
Sellers. Nothing in the order lowers a buyer's payment this month, so Colorado buyers still need help at the closing table. Offer a seller-paid buydown or closing costs instead of a bigger price cut: see how seller concessions work in Colorado and the 3-2-1 rate buydown program. Start with a home value report.
Homeowners. If you pay PMI today, you do not need a pilot. Federal law already lets you ask to cancel at 80% of the original value, and coverage ends on its own at 78%, per Insurance Business. If your home has gained value, ask your servicer what it takes to drop PMI with a new appraisal. The refi title waiver matters once rates fall: on a refinance, $500 to $1,500 less in closing costs shortens your break-even.
The Colorado market. A value-based PMI rule pays off when prices climb. 9NEWS reported Denver's average sales price fell 2% in September from a year earlier, so equity from price gains is slow right now; on our $450,000 example loan the home has to be worth $562,500 for 80% loan-to-value. Today, kennarealestate.com shows 1,497 Denver homes and 971 Aurora homes listed between $400,000 and $700,000, the range where most low-down-payment buyers shop. See why Denver has more sellers than buyers.
What to watch out for
To pay less for PMI on a Colorado home, raise your credit score, put more down where it moves the price tier, and set a plan to cancel PMI at 80%. The order we use with our buyers:
Active listings on kennarealestate.com, October 26, 2026
| Area | Homes for sale | Average list price | Average days on market |
|---|---|---|---|
| Denver | 3,858 | $689,306 | 89 |
| Colorado Springs | 3,128 | $567,692 | 84 |
| Aurora | 1,939 | $469,030 | 85 |
| Littleton | 861 | $789,734 | 80 |
| Parker | 586 | $853,413 | 80 |
| Castle Rock | 549 | $1,016,985 | 89 |
| Arvada | 524 | $675,702 | 72 |
| Lakewood | 424 | $566,961 | 81 |
| Thornton | 415 | $491,219 | 69 |
| Centennial | 283 | $670,302 | 68 |
| Highlands Ranch | 227 | $718,608 | 67 |
Active residential listings on kennarealestate.com on October 26, 2026. Looking for a lower payment? See affordable homes in Aurora, affordable homes in Denver and homes with assumable mortgages, where the seller's lower rate comes with the house.




Signed October 22, 2026, it directs the FHFA to create a pilot that cancels PMI once a borrower has enough equity based on current home value, makes a refinance title-insurance waiver permanent, tells the VA and USDA to cut rates on their direct loans, and sets up a manufactured housing task force.
No. Insurance Business reports the PMI pilot covers only loans made after it launches. If you pay PMI now, federal law already lets you ask to cancel at 80% of the original value, and it ends on its own at 78%.
No date is set. The White House fact sheet gives no start date, equity threshold or savings estimate, and the U.S. Mortgage Insurers group says the order asks the FHFA to consider a pilot.
Fannie Mae puts PMI at 0.2% to 2% of the loan a year, per Beinsure. On a $450,000 loan that is $75 to $750 a month. Your credit score and down payment set your price.
Freddie Mac's survey put the 30-year fixed rate at 7.32% on October 22, 2026, down from 7.40% a week earlier and up from 6.19% a year ago. Your rate depends on credit, down payment and loan type.
Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree.
Brian Lee Burke, the hardest working man in real estate
The Kenna Group at Keller Williams DTC. Helping You With Your Pad™. Licensed since 2003.
The Kenna Group is a real estate group with Keller Williams Realty DTC, LLC (Keller Williams DTC), serving Denver metro and Colorado home buyers and sellers.