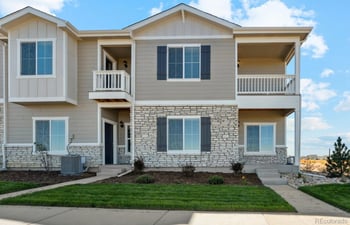
$422,900
Active
3
Beds
3
Baths
1631
Sqft
0.05
Acres
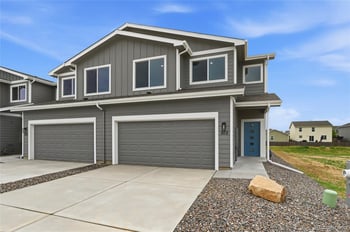
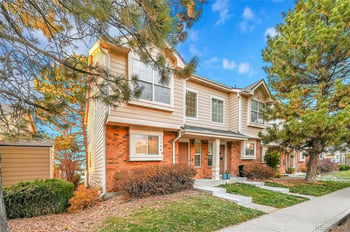
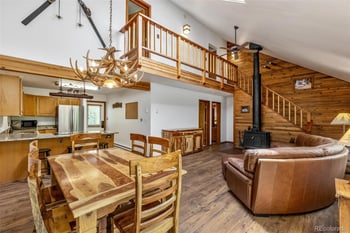
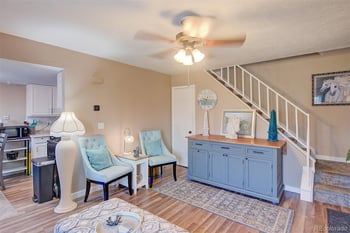
926 Montbello Ave, Fort Lupton, CO 80621
MLS#: REC2218367


Is it better to rent or buy a home in Colorado with mortgage rates above 7%? Here is the short answer for October 2026. Renting costs less every month in Denver, Colorado Springs, Greeley and Fort Collins at today's 7.28% rate. Buying a home in Colorado still comes out ahead once you stay 6 to 10 years, and sooner when you buy below list price, get the seller to pay down your rate, or take over an assumable mortgage. Below is the rent vs buy math for each Colorado market, the break-even year, and what to watch out for.
Today's 30-year and 15-year numbers are on the current Colorado mortgage rates page, updated weekly.
Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree.
Get your own rent-or-buy numbers
Text us your rent and the town you want. The Kenna Real Estate Group runs the monthly cost, the break-even year and the homes that fit, at no cost. Or start with Can I afford a home now? and the Colorado homes under $450K list, updated daily.
Freddie Mac's 30-year fixed average is 7.28% for the week of October 1, 2026, up from 6.55% in mid-July. Home prices across the Front Range held flat while rents fell.
7.28% 30-year fixed rate Oct 1, 2026, up from 6.55% in July | $650,000 Denver metro single-family median Year to date, flat for three years |
$365,500 Denver metro condo and townhome median September, down 6.28% from last year | $2,000 Average Denver rent September, $195 less than last year |
Statewide, the Colorado median sale price is $550,000 and the state has 4.8 months of supply. Metro Denver closed September with 13,567 active listings and 4.76 months of inventory. More homes on the market means buyers set more of the terms. Read why Denver is a buyer’s market and who is buying a home at 7%.
Renting is cheaper per month in all four Colorado examples below. The gap runs from $1,143 a month on a Denver metro townhome to $2,094 a month on a Denver metro single-family home.
Monthly cost to own vs rent, Colorado, October 2026
The owning cost is the full monthly bill, not the principal and interest alone:
| Home | Principal + interest | Tax + insurance | HOA + mortgage insurance | Own, all-in | Rent |
|---|---|---|---|---|---|
| Denver metro townhome, $365,500, 5% down | $2,376 | $368 | $495 | $3,238 | $2,095 (2-bed) |
| Colorado Springs home, $470,000, 5% down | $3,055 | $546 | $186 | $3,787 | $2,200 (3-bed house) |
| Greeley home, $499,900, 5% down | $3,249 | $600 | $198 | $4,047 | $2,400 (3-bed house) |
| Denver metro single-family, $650,000, 10% down | $4,003 | $698 | $244 | $4,944 | $2,850 (3-bed) |
Colorado property tax is among the lowest in the country, which keeps the tax line small. Insurance is the opposite: hail makes Colorado one of the most expensive states to insure a home, and a house policy here runs $4,200 a year in our examples. New-build suburbs add a metro district tax on top of the county bill, and townhomes add HOA dues. See HOA fees in Colorado before you pick a neighborhood.
At full price and 7.28%, buying beats renting after 8.6 to 9.8 years in our Colorado examples. A lower price, a seller-paid rate buydown or an assumable loan pulls that date in to 2.6 to 7 years.
The break-even year is the month your home equity, after a 7% cost to sell, passes every extra dollar you spent to own: the down payment, closing costs and the monthly gap over rent. The examples assume the home gains 3% a year and rent rises 3% a year, the same pace for both.
Years until buying beats renting, Colorado, October 2026
The lesson for Colorado buyers in 2026: the price and the rate you negotiate decide whether buying wins in 6 years or 10. A 3% price cut plus a seller credit that buys the rate down to 6.53% saves $250 a month on the Denver townhome and moves the break-even from 8.6 years to 6.2 years. Colorado sellers are paying those credits right now. See how to ask for seller concessions in Colorado.
The good
The bad
What to watch out for when you buy in Colorado
Already own and thinking about moving up? See how to sell and buy at the same time in Colorado and get a home value report first.
Renting costs less per month in every Colorado market we ran at the October 2026 rate of 7.28%. Buying wins once you stay 6 to 10 years, and sooner with a price cut, a seller-paid rate buydown or an assumable loan.
Renting is cheaper per month. A Denver metro townhome at the $365,500 median costs $3,238 a month to own with 5% down, against $2,095 for a 2-bedroom rental. A $650,000 single-family home costs $4,944 a month against $2,850 rent.
Buy at 7% if you plan to stay 7 years or longer, you have cash left after closing, and the payment fits your budget today. Negotiate a seller-paid buydown and refinance if rates fall. If you move within 5 years, rent.
In our Colorado examples, 8.6 to 9.8 years at full price and 7.28%. A 3% price cut plus a seller-paid buydown to 6.53% cuts that to 6.2 to 7 years. An assumable 3.25% loan cuts it to 2.6 years.
Prices are flat, not falling: the Denver metro single-family median has held at $650,000 for three years, and the statewide median is $550,000. Condo and townhome prices fell 6.28% over the last year, so attached homes are where buyers find the biggest price cuts.
For the $365,500 Denver metro townhome at 7.28% with 5% down, the full payment is $3,238 a month. At a 43% debt-to-income ratio with no other debts, that takes a household income of $90,400 a year.
No. Rent buys housing with no repair bills and no 7% cost to sell. Buying builds equity, but only pays off once you stay long enough, which is 6 to 10 years at today's rates.
The seller pays the lender at closing to lower your interest rate. A permanent buydown from 7.28% to 6.53% on a $347,225 loan cuts principal and interest from $2,376 to $2,136 a month. A 2-1 buydown lowers the rate for 2 years only.
Colorado ranks among the most expensive states for home insurance because of hail. Our examples use $4,200 a year on a single-family home and $2,400 on a townhome, where the HOA policy covers the exterior. Get a quote before your inspection deadline.
Yes. CHFA offers down payment assistance starting at a 620 credit score, and the Kenna Real Estate Group works a $1,000 cash-to-close program on homes under $600,000. Call or text 303-955-4220 to check which one fits you.
Tell us your rent, your town and your move date. We send back the monthly cost to own, your break-even year and the homes under your number. The Kenna Real Estate Group helps Colorado buyers from Fort Collins to Pueblo.
Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree.