New - Just Now
$459,900
Active
5
Beds
3
Baths
2424
Sqft
0.1464
Acres
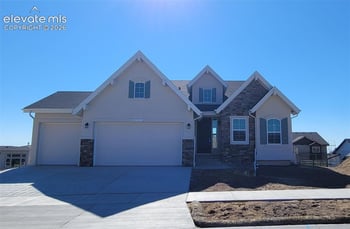
6705 Sleeping Giant Dr, Colorado Springs, CO 80923
MLS#: 4872736


A couple with two incomes and under $25,000 in savings buys a first home in Colorado with one of seven tools: CHFA down payment assistance, metroDPA, an FHA loan at 3.5% down, a rent-to-own lease option, a condo or townhome, an FHA-financed duplex they live in, or a co-buy with another household. Each one lowers the cash to close or the monthly payment by a set amount, and most of them stack. This guide gives the Front Range numbers for each path, who qualifies, and where the payment lands on a $400,000 to $500,000 purchase in the Denver metro, Colorado Springs, Greeley and Pueblo.
The Denver metro median sale price sits above $600,000 for a detached home and near $400,000 for a condo or townhome. Colorado Springs runs $150,000 under Denver. Greeley, Evans, Pueblo, Fountain and the east side of Aurora have the most detached homes under $450,000 on the Front Range. The chart below is the payment on $450,000, 30-year fixed, principal and interest only, before taxes, insurance and HOA dues.
| Path | Cash to close on $450,000 | Monthly P&I at 6.5% | Extra monthly |
|---|---|---|---|
| Conventional, 5% down | $22,500 plus $9,000 to $13,000 closing | $2,700 | PMI $150 to $250 |
| FHA, 3.5% down | $15,750 plus $9,000 to $13,000 closing | $2,790 on the higher loan | FHA MIP $200 to $300 |
| FHA plus CHFA 3% grant | $2,250 plus closing | $2,790 | MIP $200 to $300 |
| FHA plus metroDPA 5% second loan | $0 down plus closing | $2,790 | MIP; second loan forgiven over time |
| Rent-to-own, 3% option fee | $13,500 option fee | Rent $2,600 to $3,200 | Rent credit $200 to $400 toward purchase |
| Duplex, FHA, live in one unit | $15,750 on $450,000 | $2,790 | Minus $1,600 to $2,000 rent from unit two |
Closing costs on the Front Range run 2% to 3% of the price, and sellers in the 2026 Denver market agree to pay part of them on most offers under $600,000. The closing costs for Colorado home buyers page itemizes them.
The Colorado Housing and Finance Authority (CHFA) is the state's housing finance agency. It pairs a first mortgage (FHA, VA, USDA or conventional) with down payment help in two forms: a grant of up to 3% of the first mortgage that is never repaid, or a second mortgage of up to 4% at 0% interest with no monthly payment, due when you sell or refinance. The rules that matter for a couple:
CHFA works through approved lenders, not directly. The Colorado homebuyers benefit from expanded CHFA down payment assistance post covers the program details, and educators have a separate CHFA track covered in the teacher homebuying programs in Colorado post.
metroDPA is the Denver metro's regional down payment assistance program, sponsored by the City and County of Denver and offered in participating cities and counties across the metro, including Aurora, Arvada, Lakewood, Littleton, Englewood, Westminster, Thornton, Brighton, Commerce City, Adams County, Arapahoe County, Jefferson County and Douglas County. It provides a second loan of up to 5% of the first mortgage, forgiven over a set number of years of living in the home, with income limits above $150,000 for a household. It is not limited to first-time buyers and it pairs with FHA, VA and conventional first mortgages. A $450,000 purchase with an FHA first mortgage and a metroDPA second at 5% closes with the buyer paying closing costs only. Terms and participating cities change by year; confirm the current list with the lender before the offer.
FHA is the default first mortgage for Colorado couples with a 580 to 680 credit score or a thin savings account. 3.5% down, a 580 minimum score at that down payment, debt-to-income up to 50% with compensating factors, and seller-paid closing costs up to 6%. FHA loan limits in the Denver metro counties sit above $800,000 for a single unit and higher for a duplex, triplex and fourplex, which is what makes the house-hacking path below work. The trade-off is mortgage insurance for the life of the loan at 3.5% down; refinance out of it at 20% equity. The FHA vs conventional loans for Colorado buyers page runs the comparison, and the government-backed home buying guide covers VA at 0% down for eligible service members and veterans.
A rent-to-own lease option puts a couple in the house now, at a rent set in the contract, with the right to buy at a fixed price inside 1 to 3 years. An option fee of 2% to 5% of the price is paid up front and credited to the purchase; a rent credit of $200 to $400 a month adds to it. The couple uses the lease period to raise a credit score, season income from a new job or self-employment, or wait out a bankruptcy or short sale waiting period. Two rules protect the buyer in Colorado: the option fee and the rent credit must be in the written agreement, and the purchase price must be fixed, not "market at the time." Search current lease-option homes on the Colorado rent-to-own homes page and the Denver rent-to-own homes page; Colorado Springs and Greeley have their own inventory on the Colorado Springs rent-to-own and Greeley rent-to-own homes pages.
The Denver metro condo and townhome median runs $200,000 under detached homes, and 2026 inventory is up from 2024 and 2025, which puts buyers in control of price and concessions. The number to check is the HOA: $250 to $600 a month on most Denver, Aurora, Lakewood and Littleton condos, covering the roof, exterior, water and sometimes heat. Add it to the payment. Two Colorado-specific checks before the offer: the HOA's reserve study and any pending special assessment, and whether the building is on the FHA-approved list, since an FHA loan on a condo requires it. The Colorado condos for sale page and the condo vs townhome living in Denver post cover the equity math, and the HOA special assessment before closing post covers the surprise bill.
FHA finances a 2 to 4 unit property at 3.5% down when the buyer lives in one unit for at least a year, and the lender counts 75% of the rent from the other units as income on the application. A $550,000 duplex in Aurora, Lakewood, Englewood, Wheat Ridge or west Denver with a $2,000 rent from the second unit brings a $3,400 payment down to a net $1,400. That is the cheapest way to own a detached structure in the metro. The catch is the inventory: 2 to 4 unit properties are a small share of listings, and half of them need work. The Denver house hacking guide and the Colorado duplex and multifamily buying guide cover the search and the lender's rent calculation. Denver's ADU rules, which now allow an accessory dwelling unit on most residential lots in the city, open the same path on a single-family lot; the Denver ADU policy for buyers and house hackers post explains it.
Two couples, or a couple and a sibling or parent, buy one home and hold title as tenants in common with a written co-ownership agreement. Two incomes become four on the application, and a $700,000 Arvada or Centennial home with a basement suite becomes two $350,000 shares. Colorado title companies handle tenants-in-common vesting every day; the agreement that spells out shares, the exit, the buyout price and who pays what is the part to get from a Colorado attorney for $1,000 to $2,500. The co-buying a house in Colorado post walks through the agreement and the loan.
The paths stack in one order: pick the mortgage (FHA, VA or conventional), add CHFA or metroDPA to it, and choose the property type that fits the payment. Get the pre-approval first; the Colorado mortgage pre-approval guide lists what the lender needs, and the first-time home buyer guide for Colorado runs the full timeline from pre-approval to keys. Couples with a credit score under 620 start with Kenna Credit Care mortgage readiness and buy 6 to 12 months later on better terms.
The Kenna Real Estate Group at Keller Williams DTC matches Colorado couples to the assistance program, loan and property type that gets them to a closing table this year, and connects them with the lenders who run CHFA and metroDPA every week. Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree. Set a price cap and a property type and search every home for sale in Colorado.
Questions about any home in Colorado? Call or text 303-955-4220. A live person answers.
$2,250 to $15,750 down with FHA plus CHFA or metroDPA, plus $9,000 to $13,000 in closing costs that the seller pays part of on most 2026 Denver metro offers.
No on most CHFA programs. The requirements are a 620 credit score, county income limits, a homebuyer education class and $1,000 of your own money.
No. Each one is a second-lien assistance program on the same first mortgage, so the lender picks the one that fits your income, county and price.
580 at 3.5% down. Between 500 and 579 requires 10% down. CHFA layered on top requires 620.
Yes. A lease with a written purchase option, a fixed price, a stated option fee and a stated monthly rent credit is enforceable. A price set as 'market value at the time of purchase' is the term to refuse.
The lender counts 75% of the rent from the other unit as qualifying income, and you must live in your unit for at least one year.
$250 to $600 a month on most Denver, Aurora, Lakewood and Littleton condos, covering roof, exterior, water and sometimes heat. Check the reserve study and pending special assessments before the offer.