New - 19 Hours Ago
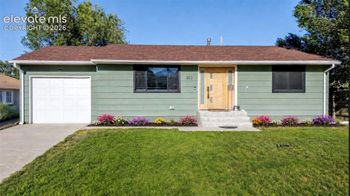
$362,950
Active
3
Beds
2
Baths
1788
Sqft
0.15
Acres
803 Tia Juana St, Colorado Springs, CO 80909
MLS#: 7002793


Shared appreciation means CHFA's Colorado Schools-to-Home Program puts up to 25% of a home's purchase price toward a school employee's down payment today, with no monthly payment on that money, and gets a share of the home's increase in value back when the employee sells, refinances or pays off the loan.
Think of Schools-to-Home as a partner that funds a large share of the down payment upfront and asks for nothing monthly in return. When the home is eventually sold, refinanced or paid off, that partner is repaid the original amount plus a percentage of how much the home appreciated. In this program the partner is Colorado's Public School Permanent Fund, the trust that helps fund Colorado K-12 education, so the appreciation share goes back into the fund that keeps the program running for the next school employee in line.
Eligibility covers any employee of a Colorado public school district or eligible school, not just teachers: bus drivers, custodians, paraprofessionals, cafeteria staff, administrators and support staff can all qualify. The requirement is active employment with a Colorado public school district or eligible school at the time of purchase.
| Feature | Detail |
|---|---|
| Assistance amount | Up to 25% of the first mortgage |
| Monthly payments on the second loan | None, deferred until a repayment event |
| Repayment triggers | Sale, refinance, payoff, end of term, or move-out |
| Who qualifies | Colorado public school employees, all roles |
| Program launch | July 2026 |
| First mortgage type | Fixed-rate CHFA loan |
| Appreciation recipient | Public School Permanent Fund, Colorado K-12 |
| Required education | "Understanding Your Financial Commitment" course |
The honest comparison for most school employees is not "Schools-to-Home versus a full 20% down payment saved in cash." It is Schools-to-Home versus continuing to rent. On a $500,000 home that appreciates to $600,000, a Schools-to-Home buyer shares part of that $100,000 gain, keeps whatever principal is paid down on the first mortgage, and keeps the remaining appreciation, building real equity. A renter over the same years builds $0 equity, keeps $0 of any appreciation, and the rent paid is gone. Sharing part of the appreciation on a home owned outperforms keeping all of the appreciation on a home never bought.
No. The buyer holds full title to the home. The Public School Permanent Fund holds a second mortgage lien and a contractual right to a percentage of the appreciation; it has no ownership stake, no say in paint colors, and no claim on the home beyond that lien and appreciation right.
The program is not the right fit for every situation. Weigh it carefully if any of these apply:
None of these rule the program out; they are reasons to run the specific numbers before committing, which is exactly why CHFA requires the "Understanding Your Financial Commitment" course before closing.
The appreciation share applies only to appreciation actually gained; CHFA's required financial commitment course covers the repayment mechanics for flat and declining markets as part of the standard disclosure. A buyer in that situation still owes the original second mortgage amount, since that portion is a loan rather than an investment stake, but owes no share of a gain that never happened.
The Public School Permanent Fund is a Colorado trust that has helped fund K-12 education for more than a century, and Schools-to-Home is structured so the appreciation share repaid by buyers flows back into that same fund rather than to a private investor or a bank's shareholders. That structure is also why the program is limited to school employees specifically: the fund that supports Colorado classrooms is, in effect, helping the people who staff those classrooms become homeowners.
Refinancing the first mortgage is a triggering event for repayment of the second mortgage and its appreciation share, so a school employee weighing a future refinance should compare the rate savings against the cost of settling the shared appreciation at that time.
CHFA already offers standard down payment assistance to any qualifying Colorado buyer, structured as a smaller second loan with its own repayment terms and no appreciation share attached. Schools-to-Home goes further for eligible school employees specifically: a larger assistance amount, up to 25% of the first mortgage rather than a smaller flat grant, in exchange for sharing part of the home's future appreciation instead of repaying a fixed second loan amount with interest. A school employee should run both structures side by side, standard CHFA assistance plus a smaller down payment versus Schools-to-Home's larger assistance plus an appreciation share, before choosing, since the better option depends on how long the buyer plans to stay and how much the home appreciates over that time.
CHFA-approved lenders will confirm income limits, purchase price limits and the exact appreciation-share percentage once the program's final terms are published ahead of the July 2026 launch. A school employee planning to buy around that timeline can get a head start now by pulling credit, gathering income and employment documentation, and completing the required "Understanding Your Financial Commitment" course as soon as it becomes available, so the application moves quickly once the program opens.
Schools-to-Home is one of several Colorado educator homebuying programs, alongside standard CHFA down payment assistance, metroDPA and other grants. Comparing loan programs and rates matters here as much as anywhere else in home financing; Mike Oswald at Rate (NMLS 261003, Equal Housing Lender) is one resource Colorado school employees use to run those comparisons, and buyers are free to use any lender. A household getting mortgage-ready first can start with Kenna Credit Care.
The Kenna Real Estate Group helps Colorado public school employees compare Schools-to-Home against every other down payment option and run the specific numbers before committing to a purchase. Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree. Ready to see what qualifies? Search every home for sale in Colorado.
Questions about any home in Colorado? Call or text 303-955-4220. A live person answers.
No monthly payments are required on the second mortgage. Repayment of the loan and the appreciation share is deferred until sale, refinance, payoff, end of term, or when the home stops being the primary residence.
No. The buyer holds title. The Public School Permanent Fund holds a second mortgage lien plus a contractual right to a share of appreciation, not an ownership stake.
How improvements interact with the appreciation calculation will be defined in CHFA's final program documents at launch. Ask a lender directly, especially before a major remodel.
The appreciation share applies only to appreciation actually gained. CHFA's required financial commitment course covers repayment in flat and down markets.
Yes, but refinancing triggers repayment of the second mortgage and appreciation share, so weigh refinance savings against that settlement cost.
Any Colorado public school employee: teachers, bus drivers, custodians, paraprofessionals, cafeteria staff, administrators and support staff, as long as employment is active with a Colorado public school district or eligible school.
The program is set to launch in July 2026, pairing a fixed-rate CHFA first mortgage with the second mortgage assistance.
The first mortgage must be a CHFA loan through a CHFA-approved lender. School employees are free to compare lenders and rates before choosing one.


