New - 6 Hours Ago


In the Denver metro right now, renting a home costs $500 to $1,200 a month less than owning the same home with 10% down, and buying wins anyway if you stay 5 years or longer. That is the whole answer: the monthly check favors the renter today, the five-year balance sheet favors the owner, and your time horizon decides which number matters.
This guide puts Front Range numbers on both sides: Denver metro rents, the monthly cost of owning at three price points, the costs each side never sees, and the Colorado programs that move a renter into a home with less than $25,000 in cash. If you have never bought before, keep the first-time home buyer guide for Colorado open in the next tab.
Denver metro rents have held flat since 2023 as a record number of new apartments came onto the market from RiNo to Lone Tree. Current ranges:
Our post on the state of the Denver rental market tracks these ranges by submarket.
Denver metro median close prices sit in the $580,000 to $620,000 range. Owning means PITI (principal, interest, taxes, insurance) plus mortgage insurance under 20% down, plus HOA dues where they apply. The table uses a 6.5% rate as a worked example only; replace it with the rate on your Loan Estimate.
| Home | Down payment | Principal and interest at 6.5% | Taxes, insurance, PMI, HOA | Total to own | Rent for the same home |
|---|---|---|---|---|---|
| $375,000 Denver condo | 5% ($18,750) | $2,250 | $150 tax, $60 insurance, $150 PMI, $350 HOA | $2,960 | $1,850 to $2,400 |
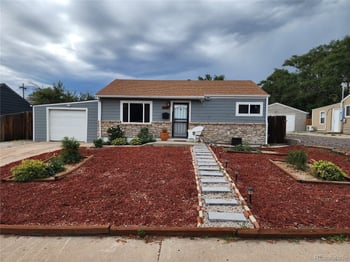
| $600,000 Littleton house | 10% ($60,000) | $3,415 | $270 tax, $250 insurance, $180 PMI | $4,115 | $3,000 to $3,600 |
| $750,000 Highlands Ranch house | 20% ($150,000) | $3,790 | $500 tax, $290 insurance, $60 HOA | $4,640 | $3,600 to $4,500 |
The gap is $500 to $1,200 a month in favor of renting on the house, and $600 to $1,100 on the condo. Every dollar of that gap is the price of the equity, the fixed payment and the tax treatment described below. To see what those price points buy, read what $600K buys in the Denver metro right now.
Use the principal-and-interest cost per $100,000 borrowed on a 30-year fixed loan, then multiply by your loan amount in hundreds of thousands:
A $540,000 loan at 6.0% is 5.4 times $600, or $3,240 a month before taxes and insurance. Rate questions go to a lender, not a headline: the Kenna Real Estate Group works with Mike Oswald, VP of Mortgage Lending at Rate, NMLS 261003, Equal Housing Lender. You are free to use any lender. Current program options are on the Colorado home financing guide.
Five years on a Denver metro single-family home; four on a condo with modest HOA dues; seven or more in a Douglas County metro district where property tax doubles. The break-even arrives when three things outgrow the monthly gap plus the transaction costs:
An owner who itemizes deducts mortgage interest on up to $750,000 of loan balance and up to $10,000 of combined state and local taxes, and sells after two years of residence with up to $250,000 of gain ($500,000 married) excluded from federal capital gains tax. Colorado adds no transfer tax on the purchase; the state documentary fee is one cent per $100 of price, $60 on a $600,000 home. Colorado residential property tax is among the lowest effective rates in the country, which is why a $600,000 central Denver home pays about $3,000 to $3,500 a year. Renters deduct nothing on a federal return.
Our post on buying now or waiting for lower Colorado mortgage rates covers the timing question, and co-buying a house in Colorado covers splitting the purchase with a friend or relative.
Yes, and it is the middle path for a renter who needs 12 to 36 months to fix credit or save the down payment. A lease-purchase locks the price today, credits part of each month's rent toward the purchase, and sets an option deadline. The Colorado rent-to-own program explains the terms, and the Denver rent-to-own homes page lists current homes. Read the option fee and the default clause before signing: a missed payment forfeits the credits in most contracts.
With CHFA assistance and a seller credit, a $450,000 Aurora or Thornton home closes with $10,000 to $16,000 out of pocket. Details are in first-time homebuyer programs in Denver; closing cost line items are in the Colorado closing costs guide.
They lower the entry price and raise the monthly fixed cost. Denver metro condos and townhomes have more inventory and longer days on market than houses, so buyers negotiate harder on them. The risk is the HOA: a special assessment for a roof or a parking structure lands on the owner, not the landlord. Ask for the reserve study and the last two years of HOA minutes during the inspection period. Search current inventory on the Colorado condos page.
Bring three numbers: your current rent, your planned years in Colorado, and a pre-approval letter with the payment on it. Then compare the house you rent to the house you can buy, side by side, using the table above with your real rate. Start with the Colorado mortgage pre-approval guide and look at prices on the Denver home search.
The Kenna Real Estate Group at Keller Williams DTC runs the rent-versus-buy numbers on your actual rent, your actual rate and the actual homes for sale in your price range, and shows you the rent-to-own and down payment assistance paths if buying outright is a year away. Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree. Then search every home for sale in Colorado and compare it to your lease.
Month to month, yes: a $600,000 Littleton house rents for $3,000 to $3,600 and costs about $4,100 to own with 10% down. Over 5 years the owner comes out ahead through principal paydown, a fixed payment and the tax exclusion on the sale.
About 5 years on a Denver metro single-family home, 4 on a condo with modest dues, and 7 or more in a metro district where property tax runs $5,000 to $7,000 a year.
With CHFA down payment assistance and a seller credit, $10,000 to $16,000 out of pocket on a $450,000 home. Without assistance, 3.5% to 5% down plus 2% to 3% closing costs, so $25,000 to $36,000.
No. The state documentary fee is one cent per $100 of price, $60 on a $600,000 home. There is no state or county real estate transfer tax.
30 days after you move out, or up to 60 days when the lease says so, with an itemized list of any deductions.
Yes when the contract is written by a Colorado real estate broker or attorney with a set price, a set option deadline and a clear statement of which payments are credited. Read the default clause: a missed payment forfeits the credits in most agreements.
The rate on your own Loan Estimate. Multiply your loan amount in hundreds of thousands by the per-$100,000 figure for that rate ($600 at 6.0%, $632 at 6.5%) to get principal and interest, then add taxes, insurance, PMI and HOA dues.