New - 2 Hours Ago


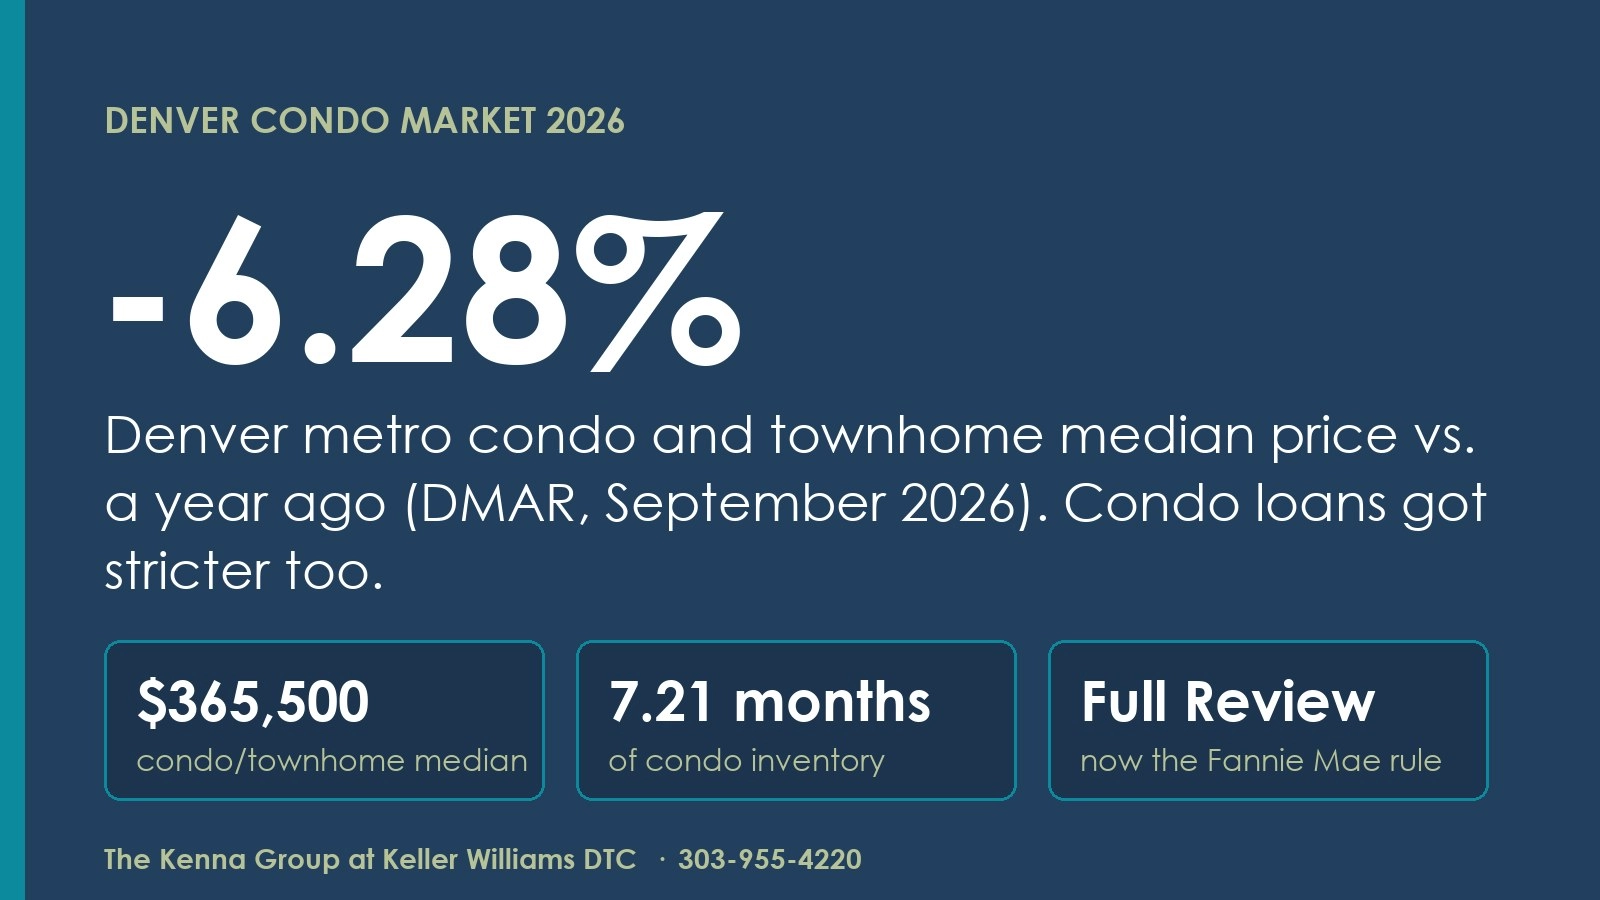
The Denver condo market in 2026 is the softest part of Colorado real estate, and condo loans got stricter. Denver metro condos and townhomes closed at a $365,500 median in September 2026, down 6.28% from a year ago, with 7.21 months of inventory (DMAR, September 2026). And Fannie Mae now requires a full project review for most attached condos; the lighter "Limited Review" is gone from its Selling Guide. Buying or selling a condo in Denver, Aurora, Lakewood or Englewood? Here are the numbers, the loan rules, and the checklist.
Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree.
$365,500 Denver metro condo/townhome median September 2026, down 6.28% from a year ago (DMAR) | 7.21 Months of condo inventory All Denver homes: 4.76 months (DMAR, September 2026) |
7.32% 30-year fixed rate Freddie Mac PMMS, October 22, 2026 | 10% Of the HOA budget to reserves Fannie Mae Full Review test |
No crash, but condos are falling while houses hold. The Denver Metro Association of REALTORS (DMAR) September 2026 report puts the condo and townhome median at $365,500, down 6.28% from September 2025, with 7.21 months of inventory. Across all Denver metro homes, inventory is 4.76 months and sellers received 98.45% of list price. The Colorado Association of REALTORS (CAR) counts the 7-county metro a little differently and lands in the same place:
| Denver metro, September 2026 | Condos and townhomes | Detached homes |
|---|---|---|
| Median price (CAR) | $375,000, down 6.2% | $610,000, down 1.3% |
| Months of supply (CAR) | 6.4 months | 4 months |
| Median price (DMAR) | $365,500, down 6.28% | Year-to-date $650,000, same as the past two years |
Condos and townhomes in the CAR metro numbers averaged 67 days on market. CAR names the reasons: rising HOA fees, insurance costs and affordability. Statewide, CAR reports condo and townhome prices down 7.1% to $395,000, while detached homes slipped 0.9% to $575,000. Higher priced condos run the other way: DMAR reports year-to-date attached sales over $1 million up 6.35%. Watch live inventory on our Denver real estate statistics page and read the full picture in is the Denver housing market crashing?.
Yes, but the building gets reviewed along with you. Fannie Mae updated its condo project standards in Lender Letter LL-2026-03 (March 18, 2026). Its Selling Guide, updated August 5, 2026, lists these review paths:
| The condo you are buying | Fannie Mae project review |
|---|---|
| Attached unit in an established condo project (most Denver condos) | Full Review with the Condo Project Manager tool, FHA project approval, or a Fannie Mae review (streamlined PERS) |
| Attached unit in a new or newly converted project | Full Review with the Condo Project Manager tool, or a Fannie Mae review (standard PERS) |
| Unit in a 2- to 4-unit condo project | Review waived (basic requirements still apply) |
| Unit in a 5- to 10-unit project that is not part of a larger development or master association | Review waived (basic requirements still apply) |
| Detached condo unit | Review waived (basic requirements still apply) |
The old "Limited Review" path is no longer in the list. For an attached condo in an established building, the lender now reviews the whole project.
Per the Fannie Mae Selling Guide (B4-2.2-01), the lender checks, among other items:
Not every buyer needs a Fannie Mae loan. Ask our lender partner whether an FHA, VA or portfolio loan fits a building that fails the review, and check CHFA down payment assistance if you need help with the down payment.
Know your HOA rights before you buy: Colorado HOA laws 2026, our Colorado HOA fees guide and the Denver HOA rules and fees guide.
Buyers. Condos give you the most room to negotiate in Denver right now: 7.21 months of supply and a median down 6.28% (DMAR). Get the building's loan status first, then push on price or a rate buydown; $261 a month separates a 7.32% payment from last year's 6.19% on a $365,500 condo. Start your search on our Denver condos for sale page.
Sellers. Order the HOA budget, reserve numbers, minutes and insurance certificate before you list, so a buyer's lender can start the project review on day one. A building that passes Full Review or holds FHA approval opens the door to more buyers; tell buyers that in the listing. Price against the live competition with a free home value report.
Homeowners. Your HOA's reserves and delinquency rate now decide whether your neighbors' buyers get a loan. Go to the HOA meetings, read the reserve study, and push the board to fund reserves at 10% of the budget or more.
The Colorado market. Statewide, CAR reports condo and townhome prices down 7.1% to $395,000 in September 2026 while detached homes held. Compare condo vs townhome in Denver and read should I buy now or wait for rates.
What to watch out for
These homes are pulled live from the MLS every time you open this page. Browse more on our Colorado condos page, the Denver townhomes guide, or homes for sale in Littleton and Lone Tree.




No crash, but condos are the weakest part of the Denver market. DMAR reports a September 2026 condo and townhome median of $365,500, down 6.28% from a year ago, with 7.21 months of inventory. Detached homes held their year-to-date median of $650,000.
Higher mortgage rates (Freddie Mac 7.32% on October 22, 2026, versus 6.19% a year earlier), rising HOA fees and insurance costs, stricter condo loan reviews, and 7.21 months of condo inventory that lets buyers negotiate.
Yes. For an attached unit in an established condo building, Fannie Mae requires a Full Review, FHA project approval or a Fannie Mae PERS review. Small projects of 2 to 4 units, many 5 to 10 unit projects and detached condos have the project review waived. Ask your lender to check the building before you make an offer.
Yes. Fannie Mae updated its condo project standards in Lender Letter LL-2026-03 (March 18, 2026), and its Selling Guide, updated August 5, 2026, no longer lists Limited Review as a review method. Established attached condos go through Full Review, FHA approval or PERS.
Under Fannie Mae's Full Review, the HOA budget sets aside at least 10% for replacement reserves, or the lender uses an acceptable reserve study instead. No more than 15% of units can be 60 days or more behind on dues.
For prepared buyers, condos offer the most negotiating room in the Denver market: 7.21 months of supply and prices down 6.28% from a year ago (DMAR, September 2026). Confirm the building passes the loan review, then negotiate price, a rate buydown or closing cost credits.
Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree.
Brian Lee Burke, the hardest working man in real estate
The Kenna Group at Keller Williams DTC. Helping You With Your Pad™. Licensed since 2003.
The Kenna Group is a real estate group with Keller Williams Realty DTC, LLC (Keller Williams DTC), serving Denver metro and Colorado home buyers and sellers.